Whole of Life Insurance in the UK, Explained Simply
What is whole of life insurance?
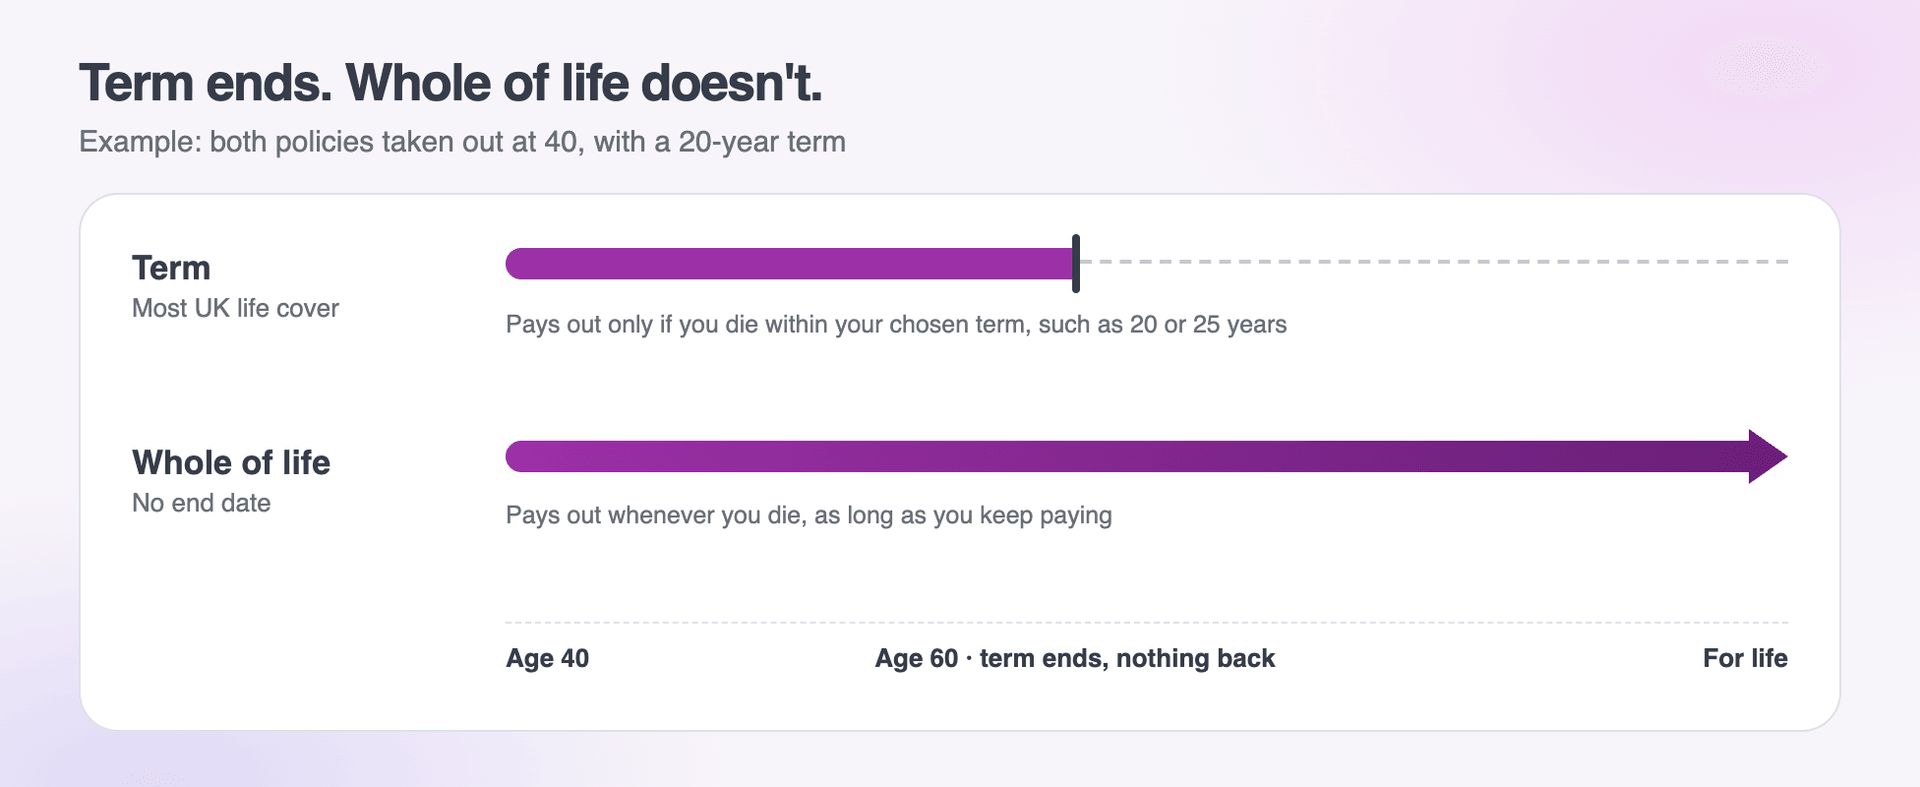
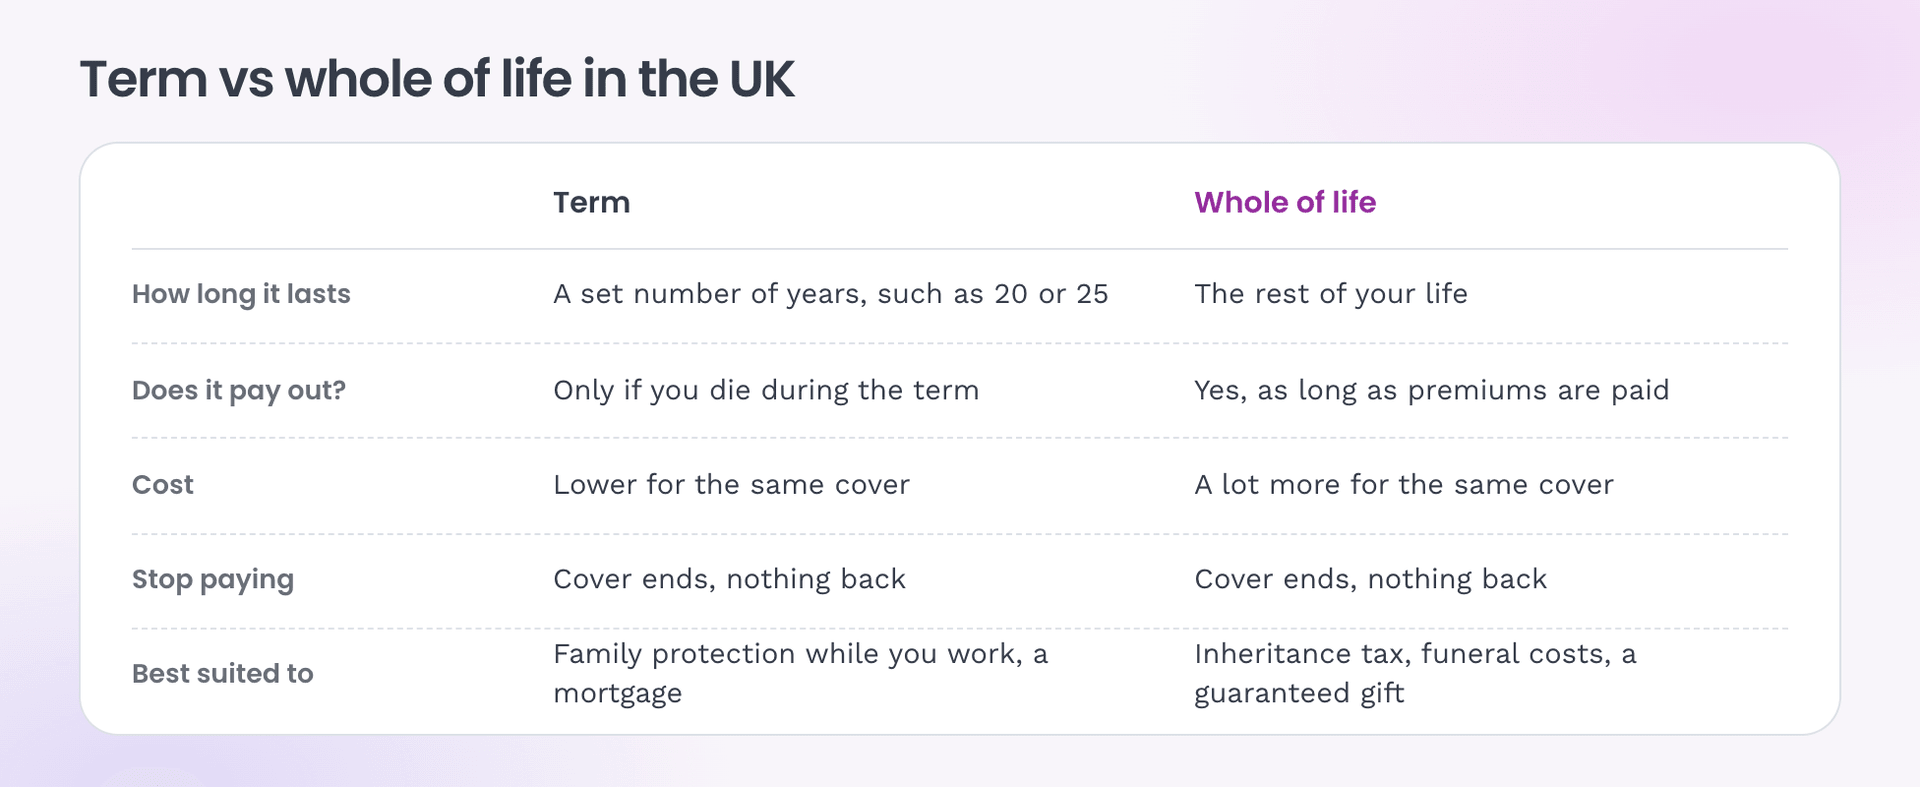
Most life insurance in the UK is term insurance. You pick a number of years, say 20 or 25. If you die during those years, the policy pays out. If you are still alive when the term ends, the policy ends and you get nothing back.
Whole of life insurance works differently. There is no end date. As long as you keep paying the premiums, you stay covered for the rest of your life, and the policy is guaranteed to pay out one day, because the claim is certain to happen eventually. That certainty is also why it costs a lot more than term insurance for the same amount of cover.
People usually buy it for one of three reasons:
- To leave a fixed amount of money to family, whenever they die.
- To cover a bill that will definitely arrive one day, such as funeral costs or an inheritance tax bill.
- For inheritance tax planning. If the policy is written in trust, the payout sits outside your estate, so it can be used to pay the tax bill without adding to it.
One important point if you have seen American content about whole life: UK whole of life policies are normally pure protection. They have no savings pot, no investment element and no cash in value. Every policy document we read says the same thing in plain terms: if you stop paying, your cover ends and you get nothing back. You cannot borrow against it and you cannot cash it in. It only pays out on a claim.
How it works, step by step
1. You choose the amount of cover. This is called the sum assured. It might be £20,000 for funeral costs, or several hundred thousand pounds to cover an inheritance tax bill.
2. You choose level or increasing cover. Level cover stays the same for life. Increasing cover goes up each year in line with inflation, usually measured by the Retail Prices Index. With increasing cover your premiums go up too, so the amount you pay is not fixed.
3. You choose single or joint cover. A joint policy covers two people. It can pay out when the first person dies, which suits family protection, or when the second person dies, which is the usual setup for inheritance tax planning, because the tax bill normally falls due on the second death.
4. You pay premiums. On most underwritten policies you pay for the whole of your life. This is the part people underestimate. If you take a policy out at 50 and live to 95, you will pay for 45 years. You need to be confident you can still afford it in retirement, because stopping means losing everything you have paid in.
5. The policy pays out early if you are terminally ill. Most underwritten policies pay the full sum if you are diagnosed with an illness that cannot be cured and is expected to lead to death within 12 months. The policy then ends.
6. On death, your family claims. They send the death certificate and policy details, the insurer checks the claim, and the lump sum is paid. If the policy was written in trust, it is paid to the trustees, which is usually faster and keeps it outside your estate for tax.
The rules that appear in almost every policy document
Reading across Legal & General, Aviva, Zurich, Vitality and Royal London, the same conditions come up again and again:
- No cash in value, ever. Stop paying and the cover ends with nothing back.
- Suicide exclusion in year one. No policy we read pays out if death in the first 12 months is by suicide or intentional self injury.
- Honest answers matter. Underwritten policies can be cancelled or a claim refused if you did not answer the health and lifestyle questions fully and honestly. Smoking status is a common problem area.
- Premiums are usually guaranteed. On a standard underwritten policy, your premium will not change unless you chose increasing cover or you change the policy yourself. Older reviewable policies are different: the insurer can raise premiums at set review points, and some people have seen large increases. Always check which type you are being sold.
- Waiver of premium is an optional extra. For an added cost, the insurer pays your premiums for you if illness or injury stops you working, usually after a waiting period of six months.
- You can increase cover after big life events. Most policies let you raise the sum assured without new medical questions after events like marriage, a child, a bigger mortgage or a higher inheritance tax bill, within set limits and age caps.
The two types sold in the UK
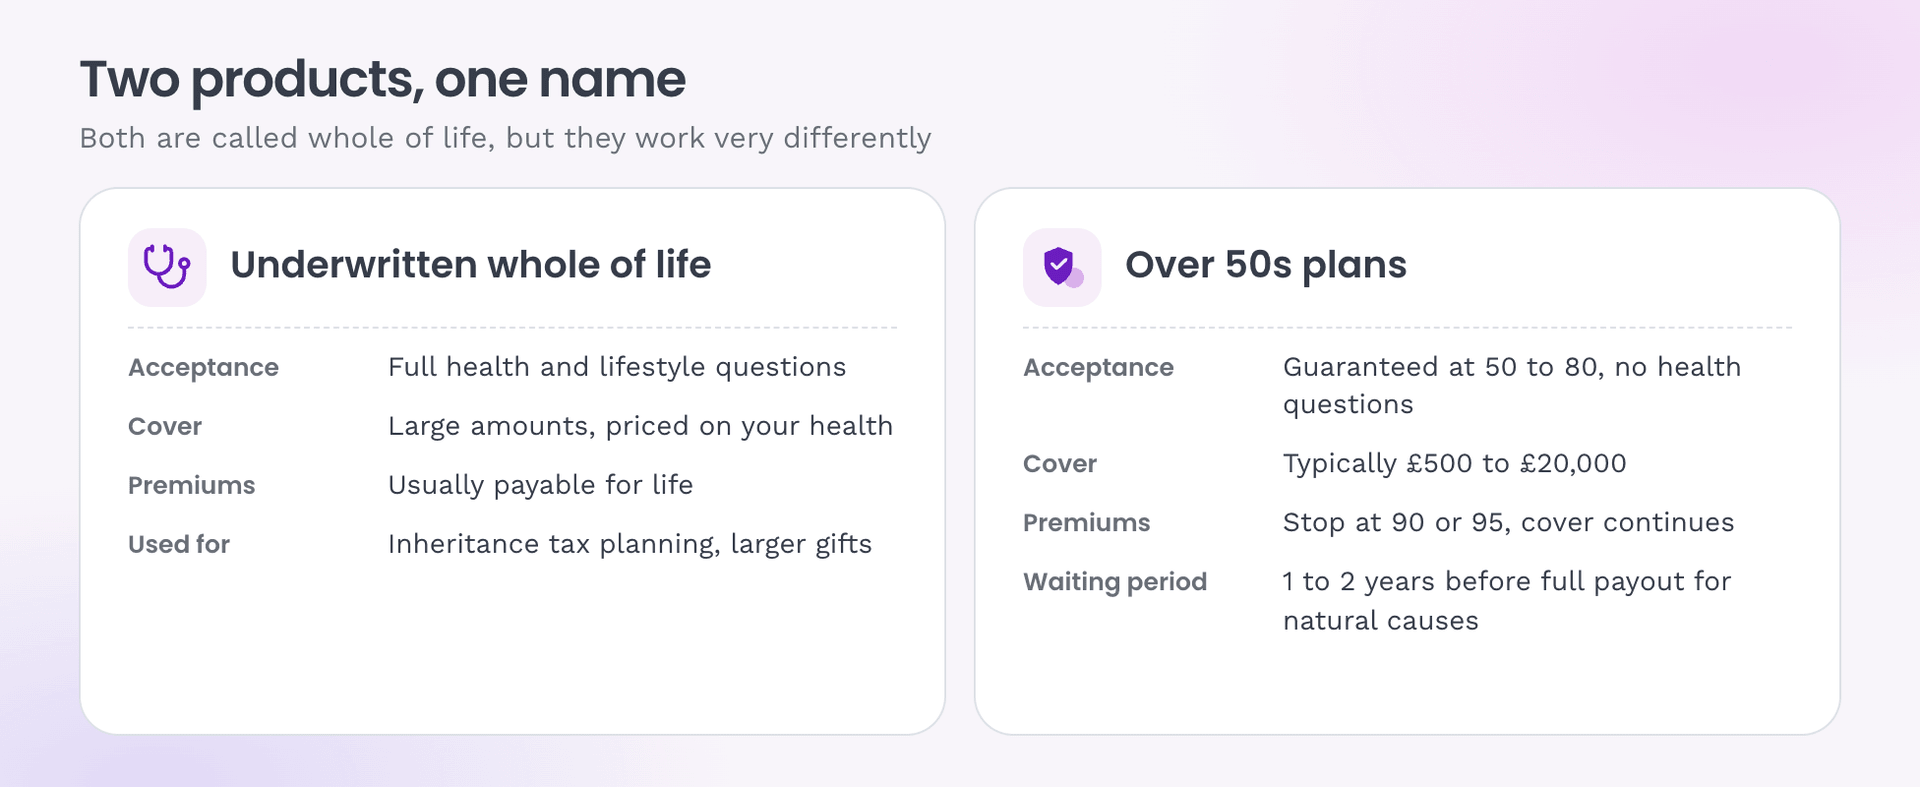
This is where most of the confusion comes from, because both are called whole of life but they are very different products.
Type 1: Underwritten whole of life
You answer full health and lifestyle questions, and sometimes have a medical. In return you can get large amounts of cover at a fair price for your actual health. This is the type used for inheritance tax planning and larger family gifts. It is mainly sold through financial advisers, not direct online.
Typical features from the documents: entry ages roughly 18 to 84 depending on the provider, joint life options, terminal illness cover included, and premiums payable for life.
Type 2: Over 50s plans
These are also whole of life policies, but sold in a completely different way. If you are aged 50 to 80 and live in the UK, you are guaranteed to be accepted. No health questions, no medical, no refusal.
That sounds generous, so here is the trade off:
- Cover amounts are small. Typically £500 to £20,000, aimed at funeral costs and small gifts.
- There is a waiting period. If you die from natural causes in the first year or two, your family does not get the full amount. Legal & General and British Seniors use a one year wait and refund premiums, or pay in full for accidental death. OneFamily and Shepherds Friendly use two years, and pay back 150 percent of premiums paid for a natural death in that period, with a higher payment for accidental death.
- Premiums stop at a set age, but cover does not. Depending on the provider you stop paying at 90 or 95, and stay covered for life.
- You can pay in more than your family gets back. If you live a long time, total premiums can pass the fixed payout. The payout also stays fixed, so inflation slowly reduces what it will actually buy. Every over 50s document says this openly.
In short: over 50s plans are simple and certain, and they make sense for people who cannot get underwritten cover or only need a small amount for funeral costs. If you are in good health, an underwritten policy will usually give you far more cover for the same monthly payment.
Who offers it in the UK?
Underwritten whole of life
- Legal & General: Whole of Life Protection Plan, ages 18 to 84, level or increasing cover, positioned for family protection and inheritance tax.
- Aviva: Whole of Life Insurance, single, joint first event or joint second event cover, with terminal illness cover.
- Zurich: Zurich Whole of Life, sold through advisers, with waiver of premium and options to increase cover after life events.
- Royal London: Pegasus Whole of Life Plan, sold through advisers. Royal London also now looks after the old Aegon whole of life policies, which transferred across in July 2024.
- Vitality: Whole of Life Cover inside its Personal Protection Plan, with its rewards programme and an optional extra called LifestyleCare, which can pay out early if you develop a serious later life illness such as dementia.
Some big names no longer sell new underwritten whole of life policies. LV= states on its own site that it no longer offers whole of life, Aegon left this market in 2023, and Canada Life has closed its CanProtect whole of life plan to new customers. Old lists online still show them, which is why the market can look bigger than it is.
Over 50s whole of life
- SunLife: the best known name in this market, with its Guaranteed Over 50 Plan, provided by Phoenix Life Limited.
- Legal & General: Over 50s Fixed Life Insurance, one year waiting period, premiums stop at your 90th birthday.
- Aviva: Over 50s Life Insurance, premiums from £5 to £100 a month, full cover after 12 months.
- OneFamily: Over 50s Life Cover, two year waiting period, funeral funding built in.
- Shepherds Friendly: Over 50s Life Insurance, two year waiting period, premiums stop at 90.
- British Seniors and Post Office: well known brands, but both are arranged by an intermediary and underwritten by a larger insurer behind the scenes. The name on the advert is not always the company that holds your policy, so it is worth checking who the underwriter is in the policy document.
Is it worth it?
Whole of life makes sense when the need truly has no end date: an inheritance tax bill, funeral costs, or a gift you want to guarantee. It makes less sense as general family protection during your working years, where term insurance will usually buy you far more cover for far less money.
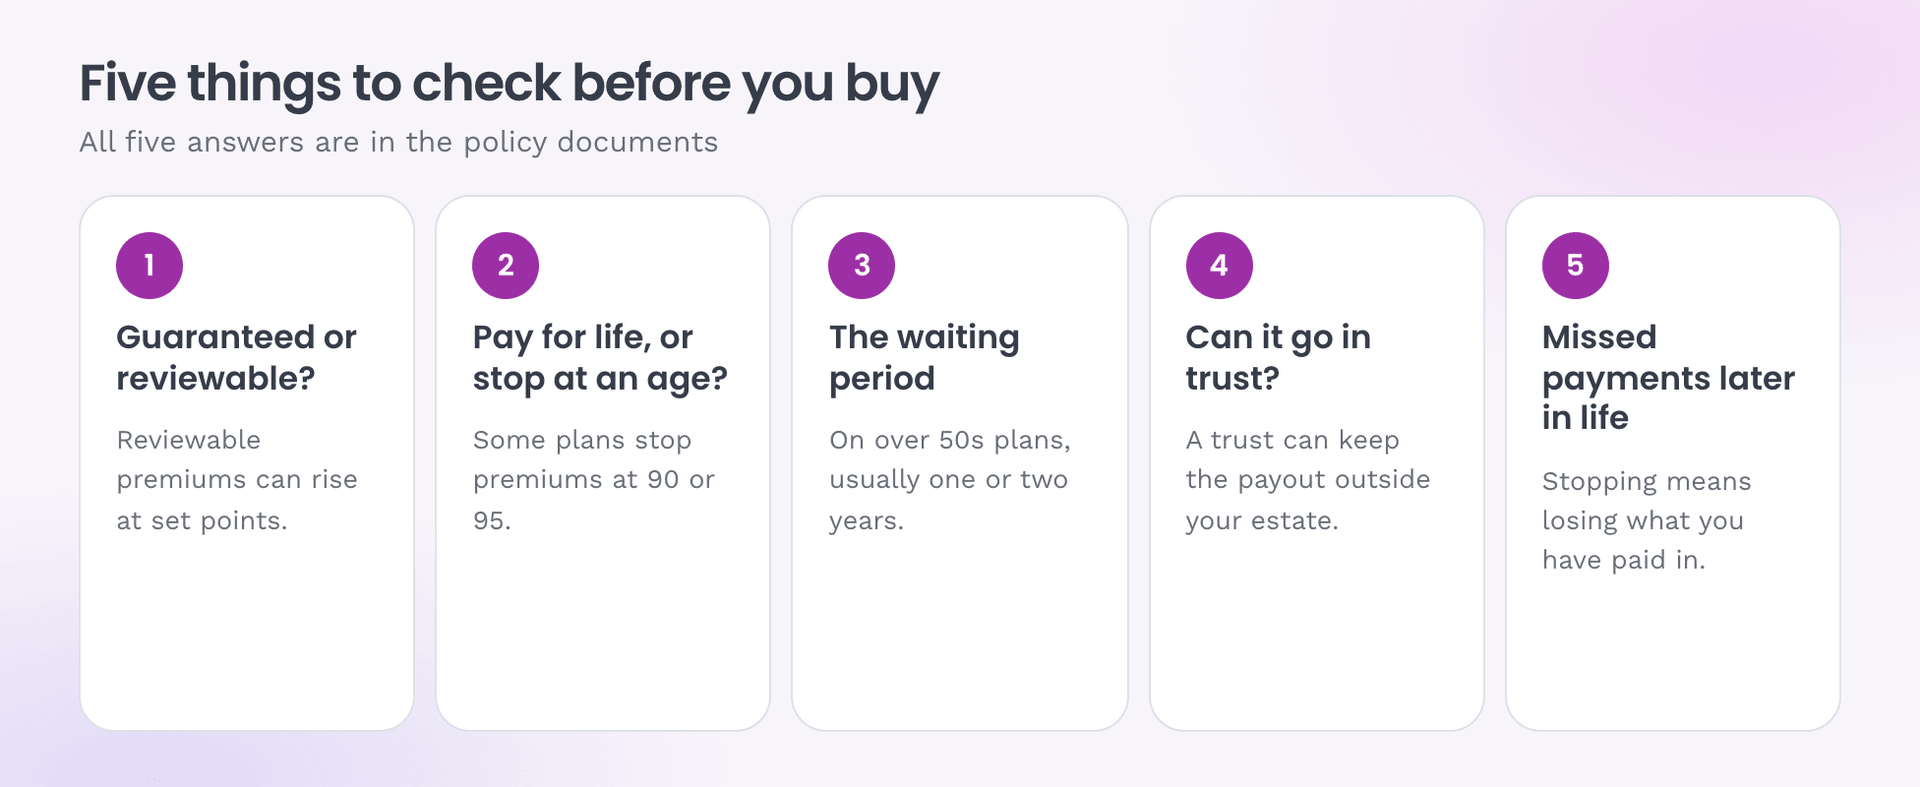
Before buying, check five things: whether premiums are guaranteed or reviewable, whether you must pay for life or premiums stop at a set age, the waiting period on an over 50s plan, whether the policy can be written in trust, and what happens if you miss payments in later life. All five answers are in the policy documents, and they matter more than the headline monthly price.
This is general information, not financial advice. Whole of life for inheritance tax planning in particular is worth taking regulated advice on, because the trust setup decides whether the tax saving works at all.
Whole of Life Insurance in the UK, Explained Simply
Frequently asked questions
Fact-checked and reviewed by Kiruba Shankar Eswaran or another licensed agent on our team. Read our editorial standards.
This guide is for general educational purposes and is not financial advice. Cover, eligibility and terms vary by insurer and by policy. Always read the policy documents for the full terms, limitations and exclusions before you buy.
Related resources
Life insurance cost UK 2026: what 6,557 real insurer quotes show
We collected 6,557 live quotes from UK life insurers in September 2026 and compared every one. Median prices by age, cover amount and policy length, how much smoking multiplies your premium, why bigger policies cost less per pound, and how mortgage protection compares with level cover.
What Is Term Life Insurance? UK Guide & Quotes (2026)
A complete UK guide to term life insurance: how it works, what it costs, the main policy types, underwriting, how it compares with whole of life, and the top UK providers.
Life Insurance for Young Adults
Life insurance for young adults doesn't have to be complicated or costly. This comprehensive guide covers why purchasing life insurance as a young adult locks in lower rates based on current health and how to pick the proper policy length and provider for your situation.
Turning Customer Curiosity Into Confidence: Theea's Coverage Calculator
Introducing Theea's Coverage Calculator: the intuitive insurance tool inspired by thousands of customer conversations that turns anxiety into tailored advice and confusion into confident choices.
Meet Your Newest Eleos Perks
We’re expanding our perks with two new additions designed to turn good intentions into healthy habits. Discover everything you can get for free with an Eleos policy.
Income protection for smokers
If you smoke, you may have a tough time getting income protection insurance, but it’s not impossible.