What is increasing life insurance?

Contents
It’s important to understand that increasing life insurance is usually available only with term life and not whole life policies. A whole life policy has no fixed end date, so it’s hard for insurers to calculate their potential liability. This is much easier to do with a finite term life policy. The cover provided by whole life policies can be boosted by other means, but this may involve buying additional cover rather than simply increasing what you already have.
The eventual payout of increasing term life insurance isn’t fixed when you take it out. Instead, policies are structured with annual increases in the amount of cover. This can be particularly effective in guarding against the erosive effects of inflation. Keeping pace with rising prices could be very important in ensuring your loved ones receive the financial support they’ll need in the future.
Inflation can be the unseen threat to standards of living. Its invisibility is reflected in the fact that pay freezes or below-inflation rises aren’t called pay cuts, even though your income doesn’t rise while prices do, so what you earn buys less. Exactly the same principle can apply to life insurance. The average UK inflation rate from 1994 to 2024 was 3.4%. Let’s say you took out a 30-year term life insurance policy with a payout of £100,000 in 1994. According to the Bank of England’s calculator, in 2024 it should have grown to £204,422.82 just to have the same buying power. An increasing term policy might have achieved that. A fixed term policy would not.
How it works
As with any life insurance policy, you work out how much you want to leave for your family and dependants should you pass away and arrange the level of cover accordingly. Your decision is likely to be influenced by how much you can afford to pay for your monthly premiums.
Increasing term life insurance often works by using indexation, which means the amount of each annual increase is linked to the rate of inflation. This is a very common method for calculating the growth of the cover, although some policies will allow you to review your cover annually, rather than relying solely on automatic adjustments. Another option is a fixed-rate percentage increase, which is typically set to mirror expected rises in the cost of living. It’s less flexible than indexation and annual reviews, but it does allow for consistency and certainty.
Do life insurance premiums increase every year?
For level term policies, premiums generally stay the same for the duration of the policy. For increasing insurance they increase every year. However, the premiums for decreasing life insurance don’t go down, as you might expect, but usually stay the same.
Inflation matching
As we’ve already discussed, one of the biggest benefits of increasing term life insurance is protection from inflation.
Rising expenses
Inflation isn’t the only pressure on your family’s finances. When you take out your policy you may have a clear idea of what they’ll need to pay for in the short term but not in the elong term. For example, as your children grow up, they may incur the costs of university and beyond that they may appreciate help with a deposit to buy a property, get married or start a family. Equally, your partner or spouse may eventually need to find the money for care services. An increasing term life policy can be an effective way of anticipating future needs.
Cost
The premiums can be lower than for a whole life insurance policy, since it’s easier for insurers to quantify the risk.
Simplicity
Usually, if you want to increase your cover, either under an existing policy or by taking out a new one, you’ll need to go through the underwriting process again so you can verify your eligibility and the insurer can assess the new level of risk. Because increasing cover is built into an increasing life policy there’s no need for this.
Cost
Because you’re paying for automatic increases the premiums will probably be higher than for level term cover and much higher than for decreasing insurance.
Annual increases
Unless your policy uses indexation to link the increasing premiums to inflation you could find that the percentage increase each year is higher than inflation. Your cover is likely to outpace inflation as a result, which may suit you. However, if you want to keep your premiums at the lowest level possible a fixed annual increase might not be the best option.
Capped payouts
Some increasing life insurance policies may place a cap on the amount by which you can increase your cover each year. In some cases, there may also be a limit on the final level of cover to which your policy can be increased.
Both term life and whole life policies can be arranged with level cover, which means the final payout is fixed at the start. Apart from offering increasing cover, term life policies can also do the opposite. This is known as decreasing life insurance, which is often used to meet the costs of declining obligations like mortgages and childcare. These are the key differences between increasing and decreasing cover.
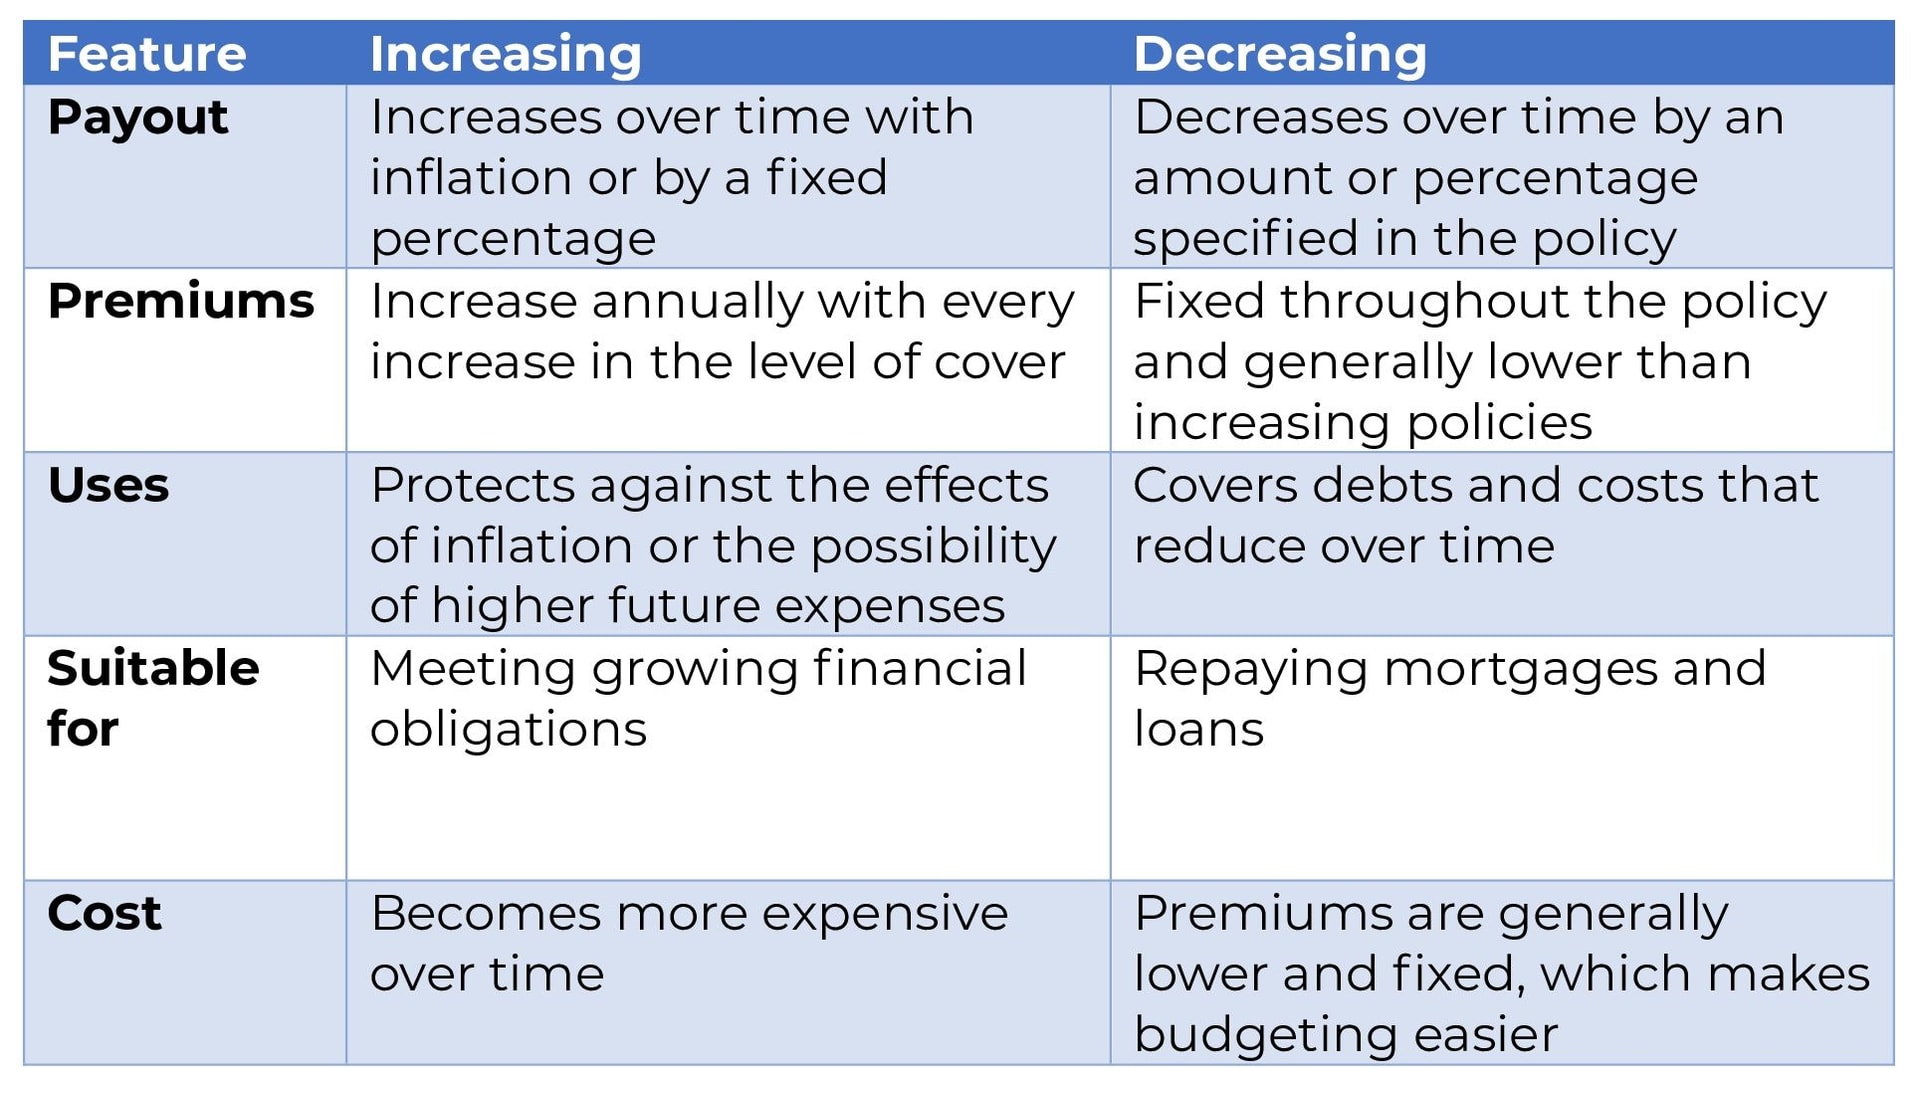
As with any life insurance policy, so many individual factors are involved that it’s impossible to give a simple answer to this question. Many insurers provide online quotes which you can use to compare level, increasing, and decreasing life insurance. When we tried this we found that increasing insurance is likely to cost more than level cover and could be around 80% more expensive than decreasing.
It’s often chosen by people who are not only planning for the long term, but anticipating rising rather than falling costs. Examples are:
- Partners who are getting married or entering civil partnerships
- Young families
- Someone who wants to make sure their partner will always be looked after
- People who want to assume responsibility for their children well into adult life
There are a number of other useful provisions that work together with increasing life insurance. It can be worth considering adding these when you take out your policy.
Terminal illness
This pays out while you’re alive, if you’re diagnosed with an illness that you’re not expected to survive for more than 12 months. Many life insurance policies already include this, but if it’s something you want you should make sure.
Critical illness
This pays out if you’re diagnosed with a serious but non-fatal condition which may be life-changing and with which you’ll probably have to live for a long time, if not forever.
Waiver of premium
If you add this to your life insurance it can cover your monthly premiums if you’re temporarily unable to earn an income because of illness or injury. This type of addition is often called a ‘rider’.
Income protection
This is a form of insurance that pays you a proportion of your income when illness or injury stops you from working. Even if you have employer’s sick pay or qualify for statutory sick pay it can top up what you receive and take over when these other forms of support end. You can claim as often as you need to for the duration of your policy.
What is increasing life insurance?
Frequently asked questions
Fact-checked and reviewed by Kiruba Shankar Eswaran or another licensed agent on our team. Read our editorial standards.
This guide is for general educational purposes and is not financial advice. Cover, eligibility and terms vary by insurer and by policy. Always read the policy documents for the full terms, limitations and exclusions before you buy.
Related resources
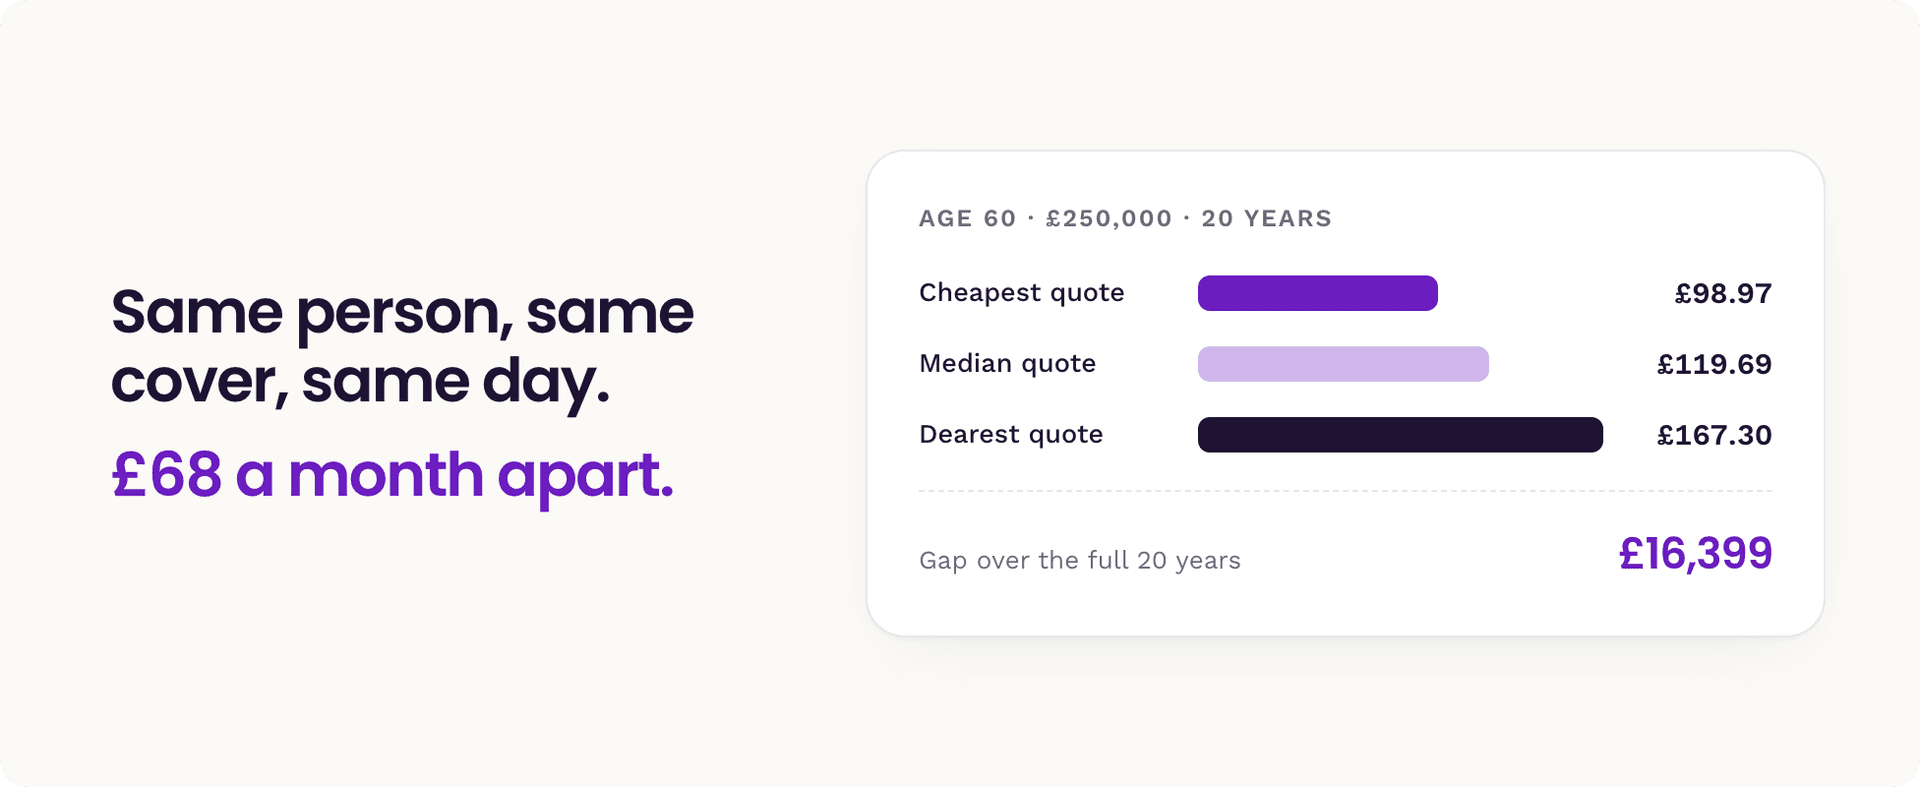
Life insurance cost UK 2026: what 6,557 real insurer quotes show
We collected 6,557 live quotes from UK life insurers in September 2026 and compared every one. Median prices by age, cover amount and policy length, how much smoking multiplies your premium, why bigger policies cost less per pound, and how mortgage protection compares with level cover.
What Is Term Life Insurance? UK Guide & Quotes (2026)
A complete UK guide to term life insurance: how it works, what it costs, the main policy types, underwriting, how it compares with whole of life, and the top UK providers.
6 Financial Resilience Tips for 2026
New Year, new money mindset. It’s time to break free from financial anxiety once and for all. Here are six simple tips to boost your financial resilience in 2026 and bring you peace of mind all year long!
Life Insurance for Young Adults
Life insurance for young adults doesn't have to be complicated or costly. This comprehensive guide covers why purchasing life insurance as a young adult locks in lower rates based on current health and how to pick the proper policy length and provider for your situation.
Turning Customer Curiosity Into Confidence: Theea's Coverage Calculator
Introducing Theea's Coverage Calculator: the intuitive insurance tool inspired by thousands of customer conversations that turns anxiety into tailored advice and confusion into confident choices.
Meet Your Newest Eleos Perks
We’re expanding our perks with two new additions designed to turn good intentions into healthy habits. Discover everything you can get for free with an Eleos policy.