Why put your life insurance policy in trust?
Contents
A trust is a legal arrangement that enables you to transfer your ownership of assets like money or property to another person or group of people. As the creator of the trust you are known as the ‘settlor’ and the people you appoint to run it are the ‘trustees’. They become responsible for the way the asset is managed and how its proceeds are distributed.
Trusts are used for lots of reasons and these are some of the most common ones:
- To protect family assets like property or businesses
- To look after the finances of children
- To take care of financial matters for someone who is unable to do it themselves
- To minimise the payment of tax when passing on money and property after death
Why put life insurance in trust?
A life insurance policy is a financial asset, just like a house or savings, which means it can be placed in trust like any other asset of value. Putting yours in trust brings several benefits, the most obvious being the way it lessens or removes the obligation on your beneficiaries to pay tax on the money they receive. It also gives you more control over how the money will be used and can speed up the payout.
Setting it up
You’ll need to find people to act as trustees. Their role is to keep an eye on the policy while the premiums are being paid, review it periodically and distribute the money from the eventual payout exactly as you’ve instructed. It’s a responsible position so anyone you approach must be aware of their duties. They may not need to have any legal knowledge but they should be organised and reliable. Many people choose family members or trusted friends but an alternative is to appoint a professional, such as a solicitor or financial adviser. If you do this, they will usually charge a fee for their services.
The trust deed
The trust is governed by a single document – the deed. This contains your instructions on how the trust will work, who the trustees are, what their duties will be and how the proceeds will be distributed if you pass away. The term ‘deed’ simply means it’s a document that must be in writing rather than just a verbal agreement.
Putting your life insurance policy in trust may sound like a complicated operation and it’s easy to be discouraged. It might be helpful to break it down into a simple point-by-point guide.
Advice: Get professional advice, because, for most of us, setting up a trust is unknown territory.
Trustees: Choose your trustees carefully, making sure they understand their responsibilities before they accept.
Trust deed: It’s advisable to create this with the help of a paralegal, solicitor or financial adviser.
Execution: The deed is executed by the policyholder and the trustees signing the document.
Assignment: This is the transfer of ownership of the policy from the policyholder to the trust, using a trust form.
Review: During the life of the policy the trustees should review it from time to time to make sure it is still sufficient to fulfil the purposes for which it was created.
Ownership of the policy
Ownership of the policy passes from you to the trust. That doesn’t mean the trustees own it – they are simply caretaking it. The transfer of ownership is a fairly straightforward process, using a trust form that your insurer can provide. Although you may still be paying the premiums, the policy is no longer yours, which means it doesn’t form part of your estate.
Payout
If you pass away, the payout from the policy can be distributed to the people you’ve listed as beneficiaries. Because it’s not part of your estate there won’t be any tax payable, which could save your beneficiaries as much as 40% of the full amount they expect to receive.
The other effect of the policy being in trust and not part of your estate is that the funds can be released quickly, rather than waiting for probate. This is the legal process of verifying that your will is valid, valuing all your assets, notifying any creditors to whom you owe money, calculating of any tax due and, finally, paying your beneficiaries. The process can take as long as 12 months, but if you put your policy in trust you can avoid all of this.
No financial solution is perfect, and putting a life insurance policy in trust has upsides and downsides.
Advantages of putting your life insurance policy in a trust
The most significant benefits of putting life insurance in trust are these.
Tax planning
40% inheritance tax is payable by beneficiaries who receive money from any estate that’s valued at more than £325,000. If your life insurance policy is part of your estate then its proceeds will be included. By placing your policy in trust you remove it from your estate and no inheritance tax is due on it.
Speed
Since your policy is outside your estate, the insurer can pay your beneficiaries without waiting for the probate process to be completed.
Control
You insure your life to provide financial help to your family after your death but generally they can do whatever they wish with the proceeds. By using a trust you can specify certain purposes you want the money to serve, such as paying school or university fees.
Protecting your beneficiaries
If your policy is in trust it can be protected from creditors so any debts you might leave behind don’t fall to your beneficiaries. You can also make it part of your trustees’ function to make sure the money isn’t frittered away by any of your beneficiaries whose attitude to money might be a little reckless.
Disadvantages of putting your life insurance policy in a trust
It’s important to bear in mind some of the drawbacks of using a trust for your life insurance policy.
Lack of control
A trust allows you to decide how the proceeds of a life policy are used, but it does mean that as soon as you place it in trust you no longer own it. You won’t be able to change its terms or take it back.
Cost and complexity
Setting up a trust will cost money because you’ll need professional advice and help. It also places long-term obligations on your trustees which in some circumstances may attract additional costs.
Choosing the trustees
This is just as important to get right as the trust deed itself. It’s crucial to appoint trustees who are trustworthy, financially responsible and fully prepared for all the duties they’re agreeing to undertake.
Limited access
A trust gives you control over how the proceeds of your policy are spent but the flipside of this is that your beneficiaries may be limited in how they can use the funds.
Disputes
Another consequence of the control you can exercise through the trust is the possibility of dispute between family members if they feel the terms are unfair. There’s nothing they can do about it, but it can cause problems, so you should make sure all the terms are clear and, as far as possible, explained.
There are considerable benefits of putting your life insurance policy in trust but you need to go into it with your eyes open. In theory it’s straightforward but in practice it can throw up unexpected complexities and problems at any time. There’s no substitute for taking sound professional advice from the outset so you’ll appreciate the implications, both positive and negative. If handled properly it can be a very efficient way of providing financial support for your loved ones when you’re no longer around to help them.
Why put your life insurance policy in trust?
Frequently asked questions
Fact-checked and reviewed by Kiruba Shankar Eswaran or another licensed agent on our team. Read our editorial standards.
This guide is for general educational purposes and is not financial advice. Cover, eligibility and terms vary by insurer and by policy. Always read the policy documents for the full terms, limitations and exclusions before you buy.
Related resources
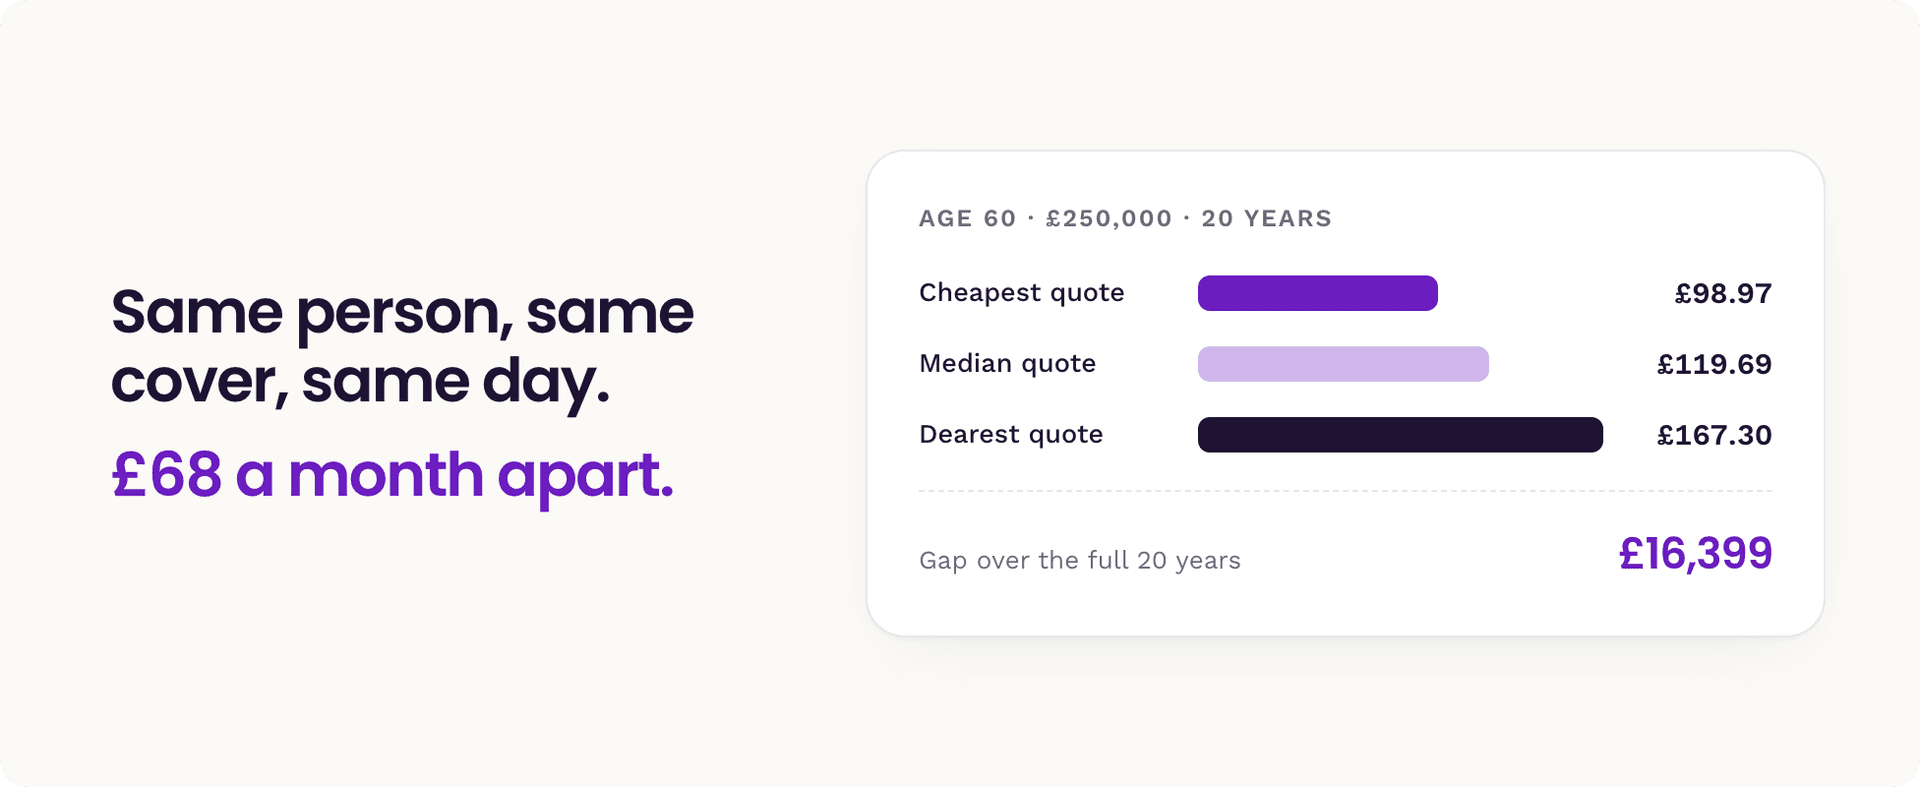
Life insurance cost UK 2026: what 6,557 real insurer quotes show
We collected 6,557 live quotes from UK life insurers in September 2026 and compared every one. Median prices by age, cover amount and policy length, how much smoking multiplies your premium, why bigger policies cost less per pound, and how mortgage protection compares with level cover.
What Is Term Life Insurance? UK Guide & Quotes (2026)
A complete UK guide to term life insurance: how it works, what it costs, the main policy types, underwriting, how it compares with whole of life, and the top UK providers.
6 Financial Resilience Tips for 2026
New Year, new money mindset. It’s time to break free from financial anxiety once and for all. Here are six simple tips to boost your financial resilience in 2026 and bring you peace of mind all year long!
Life Insurance for Young Adults
Life insurance for young adults doesn't have to be complicated or costly. This comprehensive guide covers why purchasing life insurance as a young adult locks in lower rates based on current health and how to pick the proper policy length and provider for your situation.
Turning Customer Curiosity Into Confidence: Theea's Coverage Calculator
Introducing Theea's Coverage Calculator: the intuitive insurance tool inspired by thousands of customer conversations that turns anxiety into tailored advice and confusion into confident choices.
Meet Your Newest Eleos Perks
We’re expanding our perks with two new additions designed to turn good intentions into healthy habits. Discover everything you can get for free with an Eleos policy.