insurance
Life insurance cost UK 2026: what 6,557 real insurer quotes show
Kiruba Shankar EswaranFounder + CEO
Published 24 September 2026Last updated 24 September 202616 min read
Life insurance cost UK 2026: what 6,557 real insurer quotes show
Fact-checked and reviewed by Kiruba Shankar Eswaran or another licensed agent on our team. Read our editorial standards.
This guide is for general educational purposes and is not financial advice. Cover, eligibility and terms vary by insurer and by policy. Always read the policy documents for the full terms, limitations and exclusions before you buy.
Based on 6,557 live quotes for level term and mortgage protection cover, collected September 2026
Key facts from this study
Most articles about life insurance costs give you one number, or a vague "from £5 a month" that turns out to apply to almost nobody. This one is different. We asked UK life insurers for real prices, over and over, changing one thing at a time, and we wrote down every answer.
Here is exactly what we did. We used a whole of market platform that financial advisers use to compare life insurance. For each combination of age, cover amount, policy length and smoking status, we asked every insurer on the panel for a price, then recorded what each one came back with. We did it twice, once for level cover and once for mortgage protection.
These are not estimates and they are not marketing numbers. They are the actual prices insurers were offering on that day.
One thing to be clear about up front: these are quotes, not policies that people bought. That difference matters, and we come back to it near the end.
Insurance pricing is not one number, it is a spread. For the same person asking for the same cover on the same day, the cheapest insurer and the most expensive can be very far apart. A single average would hide the thing you most need to know.
So we give you four ways of looking at each price.
The median. Line up every quote from cheapest to dearest and take the one in the middle. Half the insurers charge less, half charge more. This is the most useful single number, because one very expensive outlier cannot drag it around.
The middle half. Chop off the cheapest quarter of quotes and the dearest quarter. What is left is the middle half. If you shop around a bit without being obsessive, this is the territory you will land in.
The 95% confidence range. We sampled the insurers on one adviser panel, not every insurer that exists. This range is our honest answer to the question "if we could ask the whole market, where would the true average sit?" We are 95% confident the real average falls inside it. A wide range means insurers disagreed with each other a lot.
Cheapest to dearest. The full spread, outliers included. This is what tells you whether shopping around is worth your time.
Every quote here is for the same imaginary person, because that is the only way to compare fairly. He is male, 5 foot 10, 12 stone 4, which is a BMI of 24.6 and sits in the healthy range. He is in good health with nothing to declare, and we did not enter an occupation.
Gender does not change the price in the UK. Since a European court ruling took effect in 2012, UK insurers cannot charge men and women different prices for life insurance. These prices apply to women too.
Build does change the price. Height and weight are compulsory questions and they feed straight into the quote. We held them fixed so everything else could be compared cleanly.
Occupation was left blank. A few products on the panel take occupation into account, so their prices could move once a job is entered.
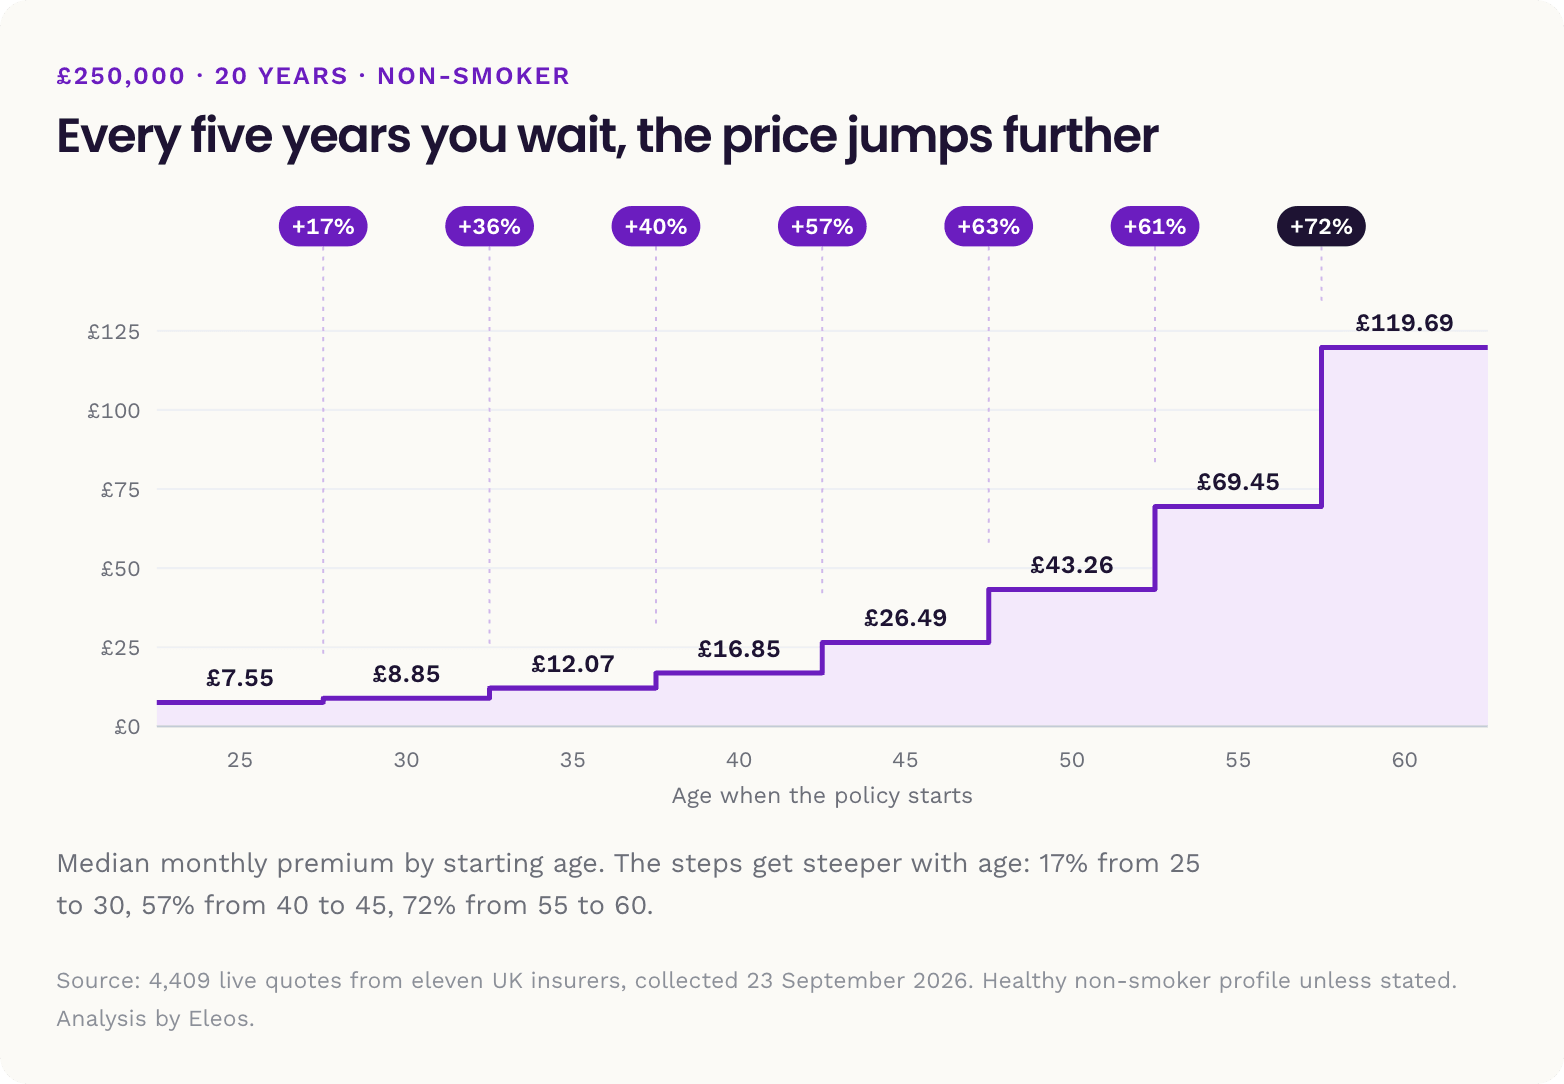
Age is the single biggest driver of price, and it does not rise in a straight line. It bends upward sharply after about 45.
Below are the full median tables for every combination we tested. Level term means the payout stays the same for the whole policy, and so does the price.
| Age | £50k | £100k | £150k | £200k | £250k | £500k | £750k |
|---|---|---|---|---|---|---|---|
| 25 | £5.01 | £5.22 | £5.29 | £6.20 | £6.82 | £10.97 | £15.27 |
| 30 | £5.01 | £5.25 | £6.18 | £7.38 | £8.31 | £12.94 | £18.26 |
| 35 | £5.26 | £5.71 | £7.82 | £9.28 | £10.52 | £16.43 | £23.69 |
| 40 | £5.40 | £8.10 | £9.97 | £12.12 | £13.71 | £21.79 | £32.15 |
| 45 | £6.64 | £10.66 | £13.47 | £17.12 | £20.14 | £33.41 | £50.43 |
| 50 | £9.27 | £15.71 | £21.61 | £26.91 | £32.64 | £55.31 | £85.45 |
| 55 | £13.25 | £23.70 | £31.82 | £41.46 | £49.56 | £91.69 | £132.04 |
| 60 | £20.84 | £38.48 | £52.02 | £68.14 | £79.00 | £147.77 | £214.52 |
| Age | £50k | £100k | £150k | £200k | £250k | £500k | £750k |
|---|---|---|---|---|---|---|---|
| 25 | £5.31 | £5.84 | £7.55 | £8.68 | £9.69 | £15.49 | £21.36 |
| 30 | £5.30 | £7.37 | £9.16 | £10.75 | £12.12 | £20.29 | £28.59 |
| 35 | £6.57 | £9.48 | £12.12 | £14.91 | £17.09 | £28.39 | £42.28 |
| 40 | £8.70 | £13.25 | £17.23 | £21.68 | £24.64 | £45.43 | £64.87 |
| 45 | £12.50 | £20.70 | £27.80 | £34.60 | £42.52 | £75.73 | £112.49 |
| 50 | £19.56 | £33.87 | £48.98 | £62.40 | £71.84 | £132.15 | £198.15 |
| 55 | £32.83 | £59.96 | £88.02 | £108.38 | £129.01 | £228.15 | £343.00 |
| 60 | £53.82 | £108.34 | £149.27 | £188.41 | £216.93 | £392.99 | £579.46 |
| Age | £50k | £100k | £150k | £200k | £250k | £500k | £750k |
|---|---|---|---|---|---|---|---|
| 25 | £4.88 | £5.01 | £5.30 | £6.71 | £7.55 | £11.71 | £16.57 |
| 30 | £5.01 | £5.16 | £6.78 | £8.30 | £8.85 | £14.42 | £20.70 |
| 35 | £5.01 | £6.36 | £8.57 | £10.66 | £12.07 | £19.46 | £28.66 |
| 40 | £5.31 | £9.10 | £11.54 | £14.48 | £16.85 | £29.42 | £44.06 |
| 45 | £8.27 | £13.29 | £17.48 | £22.16 | £26.49 | £45.74 | £69.80 |
| 50 | £11.08 | £19.84 | £28.12 | £35.91 | £43.26 | £76.99 | £115.25 |
| 55 | £18.03 | £32.38 | £46.04 | £59.92 | £69.45 | £123.82 | £185.73 |
| 60 | £29.99 | £53.94 | £78.02 | £97.50 | £119.69 | £218.42 | £315.08 |
| Age | £50k | £100k | £150k | £200k | £250k | £500k | £750k |
|---|---|---|---|---|---|---|---|
| 25 | £5.01 | £6.02 | £7.67 | £8.98 | £10.23 | £16.69 | £24.02 |
| 30 | £5.15 | £7.79 | £10.14 | £12.25 | £14.15 | £23.66 | £34.80 |
| 35 | £6.92 | £10.79 | £14.62 | £18.73 | £20.91 | £37.39 | £54.77 |
| 40 | £9.99 | £16.91 | £23.47 | £29.57 | £34.09 | £60.46 | £90.69 |
| 45 | £16.05 | £29.13 | £40.07 | £50.38 | £62.00 | £104.80 | £156.35 |
| 50 | £25.80 | £47.16 | £69.66 | £92.31 | £104.62 | £189.00 | £285.96 |
| 55 | £44.06 | £83.55 | £123.79 | £159.33 | £179.71 | £326.28 | £483.36 |
| 60 | £78.13 | £147.93 | £207.10 | £269.48 | £315.83 | £576.84 | £819.07 |
| Age | £50k | £100k | £150k | £200k | £250k | £500k | £750k |
|---|---|---|---|---|---|---|---|
| 25 | £4.92 | £5.01 | £5.47 | £7.20 | £8.32 | £12.41 | £18.06 |
| 30 | £5.07 | £5.32 | £7.41 | £8.80 | £9.82 | £16.00 | £23.52 |
| 35 | £5.04 | £7.03 | £9.54 | £11.81 | £13.54 | £22.71 | £32.48 |
| 40 | £6.13 | £10.21 | £13.08 | £16.56 | £19.69 | £32.30 | £49.66 |
| 45 | £9.05 | £14.82 | £19.80 | £25.16 | £29.95 | £52.80 | £80.24 |
| 50 | £13.47 | £23.45 | £32.20 | £41.25 | £49.07 | £88.31 | £132.78 |
| 55 | £21.47 | £38.83 | £55.07 | £73.42 | £83.55 | £155.38 | £226.44 |
| 60 | £35.49 | £66.37 | £95.01 | £123.08 | £149.79 | £271.65 | £393.50 |
| Age | £50k | £100k | £150k | £200k | £250k | £500k | £750k |
|---|---|---|---|---|---|---|---|
| 25 | £5.49 | £6.46 | £7.94 | £9.62 | £11.26 | £18.46 | £26.73 |
| 30 | £5.50 | £8.52 | £11.23 | £13.77 | £16.23 | £27.31 | £39.59 |
| 35 | £7.61 | £12.36 | £16.89 | £21.37 | £24.57 | £43.27 | £64.68 |
| 40 | £12.05 | £20.24 | £27.63 | £34.80 | £40.25 | £71.67 | n/a |
| 45 | £18.50 | £34.05 | £47.00 | £59.66 | £72.19 | £122.73 | n/a |
| 50 | £31.36 | £56.80 | £81.31 | £108.84 | £121.32 | £219.88 | n/a |
| 55 | £52.29 | £99.56 | £141.89 | £182.77 | £214.40 | £399.47 | n/a |
| 60 | £93.03 | £172.78 | £247.61 | £304.46 | £367.09 | £666.22 | n/a |
This is the finding that costs people the most money, and almost nobody checks it.
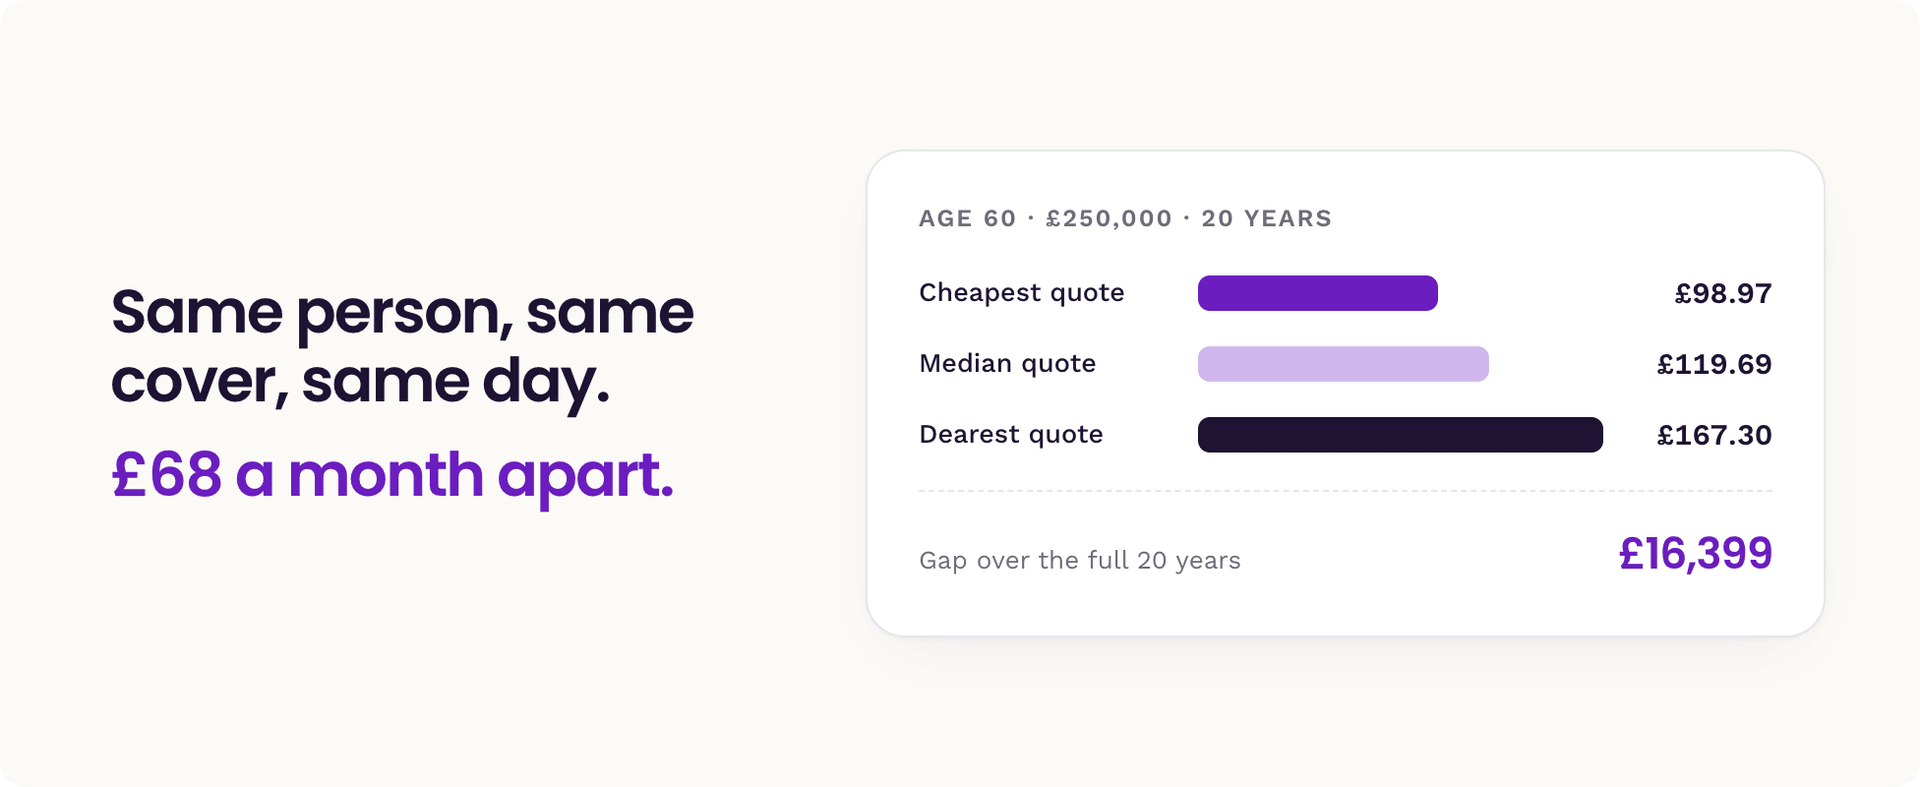
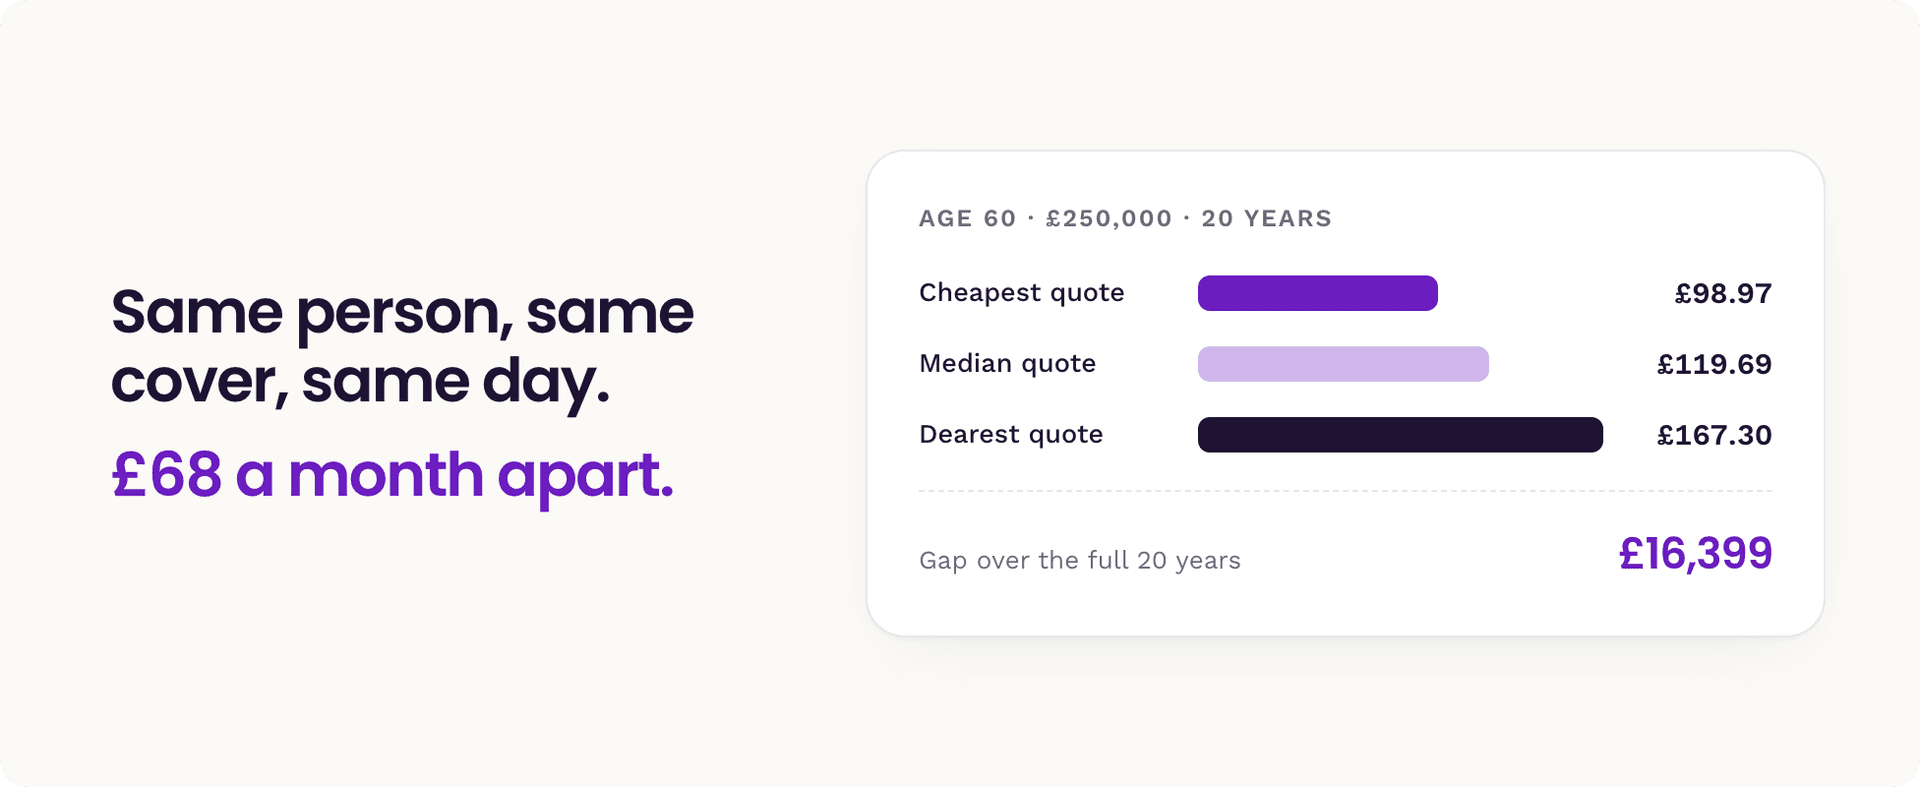
At 60, wanting £250,000 over 20 years, the cheapest insurer quoted £98.97 a month and the dearest quoted £167.30. Same person, same cover, same day. Over the full policy that gap is £16,399.
The gap grows with age, and it grows faster than the price itself.
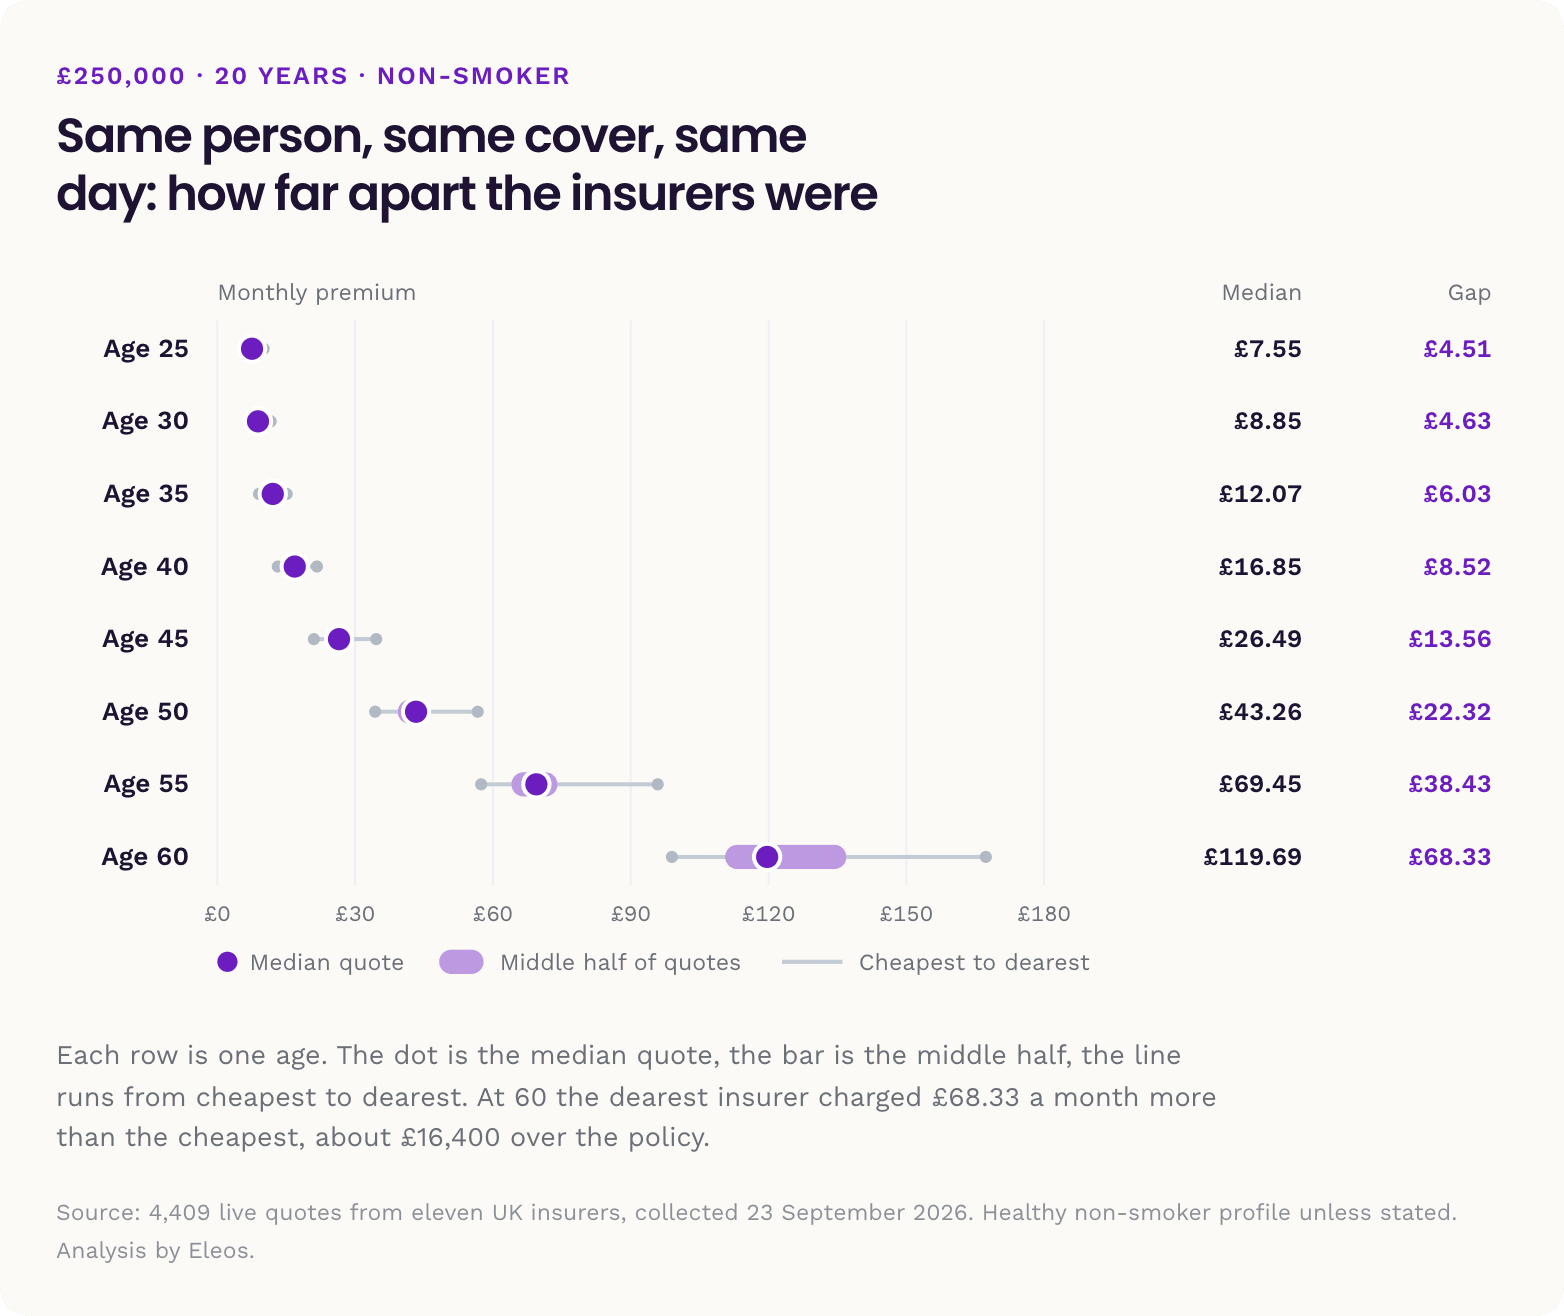
Each row is one age. The dot is the median, the thick bar is the middle half of quotes, and the thin line runs from cheapest to dearest.
Notice that at 25 the whole market fits inside about £4.50. By 60 it spans nearly £70. Shopping around is barely worth the effort in your twenties. In your fifties and sixties it is worth more than almost anything else you can do.
Here are the full bands for two common cover amounts.
| Age | Quotes | Median | Middle half | 95% confidence range | Cheapest to dearest |
|---|---|---|---|---|---|
| 25 | 6 | £5.22 | £4.98 to £6.29 | £4.80 to £6.21 | £4.91 to £6.45 |
| 30 | 8 | £5.25 | £5.00 to £6.47 | £4.70 to £6.40 | £4.13 to £7.27 |
| 35 | 10 | £5.71 | £5.09 to £7.04 | £5.22 to £7.07 | £5.01 to £8.73 |
| 40 | 12 | £8.10 | £6.69 to £8.79 | £6.83 to £8.88 | £5.29 to £10.93 |
| 45 | 12 | £10.66 | £9.68 to £11.41 | £9.46 to £11.91 | £7.50 to £14.94 |
| 50 | 12 | £15.71 | £14.38 to £16.47 | £14.31 to £17.56 | £12.49 to £22.47 |
| 55 | 12 | £23.70 | £21.82 to £25.38 | £21.67 to £26.96 | £19.31 to £35.18 |
| 60 | 11 | £38.48 | £34.79 to £40.53 | £34.65 to £43.98 | £30.72 to £55.75 |
| Age | Quotes | Median | Middle half | 95% confidence range | Cheapest to dearest |
|---|---|---|---|---|---|
| 25 | 10 | £6.82 | £6.18 to £8.11 | £6.17 to £8.35 | £5.34 to £10.22 |
| 30 | 12 | £8.31 | £7.43 to £8.79 | £7.54 to £9.42 | £6.20 to £11.30 |
| 35 | 12 | £10.52 | £9.29 to £10.80 | £9.37 to £11.77 | £7.53 to £14.48 |
| 40 | 12 | £13.71 | £12.64 to £14.39 | £12.44 to £15.65 | £10.31 to £19.57 |
| 45 | 12 | £20.14 | £18.78 to £20.93 | £18.58 to £22.75 | £15.67 to £28.03 |
| 50 | 12 | £32.64 | £28.51 to £34.56 | £29.56 to £35.94 | £26.78 to £44.32 |
| 55 | 11 | £49.56 | £44.24 to £52.85 | £45.41 to £57.34 | £42.62 to £72.69 |
| 60 | 11 | £79.00 | £77.48 to £84.91 | £75.60 to £94.17 | £71.32 to £118.21 |
| Age | Quotes | Median | Middle half | 95% confidence range | Cheapest to dearest |
|---|---|---|---|---|---|
| 25 | 9 | £5.84 | £5.01 to £7.29 | £5.08 to £7.21 | £4.73 to £8.53 |
| 30 | 12 | £7.37 | £6.14 to £8.85 | £6.33 to £8.38 | £5.01 to £9.96 |
| 35 | 12 | £9.48 | £8.20 to £11.05 | £8.22 to £10.92 | £6.16 to £13.63 |
| 40 | 12 | £13.25 | £12.17 to £15.54 | £11.78 to £15.87 | £9.04 to £21.36 |
| 45 | 12 | £20.70 | £19.23 to £24.04 | £18.81 to £24.23 | £15.48 to £31.81 |
| 50 | 12 | £33.87 | £32.30 to £41.05 | £32.48 to £40.88 | £27.87 to £50.88 |
| 55 | 12 | £59.96 | £56.27 to £67.58 | £56.09 to £69.83 | £48.06 to £86.59 |
| 60 | 11 | £108.34 | £97.44 to £112.63 | £95.68 to £122.67 | £84.56 to £152.04 |
| Age | Quotes | Median | Middle half | 95% confidence range | Cheapest to dearest |
|---|---|---|---|---|---|
| 25 | 12 | £9.69 | £8.13 to £11.32 | £8.51 to £11.48 | £6.91 to £14.44 |
| 30 | 12 | £12.12 | £11.06 to £13.82 | £11.18 to £14.19 | £9.45 to £17.35 |
| 35 | 12 | £17.09 | £15.61 to £17.80 | £15.62 to £19.68 | £13.21 to £24.78 |
| 40 | 12 | £24.64 | £24.22 to £28.75 | £23.17 to £30.79 | £19.95 to £42.19 |
| 45 | 12 | £42.52 | £39.40 to £46.99 | £38.90 to £49.59 | £33.42 to £65.01 |
| 50 | 12 | £71.84 | £68.44 to £81.53 | £68.04 to £83.85 | £60.51 to £106.50 |
| 55 | 11 | £129.01 | £117.51 to £151.03 | £117.51 to £149.71 | £101.96 to £183.14 |
| 60 | 11 | £216.93 | £202.80 to £253.30 | £202.22 to £259.18 | £173.09 to £329.41 |
| Age | Quotes | Median | Middle half | 95% confidence range | Cheapest to dearest |
|---|---|---|---|---|---|
| 25 | 6 | £5.01 | £4.28 to £5.93 | £4.08 to £5.98 | £3.67 to £6.16 |
| 30 | 9 | £5.16 | £5.01 to £6.38 | £4.97 to £6.16 | £4.85 to £6.82 |
| 35 | 10 | £6.36 | £5.76 to £7.71 | £5.83 to £7.49 | £5.01 to £8.58 |
| 40 | 12 | £9.10 | £8.35 to £9.96 | £8.32 to £9.98 | £6.59 to £11.57 |
| 45 | 12 | £13.29 | £12.33 to £13.92 | £12.25 to £14.35 | £9.95 to £16.54 |
| 50 | 12 | £19.84 | £19.31 to £20.96 | £18.64 to £22.46 | £15.55 to £27.60 |
| 55 | 11 | £32.38 | £30.55 to £33.90 | £29.72 to £37.20 | £24.89 to £46.06 |
| 60 | 11 | £53.94 | £50.70 to £62.93 | £49.95 to £63.49 | £41.43 to £75.89 |
| Age | Quotes | Median | Middle half | 95% confidence range | Cheapest to dearest |
|---|---|---|---|---|---|
| 25 | 10 | £7.55 | £6.63 to £8.21 | £6.61 to £8.48 | £5.57 to £10.08 |
| 30 | 12 | £8.85 | £8.30 to £9.47 | £8.27 to £9.93 | £6.98 to £11.61 |
| 35 | 12 | £12.07 | £10.98 to £12.49 | £10.98 to £13.12 | £9.07 to £15.10 |
| 40 | 12 | £16.85 | £15.60 to £17.83 | £15.63 to £18.55 | £13.16 to £21.68 |
| 45 | 12 | £26.49 | £24.53 to £27.09 | £24.39 to £28.89 | £21.02 to £34.58 |
| 50 | 12 | £43.26 | £39.28 to £45.74 | £39.61 to £47.36 | £34.36 to £56.68 |
| 55 | 11 | £69.45 | £64.03 to £74.05 | £63.65 to £78.95 | £57.43 to £95.86 |
| 60 | 11 | £119.69 | £110.56 to £136.94 | £111.68 to £140.20 | £98.97 to £167.30 |
| Age | Quotes | Median | Middle half | 95% confidence range | Cheapest to dearest |
|---|---|---|---|---|---|
| 25 | 11 | £6.02 | £5.31 to £7.98 | £5.46 to £7.19 | £5.01 to £8.42 |
| 30 | 12 | £7.79 | £7.26 to £9.61 | £7.08 to £9.11 | £5.17 to £10.23 |
| 35 | 12 | £10.79 | £10.47 to £12.54 | £10.01 to £12.59 | £7.59 to £15.05 |
| 40 | 12 | £16.91 | £16.38 to £19.40 | £15.99 to £19.83 | £13.61 to £25.51 |
| 45 | 12 | £29.13 | £27.33 to £31.87 | £26.72 to £32.49 | £21.68 to £40.37 |
| 50 | 12 | £47.16 | £46.30 to £55.66 | £45.02 to £55.36 | £37.37 to £68.29 |
| 55 | 11 | £83.55 | £77.75 to £95.76 | £77.50 to £97.57 | £66.17 to £117.14 |
| 60 | 11 | £147.93 | £125.64 to £157.15 | £131.29 to £164.83 | £114.54 to £196.24 |
| Age | Quotes | Median | Middle half | 95% confidence range | Cheapest to dearest |
|---|---|---|---|---|---|
| 25 | 12 | £10.23 | £9.21 to £12.16 | £9.42 to £12.13 | £7.61 to £15.18 |
| 30 | 12 | £14.15 | £13.27 to £15.23 | £13.09 to £16.13 | £10.52 to £19.39 |
| 35 | 12 | £20.91 | £19.79 to £23.53 | £19.69 to £24.29 | £15.90 to £29.02 |
| 40 | 12 | £34.09 | £32.76 to £38.95 | £32.18 to £40.41 | £27.78 to £52.41 |
| 45 | 12 | £62.00 | £55.29 to £68.50 | £56.32 to £68.91 | £48.01 to £85.15 |
| 50 | 12 | £104.62 | £95.16 to £122.39 | £97.98 to £120.22 | £88.52 to £146.71 |
| 55 | 11 | £179.71 | £167.21 to £214.52 | £169.89 to £214.52 | £152.99 to £253.91 |
| 60 | 11 | £315.83 | £303.75 to £355.17 | £296.34 to £356.78 | £269.78 to £426.45 |
| Age | Quotes | Median | Middle half | 95% confidence range | Cheapest to dearest |
|---|---|---|---|---|---|
| 25 | 8 | £5.01 | £4.62 to £5.75 | £4.56 to £5.77 | £4.15 to £6.43 |
| 30 | 10 | £5.32 | £5.11 to £6.50 | £5.15 to £6.37 | £5.01 to £7.25 |
| 35 | 10 | £7.03 | £6.23 to £8.30 | £6.23 to £8.16 | £5.01 to £9.32 |
| 40 | 12 | £10.21 | £9.41 to £11.04 | £9.36 to £11.32 | £7.49 to £13.52 |
| 45 | 12 | £14.82 | £14.01 to £16.00 | £13.75 to £16.64 | £11.33 to £20.28 |
| 50 | 11 | £23.45 | £22.08 to £25.14 | £21.47 to £26.78 | £17.58 to £32.07 |
| 55 | 11 | £38.83 | £35.77 to £44.42 | £35.43 to £45.21 | £28.41 to £53.37 |
| 60 | 11 | £66.37 | £60.17 to £85.84 | £61.27 to £81.37 | £47.34 to £93.17 |
| Age | Quotes | Median | Middle half | 95% confidence range | Cheapest to dearest |
|---|---|---|---|---|---|
| 25 | 9 | £8.32 | £7.54 to £9.01 | £7.48 to £9.30 | £6.84 to £10.70 |
| 30 | 10 | £9.82 | £8.96 to £10.74 | £9.06 to £10.99 | £8.68 to £12.61 |
| 35 | 11 | £13.54 | £12.06 to £14.03 | £12.05 to £14.69 | £10.00 to £16.56 |
| 40 | 10 | £19.69 | £18.18 to £21.18 | £18.34 to £21.96 | £17.58 to £25.27 |
| 45 | 10 | £29.95 | £28.79 to £32.62 | £28.38 to £34.33 | £27.59 to £40.04 |
| 50 | 9 | £49.07 | £47.17 to £56.89 | £45.99 to £58.14 | £45.86 to £67.47 |
| 55 | 9 | £83.55 | £82.50 to £101.96 | £80.54 to £101.28 | £79.59 to £115.11 |
| 60 | 9 | £149.79 | £139.91 to £191.34 | £142.36 to £185.71 | £135.77 to £208.81 |
| Age | Quotes | Median | Middle half | 95% confidence range | Cheapest to dearest |
|---|---|---|---|---|---|
| 25 | 12 | £6.46 | £5.90 to £8.59 | £5.97 to £7.91 | £5.01 to £9.35 |
| 30 | 12 | £8.52 | £8.21 to £10.93 | £7.87 to £10.46 | £5.79 to £12.88 |
| 35 | 12 | £12.36 | £12.04 to £13.95 | £11.42 to £14.77 | £8.80 to £19.07 |
| 40 | 12 | £20.24 | £19.30 to £21.71 | £18.66 to £23.15 | £15.14 to £29.45 |
| 45 | 12 | £34.05 | £32.12 to £39.32 | £31.65 to £38.85 | £25.41 to £48.01 |
| 50 | 11 | £56.80 | £53.69 to £66.24 | £53.09 to £66.41 | £44.05 to £80.44 |
| 55 | 11 | £99.56 | £88.43 to £112.07 | £90.12 to £113.81 | £74.87 to £133.61 |
| 60 | 11 | £172.78 | £144.11 to £192.51 | £152.78 to £192.33 | £127.76 to £220.21 |
| Age | Quotes | Median | Middle half | 95% confidence range | Cheapest to dearest |
|---|---|---|---|---|---|
| 25 | 12 | £11.26 | £10.17 to £13.56 | £10.34 to £13.72 | £8.28 to £16.93 |
| 30 | 12 | £16.23 | £14.98 to £16.62 | £14.54 to £19.01 | £11.81 to £24.66 |
| 35 | 12 | £24.57 | £23.45 to £26.14 | £22.68 to £29.24 | £18.54 to £38.30 |
| 40 | 12 | £40.25 | £38.90 to £44.02 | £38.07 to £47.58 | £33.08 to £61.25 |
| 45 | 12 | £72.19 | £66.25 to £76.51 | £66.13 to £80.80 | £57.22 to £102.16 |
| 50 | 11 | £121.32 | £113.06 to £135.09 | £112.47 to £140.11 | £96.10 to £173.50 |
| 55 | 11 | £214.40 | £194.26 to £243.77 | £198.19 to £243.10 | £168.88 to £290.34 |
| 60 | 11 | £367.09 | £342.58 to £402.70 | £335.54 to £406.08 | £298.41 to £480.26 |
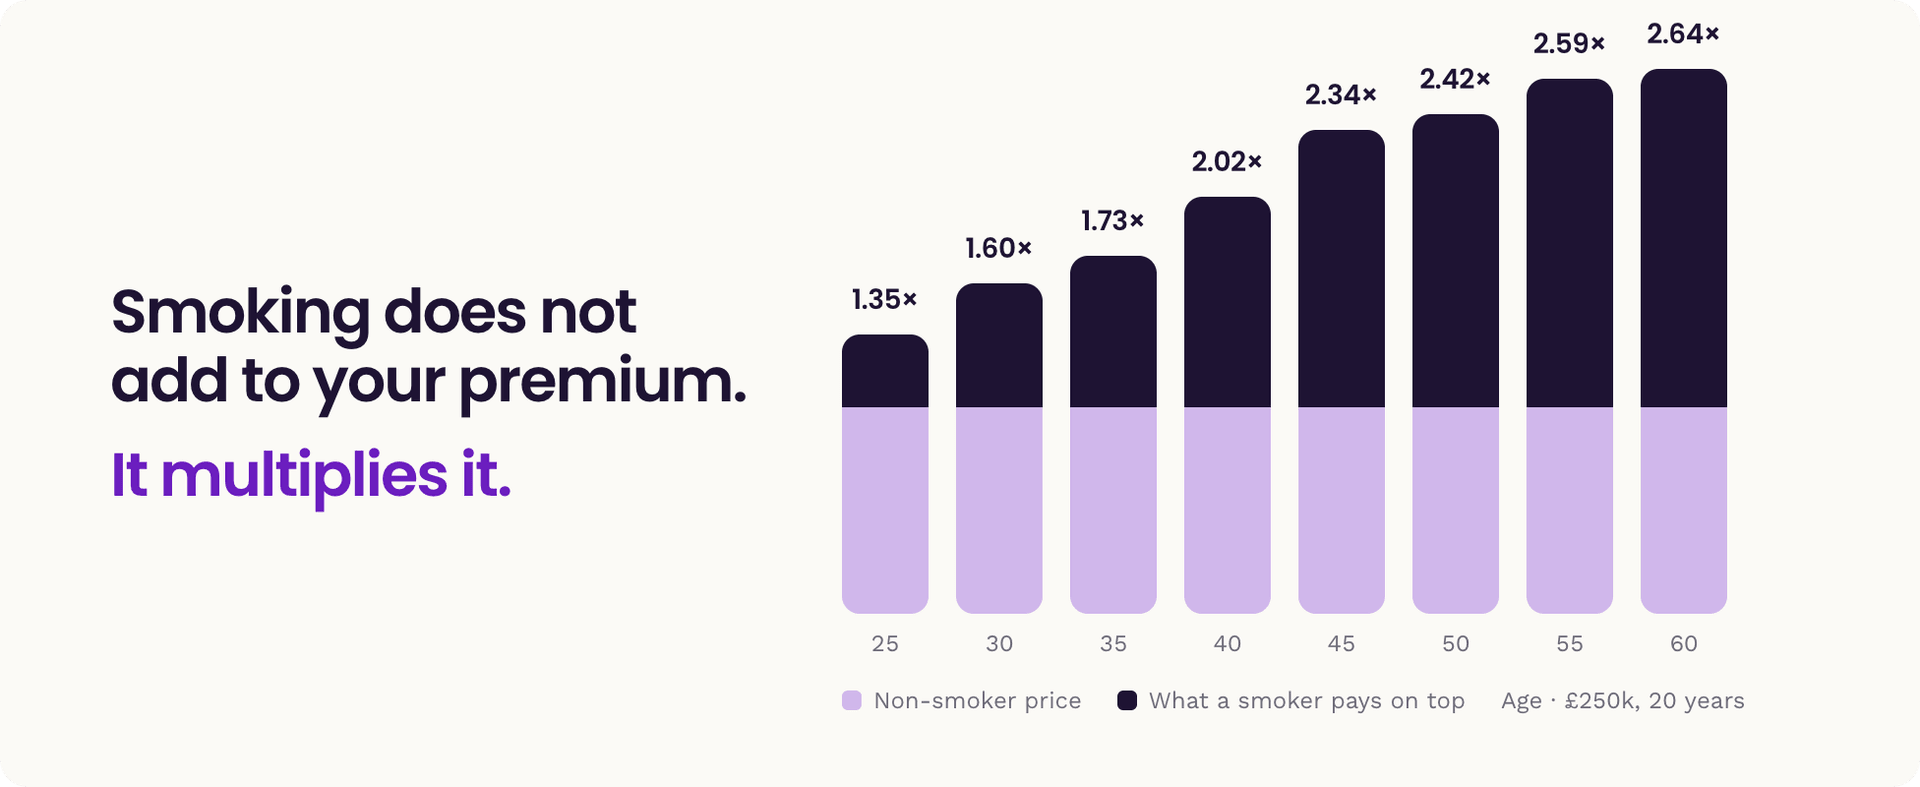
Smoking does not add a flat amount to your premium. It multiplies it, and the multiplier gets worse as you get older.
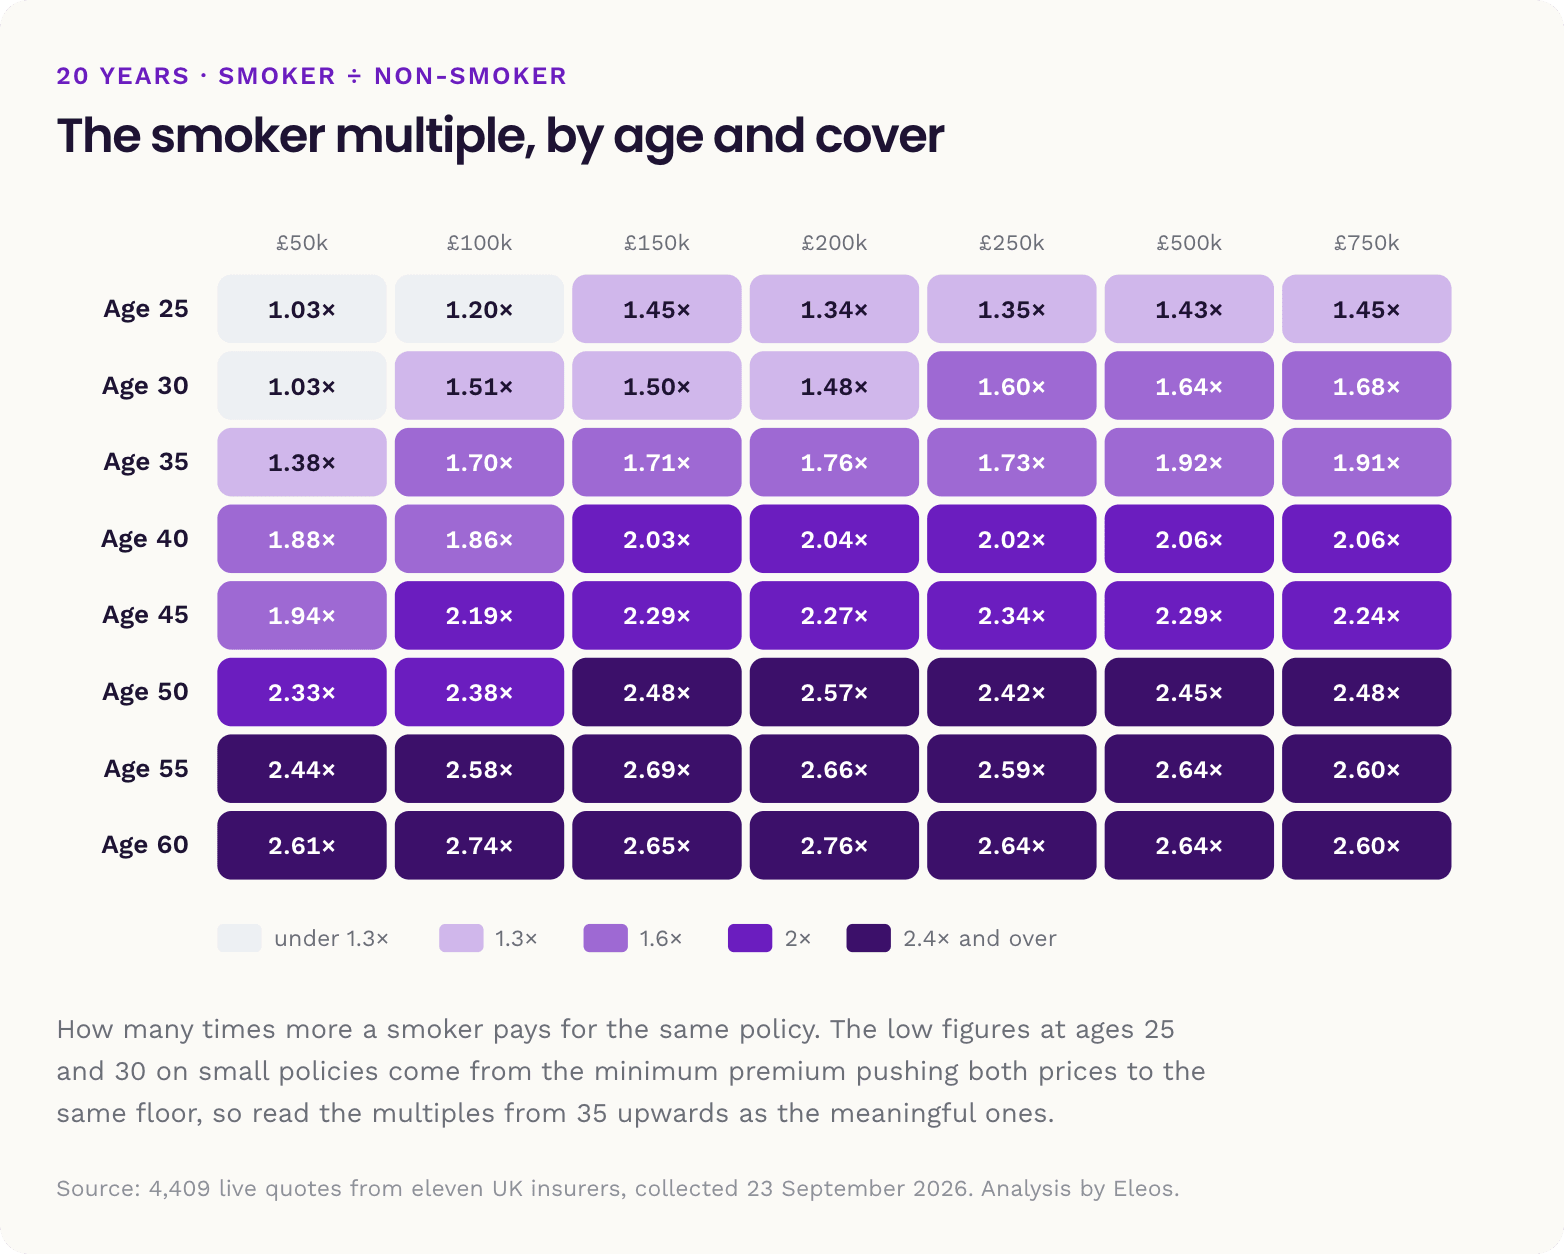
The multiple is remarkably steady across cover amounts. At 50 it sits between 2.33 and 2.57 whether you are buying £50,000 or £750,000. That means it collapses to a single number per age, which is unusual and useful.
Roughly: 1.2 times at 25, 1.7 at 35, 2.0 at 40, 2.2 at 45, 2.4 at 50, 2.6 at 55, 2.7 at 60.
One honest wrinkle. At ages 25 and 30 on small policies the multiple looks tiny, sometimes barely above 1. That is not a smoker discount, it is the minimum premium pushing both prices onto the same floor. Read the multiples from 35 upwards as the meaningful ones.
In money, over a full 20 year policy, it looks like this.
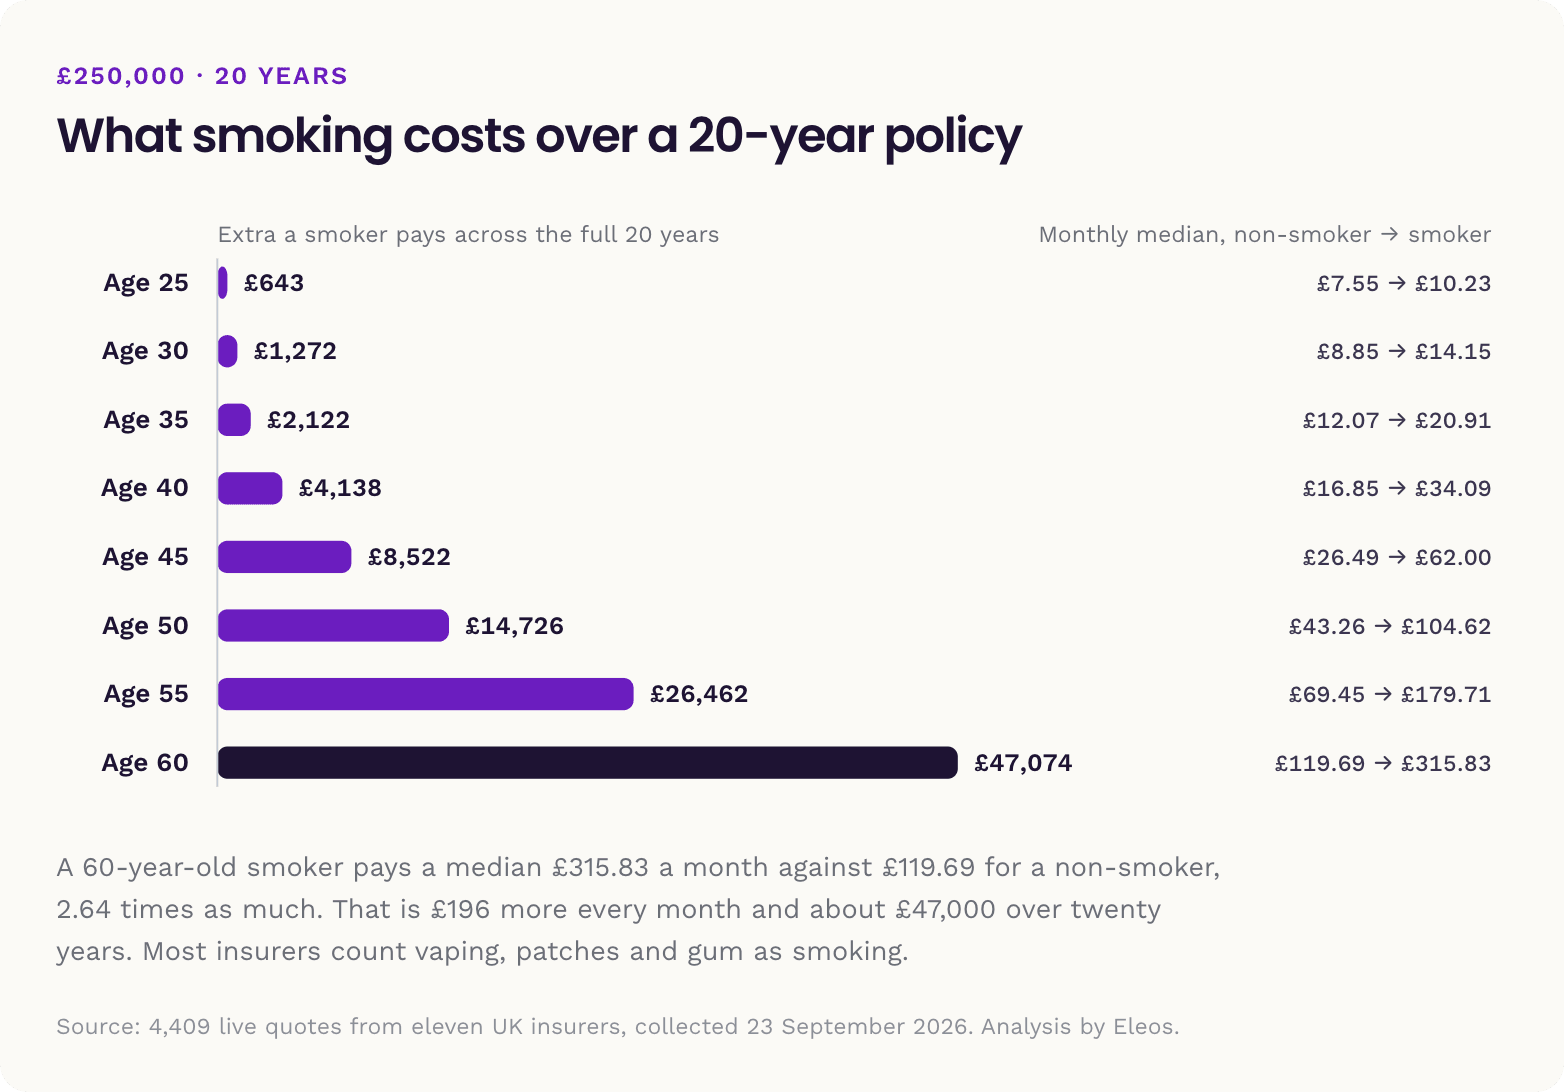
A 40 year old smoker pays about £17 a month more than a non-smoker for £250,000 of cover, which is roughly £4,100 across the policy. A 60 year old pays about £196 a month more, which is roughly £47,000.
Two practical notes. Most insurers count you as a smoker if you have used any nicotine in the last twelve months, and that usually includes vaping, patches and gum. And most want you nicotine free for a full year before they will price you as a non-smoker. The saving is real, but you have to wait for it.
Cover does not cost double when you double it. The price per pound of cover falls as you buy more.
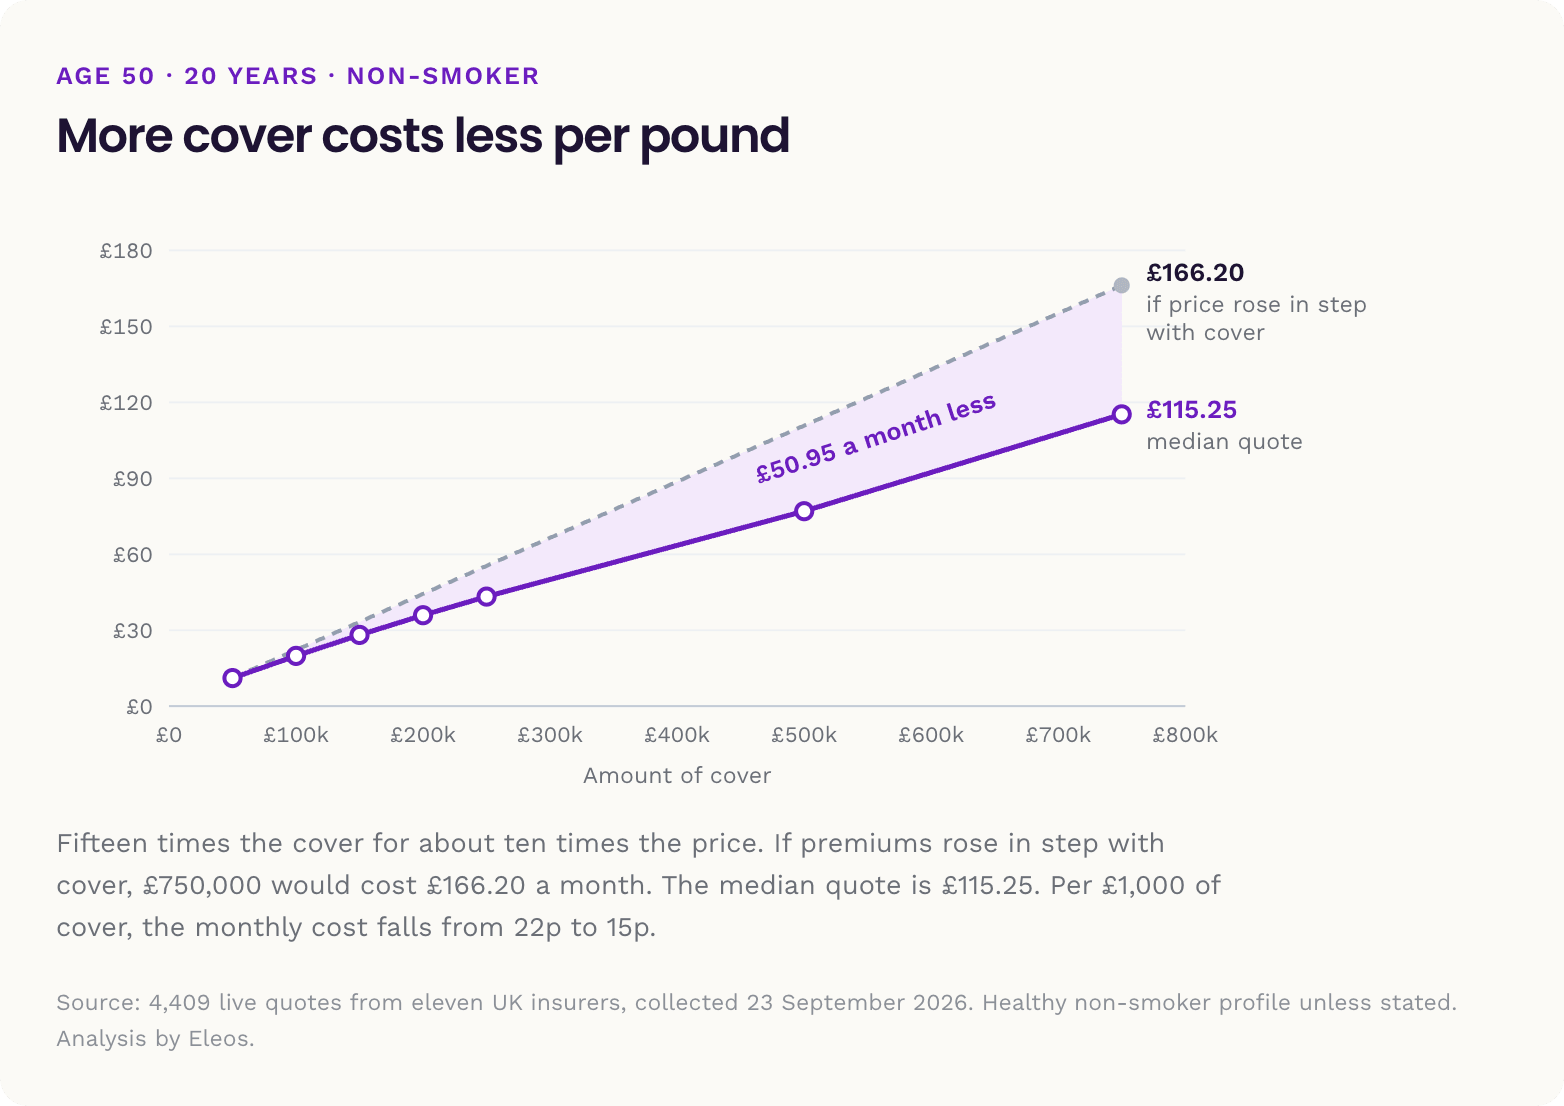
At 60, £50,000 of 20 year cover works out at about 60p per £1,000 each month, while £750,000 works out at about 42p. Fifteen times the cover at a much better rate.
Under 40 this goes further still, because of the minimum premium.
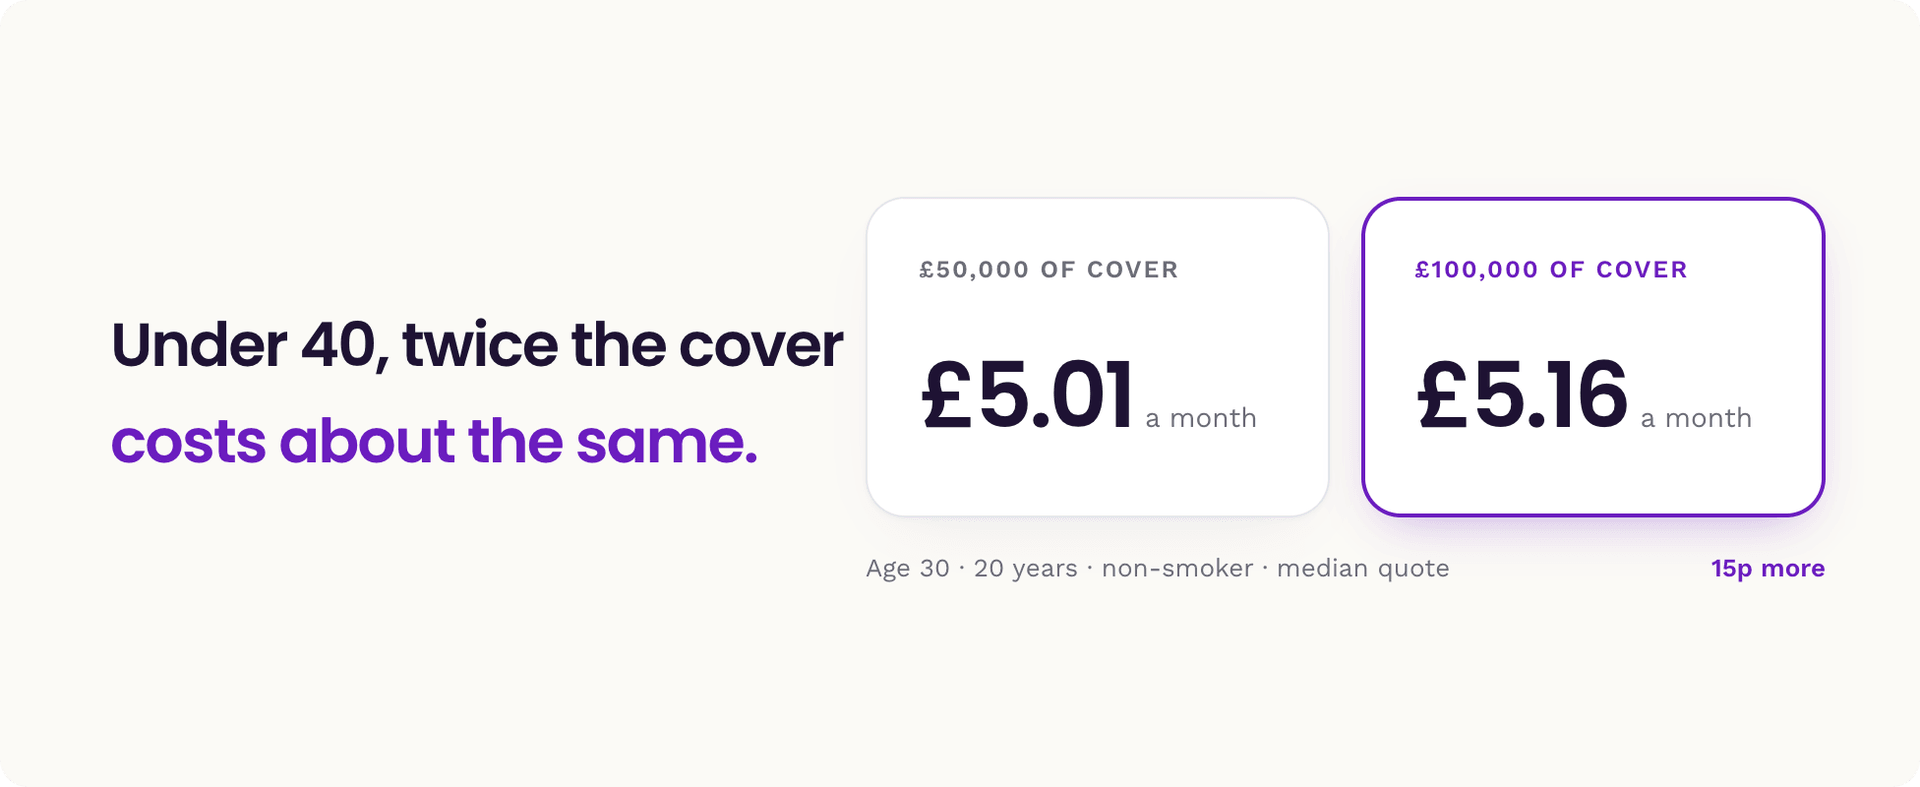
At 30, £50,000 of 20 year cover has a median price of £5.01. Doubling it to £100,000 costs £5.16. That is 15p a month for twice the payout.
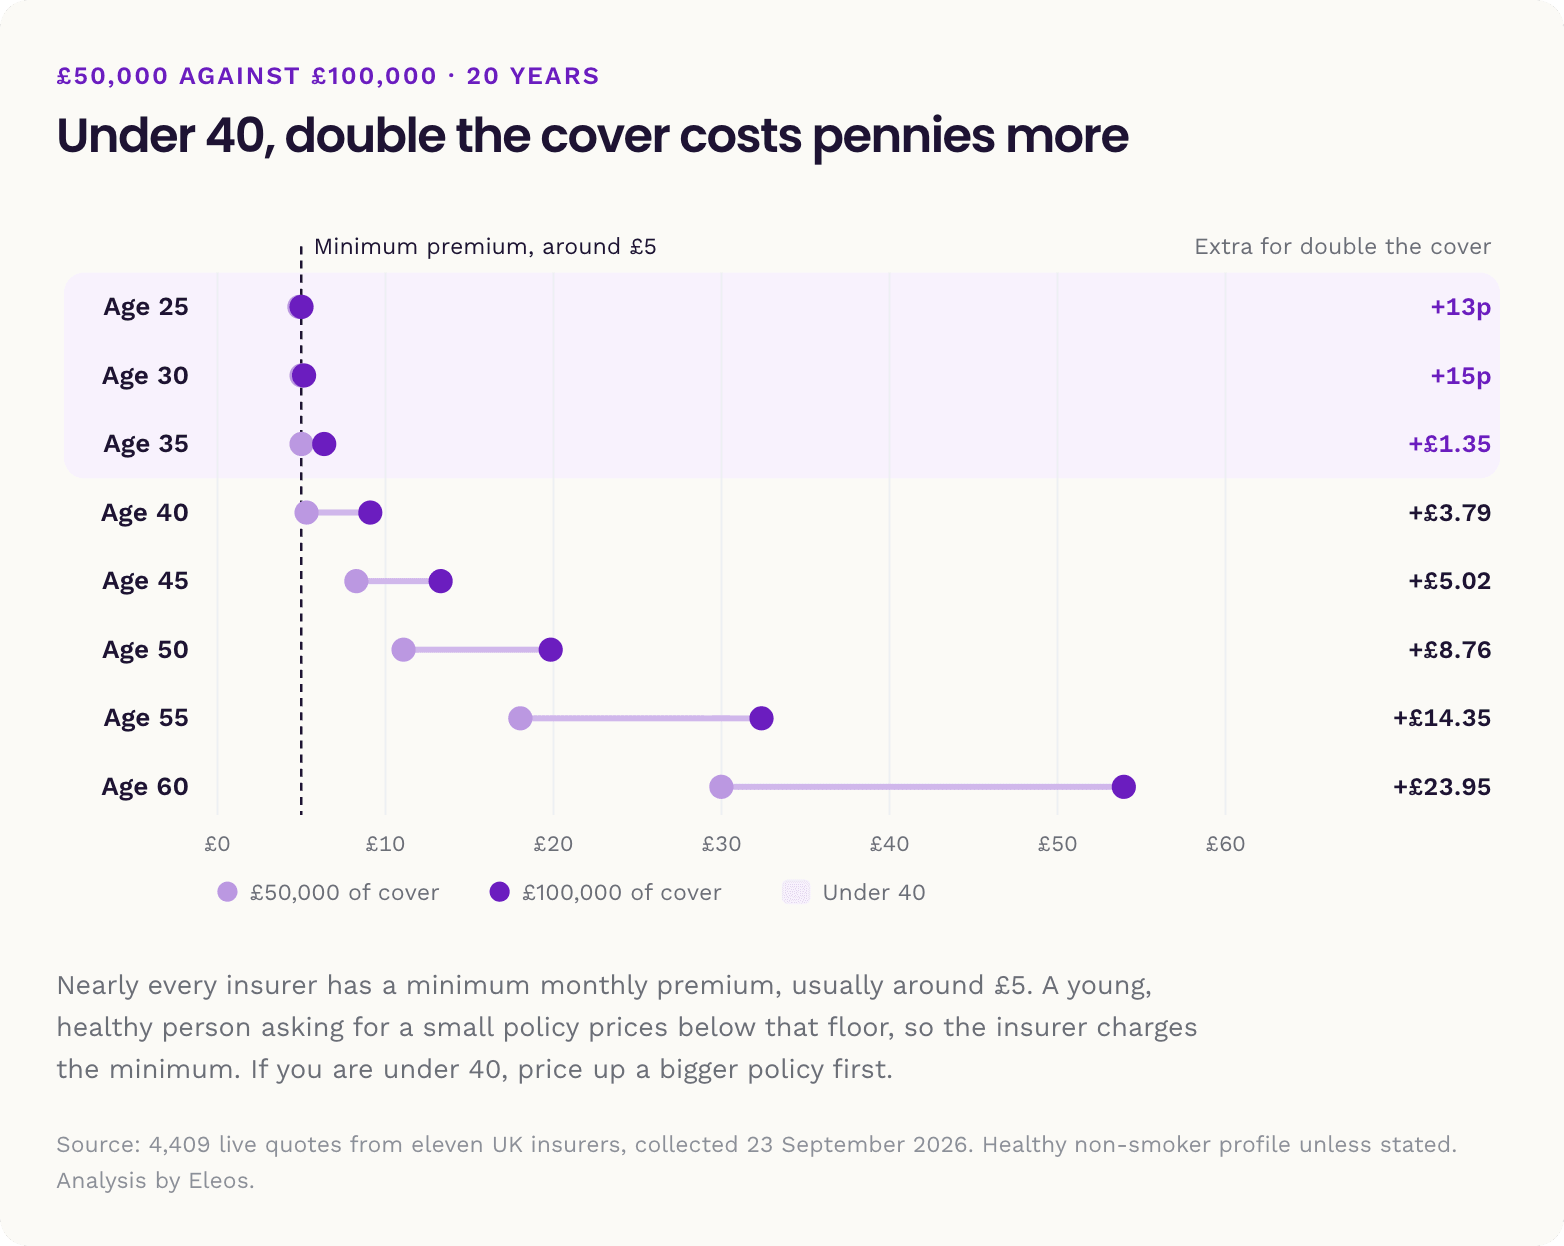
This is not an error in the data. Nearly every insurer has a minimum monthly premium, usually around £5 and sometimes as high as £8. A young healthy person asking for a small policy prices out below that floor, so the insurer just charges the minimum.
We saw this plainly. At age 25 several insurers came back offering far more cover than we had asked for, because they would not quote below their minimum. One offered over £300,000 of cover for £8 a month when we had asked for £50,000.
If you are under 40 and thinking about a small policy, price up a bigger one first. The extra cover may be close to free.
You might assume a 20 year policy costs twice what a 10 year one does. It does not.
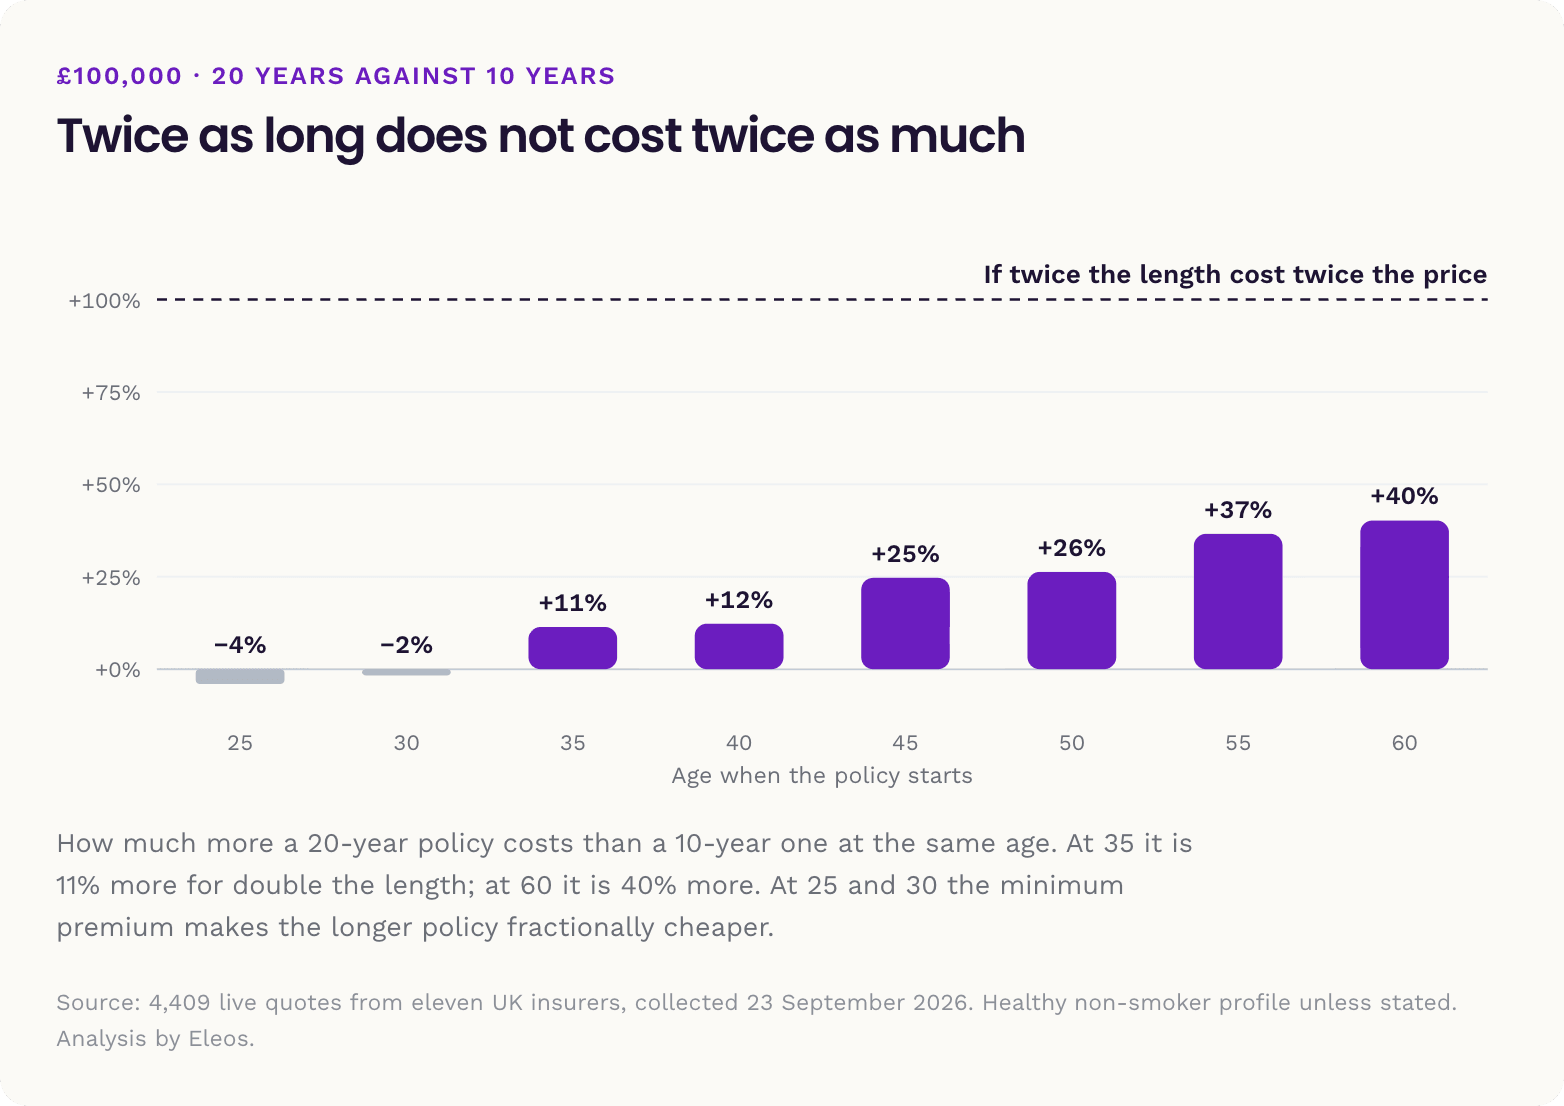
At 30, stretching £250,000 of cover from 10 years to 20 costs about 6% more. At 40 it is about 23% more. Even at 60, where the gap is widest, going from 10 to 20 years costs about 51% more, not 100%.
This matters because policy length is usually driven by something real, like how long is left on your mortgage or how many years until the children are grown. The data says stretching the term is rarely the expensive part of the decision.
If you are still deciding how much cover to buy in the first place, our guide on how much life insurance you need walks through the sums.
Everything above is level cover, where the payout stays the same for the whole policy. There is a second kind, and if you are buying cover because of a mortgage it is probably the one you want.
Decreasing cover, usually sold as mortgage protection, shrinks over time to track what is left on a repayment mortgage. If you want the plain explanation of how the two types differ, read level term versus decreasing term, and for how this fits alongside a mortgage see mortgage life insurance explained.
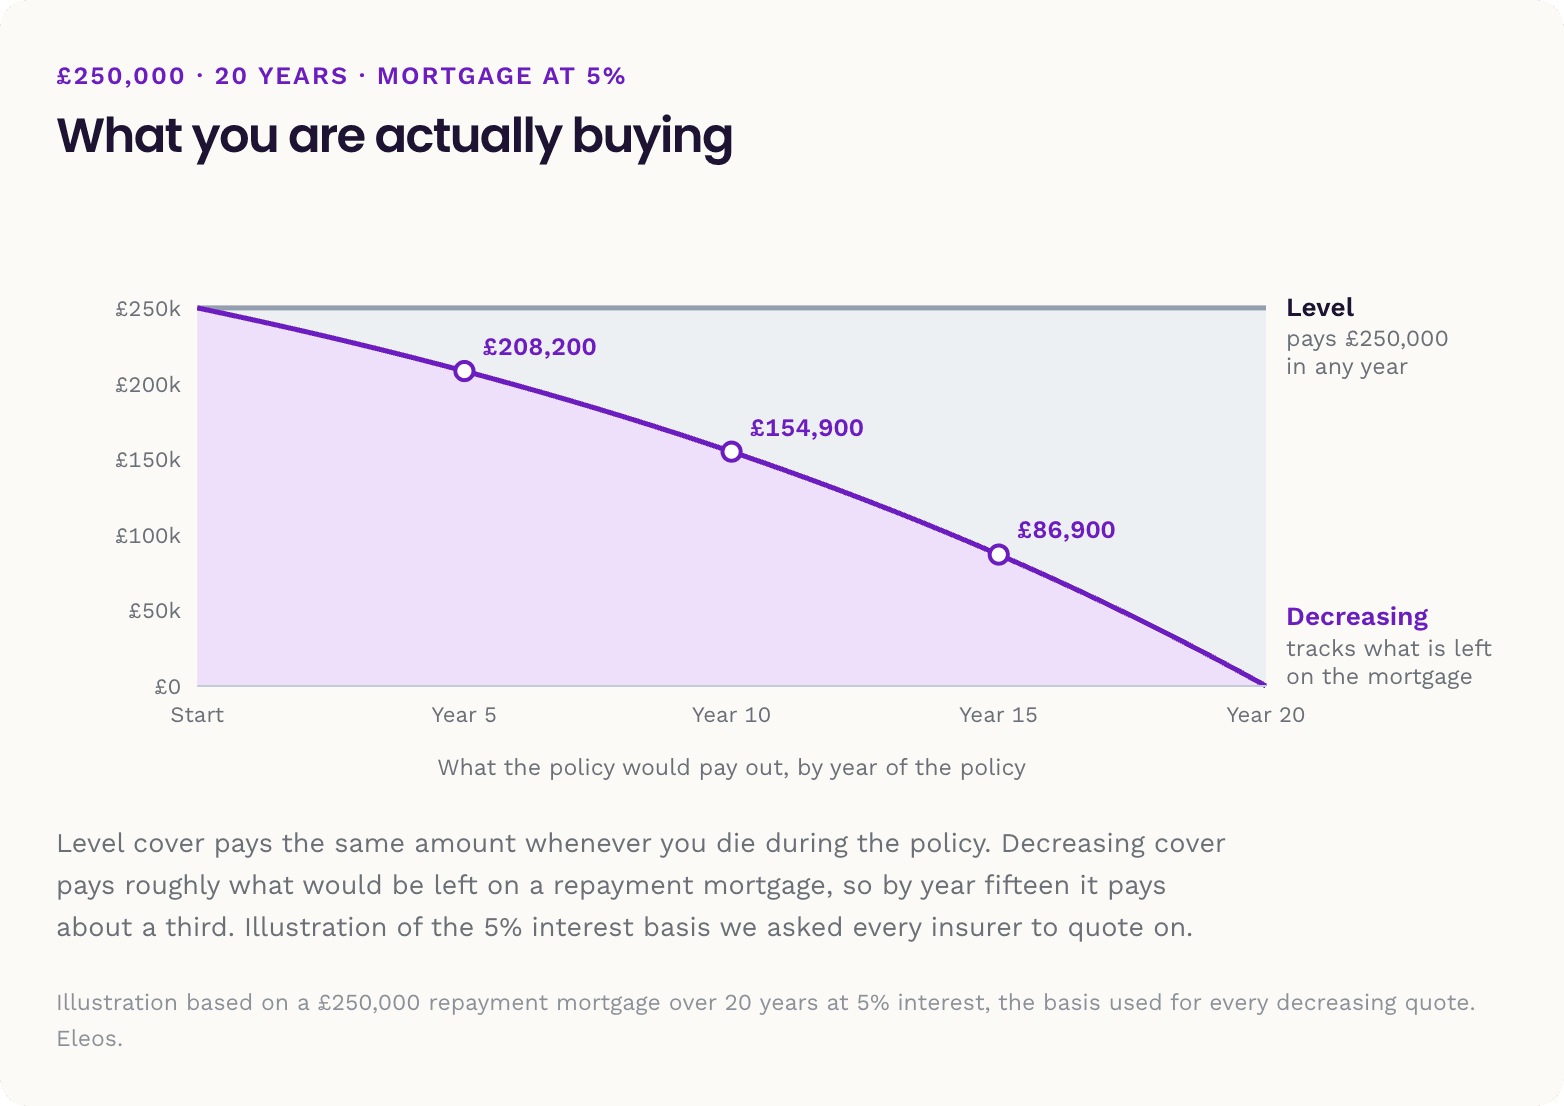
That is what you are actually buying. On a £250,000 mortgage at 5% over 20 years, level cover pays £250,000 whenever you die during the policy. Decreasing cover pays about £208,000 in year five, about £155,000 in year ten, and about £87,000 in year fifteen.
Because the insurer is on the hook for less as the years pass, it costs less.
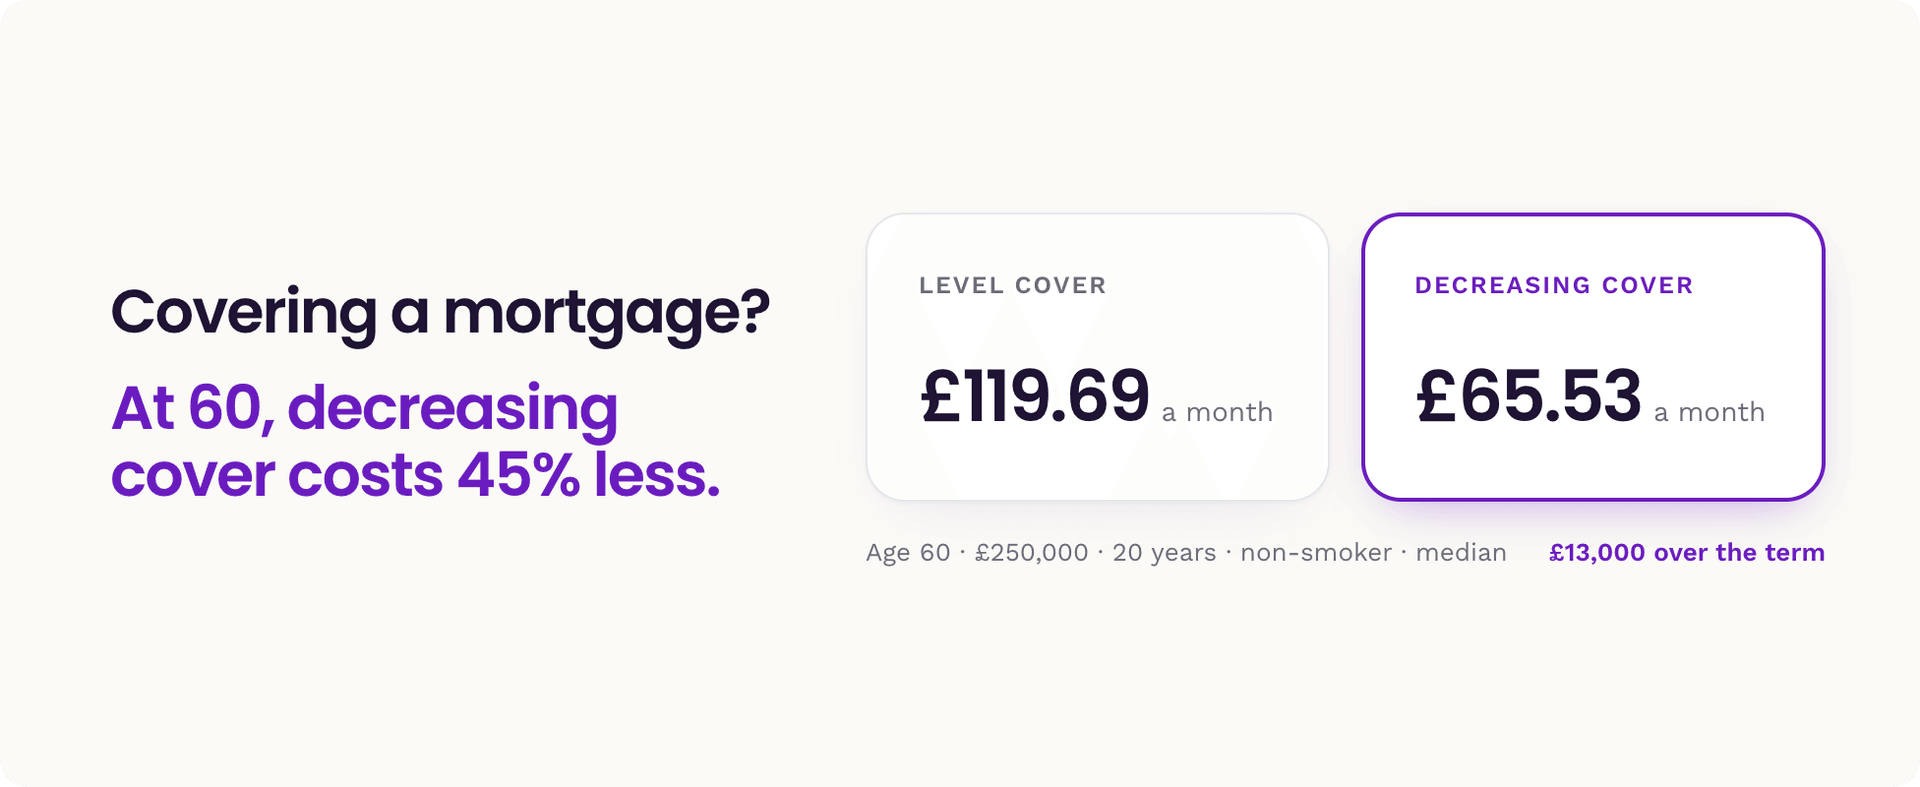
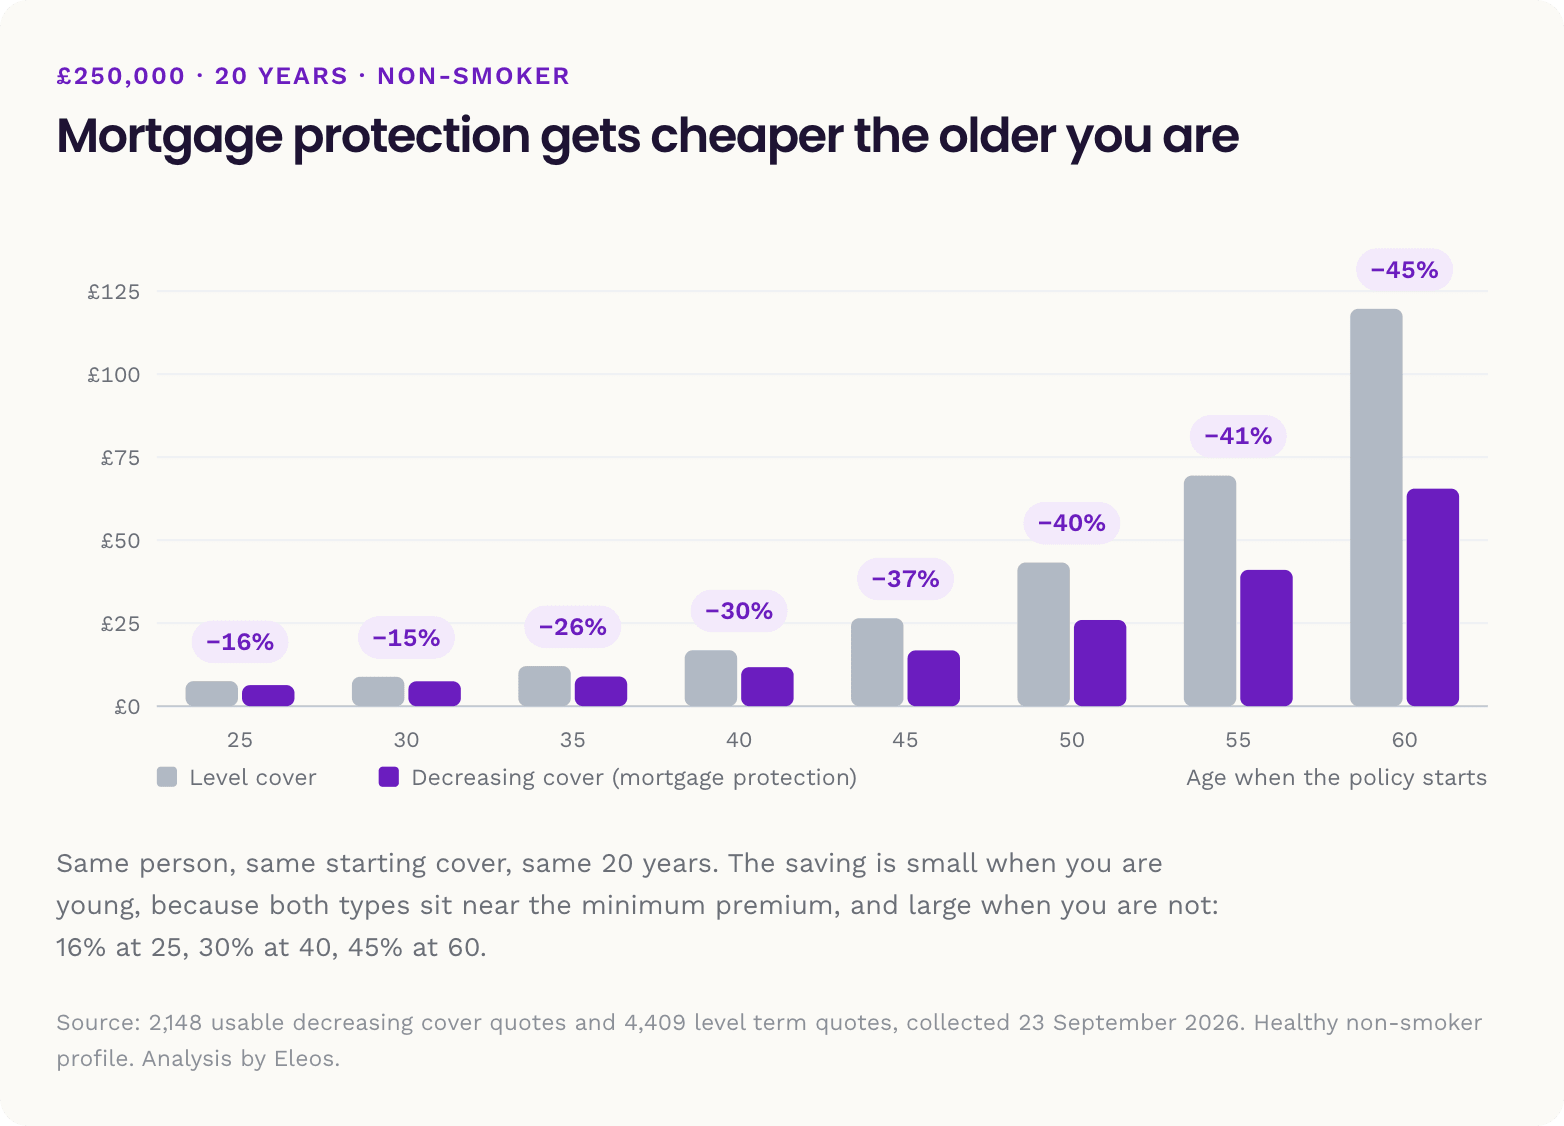
The saving is small when you are young and large when you are not. At 25 there is almost none, because both types are already on the minimum premium. By 40 you save around 30%. By 60 it is 45%.
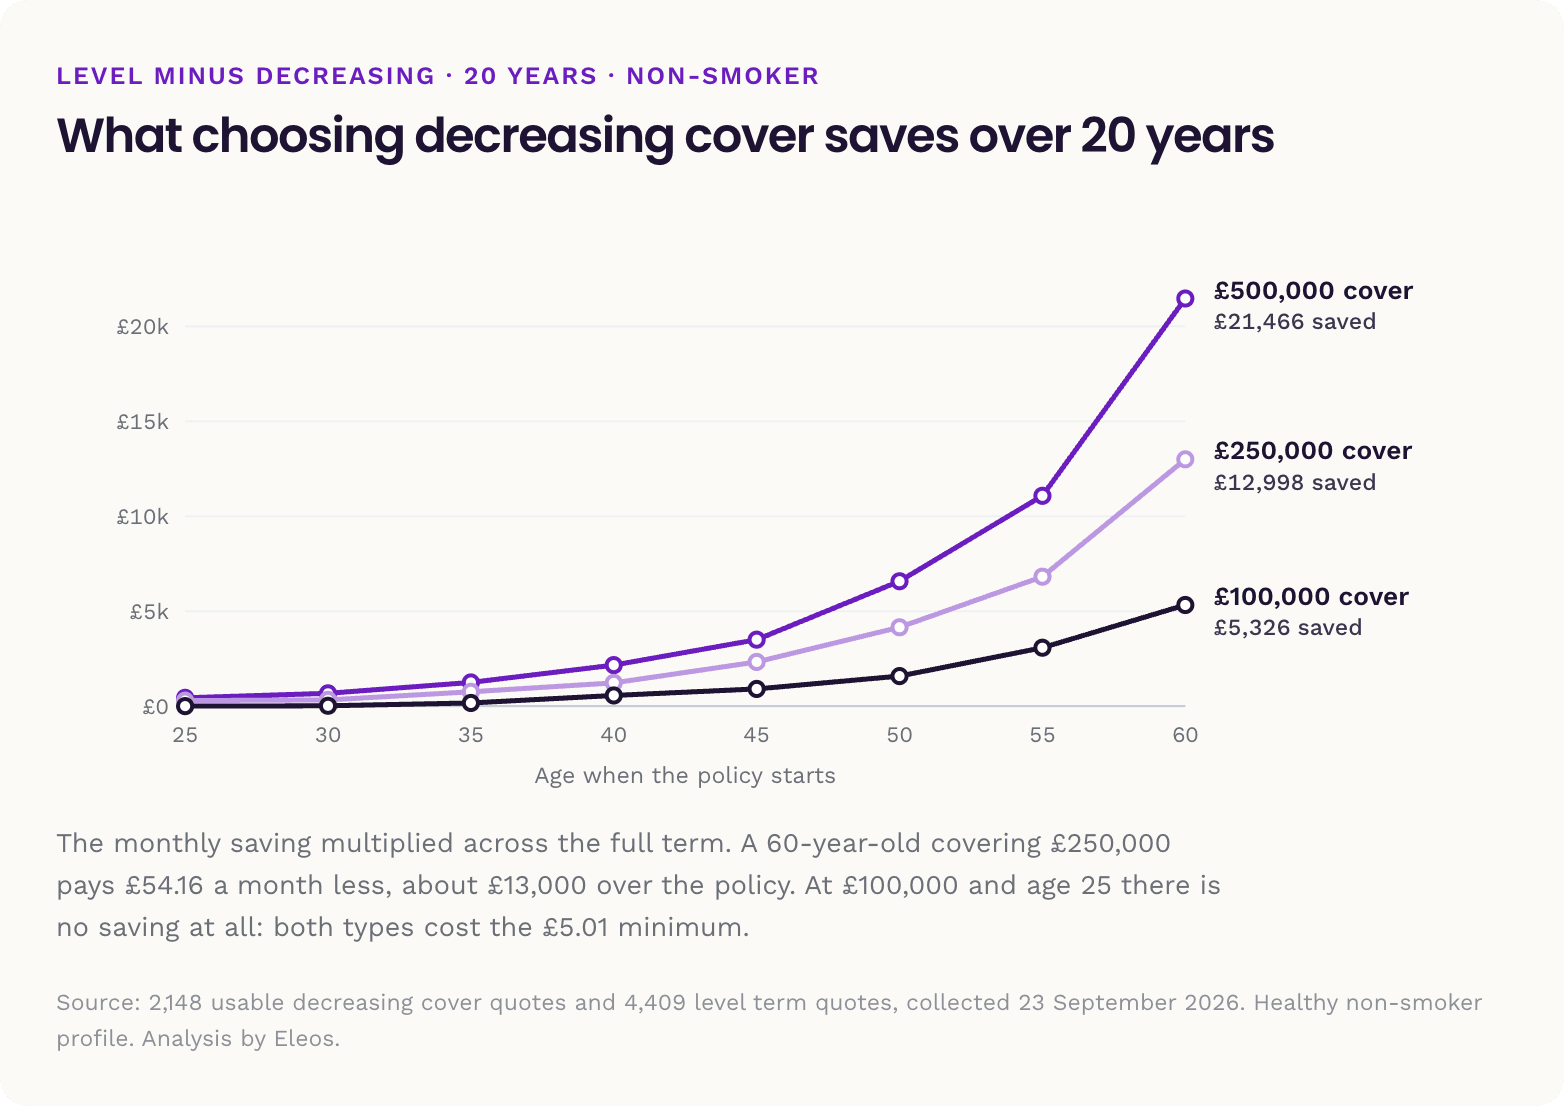
Put the two choices together with smoking and you get four very different prices for the same person.
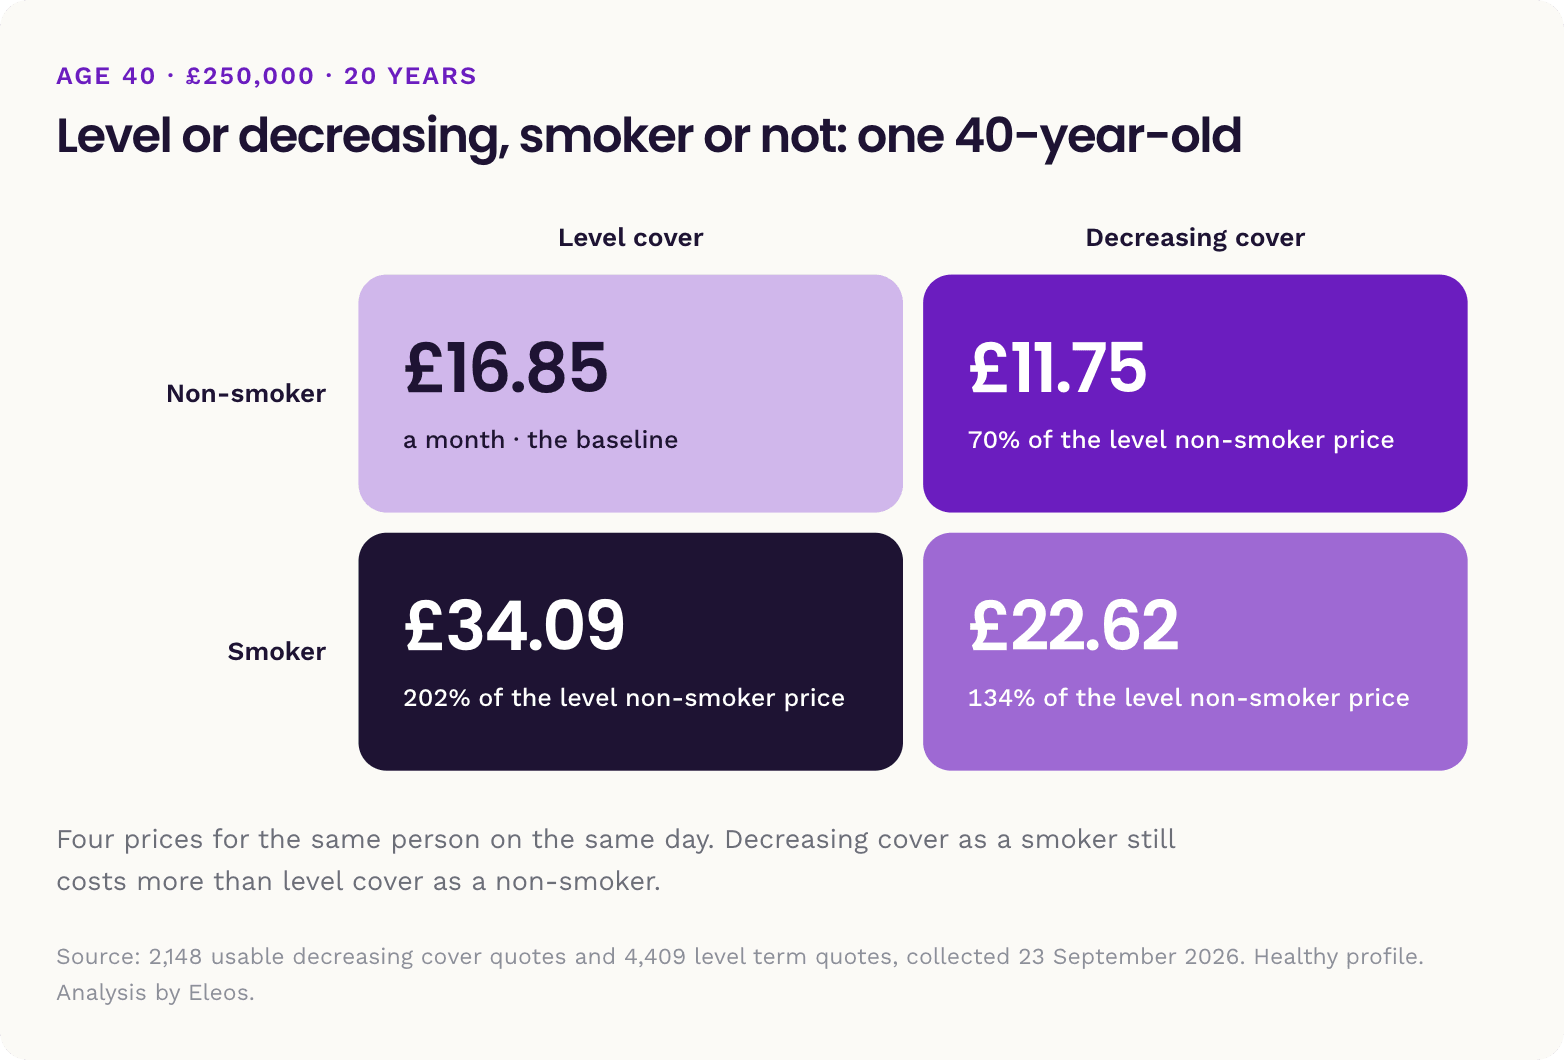
For a 40 year old wanting £250,000 over 20 years, the four prices run from £11.75 to £34.09 a month. Worth noticing: decreasing cover as a smoker still costs more than level cover as a non-smoker.
The smoking penalty works the same way on decreasing cover as it does on level.
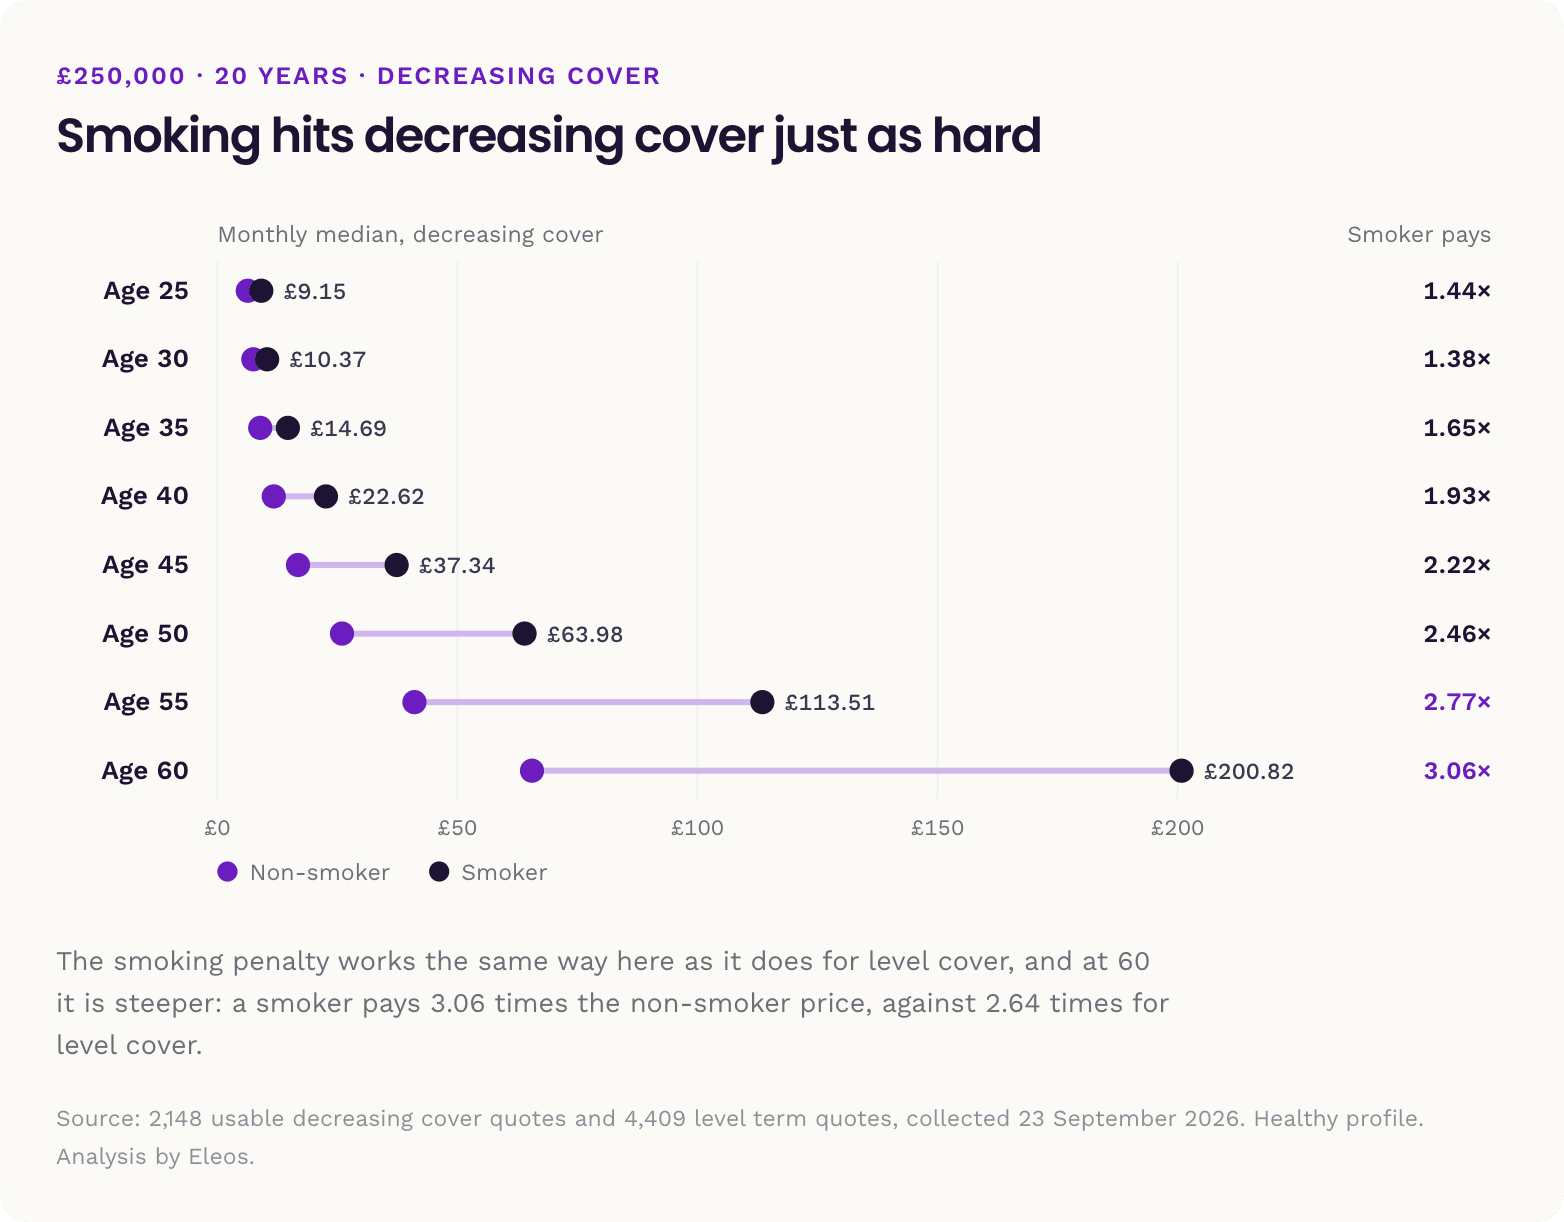
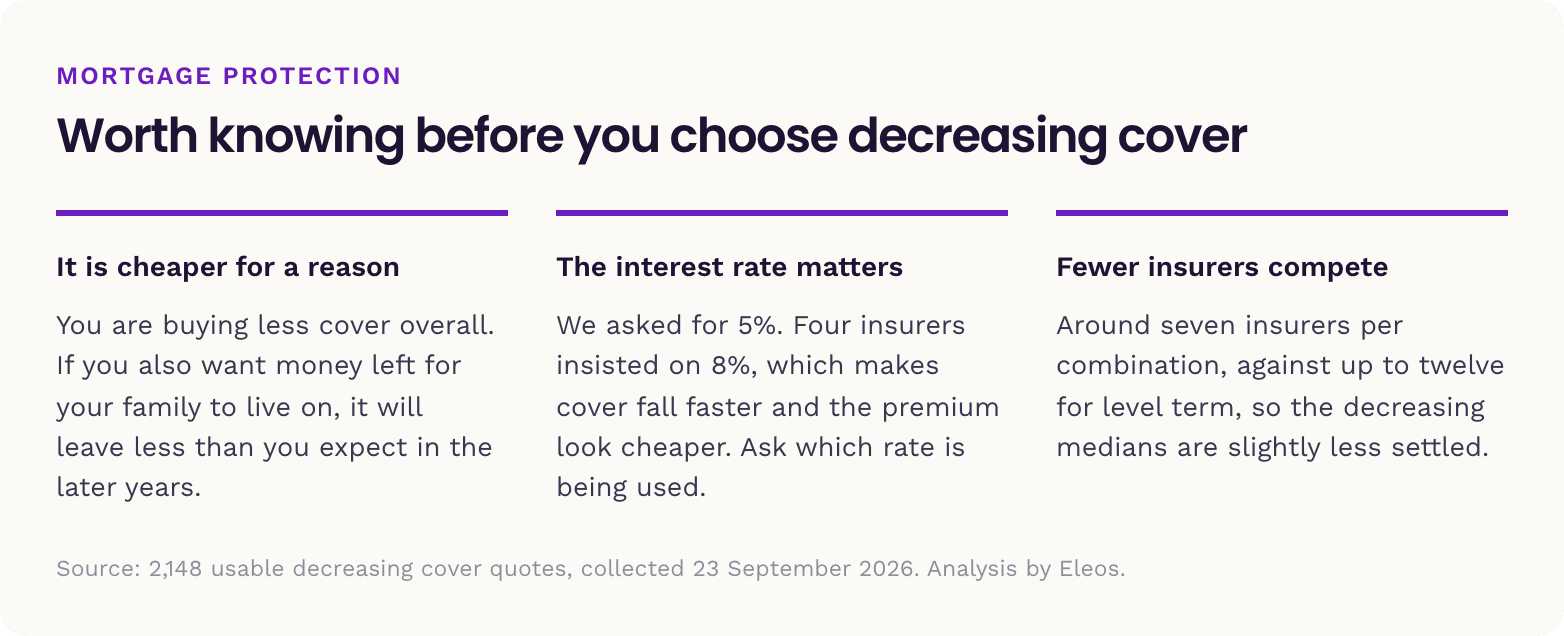
The interest rate point is the one most likely to catch you out. Decreasing cover falls at a rate the insurer assumes. We asked every insurer to quote at 5%. Four of them refused and insisted on their own rate of 8%, which makes the cover fall faster and the premium look cheaper. We excluded those quotes so we are comparing like with like. A low quote can simply mean fast shrinking cover, so ask which rate is being used.
| Age | £50k | £100k | £150k | £200k | £250k | £500k | £750k |
|---|---|---|---|---|---|---|---|
| 25 | n/a | £5.01 | £5.25 | £5.82 | £6.34 | £9.89 | £14.43 |
| 30 | n/a | £5.09 | £5.85 | £6.84 | £7.49 | £11.61 | £17.03 |
| 35 | £5.01 | £5.67 | £6.51 | £7.97 | £8.93 | £14.26 | £21.02 |
| 40 | £5.21 | £6.76 | £8.45 | £10.16 | £11.75 | £20.42 | £30.81 |
| 45 | £5.95 | £9.52 | £11.68 | £14.34 | £16.80 | £31.16 | £46.33 |
| 50 | £8.13 | £13.25 | £17.56 | £21.72 | £25.96 | £49.58 | £73.94 |
| 55 | £11.75 | £19.57 | £25.83 | £33.10 | £41.05 | £77.67 | £114.73 |
| 60 | £18.24 | £31.75 | £43.33 | £56.19 | £65.53 | £128.98 | £186.20 |
| Age | £50k | £100k | £150k | £200k | £250k | £500k | £750k |
|---|---|---|---|---|---|---|---|
| 25 | £5.01 | £5.81 | £6.85 | £8.14 | £9.15 | £15.13 | £21.27 |
| 30 | £5.01 | £6.32 | £8.03 | £8.69 | £10.37 | £19.41 | £27.08 |
| 35 | £5.84 | £7.87 | £10.27 | £12.53 | £14.69 | £27.05 | £35.99 |
| 40 | £7.11 | £11.50 | £15.56 | £19.54 | £22.62 | £42.14 | £60.97 |
| 45 | £10.90 | £18.15 | £24.72 | £31.41 | £37.34 | £69.94 | £103.86 |
| 50 | £17.14 | £29.88 | £41.34 | £53.88 | £63.98 | £122.65 | £176.34 |
| 55 | £28.45 | £50.32 | £71.07 | £93.50 | £113.51 | £220.55 | £287.19 |
| 60 | £51.92 | £89.11 | £127.81 | £165.37 | £200.82 | £392.94 | £512.60 |
| Age | £50k | £100k | £150k | £200k | £250k | £500k | £750k |
|---|---|---|---|---|---|---|---|
| 25 | n/a | £5.01 | £5.48 | £6.38 | £6.87 | £10.66 | £15.90 |
| 30 | £5.01 | £5.03 | £6.25 | £7.26 | £7.89 | £12.82 | £19.06 |
| 35 | £5.01 | £5.86 | £7.41 | £8.59 | £9.70 | £16.27 | £24.51 |
| 40 | £5.36 | £7.47 | £9.36 | £11.45 | £13.26 | £23.44 | £34.60 |
| 45 | £6.62 | £10.25 | £13.13 | £16.60 | £19.58 | £35.98 | £53.43 |
| 50 | £9.08 | £14.98 | £20.35 | £25.47 | £30.41 | £59.97 | £88.76 |
| 55 | £13.17 | £23.63 | £31.55 | £40.16 | £46.83 | £98.25 | £144.60 |
| 60 | £21.44 | £39.05 | £53.29 | £67.50 | £77.20 | £147.97 | £221.95 |
| Age | £50k | £100k | £150k | £200k | £250k | £500k | £750k |
|---|---|---|---|---|---|---|---|
| 25 | £5.01 | £5.88 | £7.34 | £8.63 | £9.72 | £16.19 | £22.87 |
| 30 | £5.14 | £6.75 | £8.61 | £10.16 | £11.80 | £21.39 | £30.42 |
| 35 | £6.02 | £8.90 | £11.67 | £14.51 | £16.93 | £31.23 | £45.89 |
| 40 | £8.18 | £13.27 | £17.93 | £22.69 | £26.12 | £50.10 | £72.72 |
| 45 | £12.61 | £21.46 | £29.62 | £37.49 | £44.03 | £84.56 | £116.36 |
| 50 | £20.45 | £35.39 | £49.81 | £63.39 | £76.56 | £150.18 | £208.24 |
| 55 | £34.39 | £60.38 | £84.72 | £109.44 | £134.77 | £252.68 | £369.44 |
| 60 | £58.74 | £102.28 | £142.39 | £185.67 | £229.87 | £437.90 | £661.12 |
| Age | £100k level | £100k decreasing | £250k level | £250k decreasing | £500k level | £500k decreasing |
|---|---|---|---|---|---|---|
| 25 | £5.01 | £5.01 | £7.55 | £6.34 | £11.71 | £9.89 |
| 30 | £5.16 | £5.09 | £8.85 | £7.49 | £14.42 | £11.61 |
| 35 | £6.36 | £5.67 | £12.07 | £8.93 | £19.46 | £14.26 |
| 40 | £9.10 | £6.76 | £16.85 | £11.75 | £29.42 | £20.42 |
| 45 | £13.29 | £9.52 | £26.49 | £16.80 | £45.74 | £31.16 |
| 50 | £19.84 | £13.25 | £43.26 | £25.96 | £76.99 | £49.58 |
| 55 | £32.38 | £19.57 | £69.45 | £41.05 | £123.82 | £77.67 |
| 60 | £53.94 | £31.75 | £119.69 | £65.53 | £218.42 | £128.98 |
Now the important caveat. Every price in this article is for someone with nothing to declare. If you have a health condition your price will be different, and our data cannot tell you by how much.
When you get a quote, the insurer has not really looked at you yet. They have your age, your build, whether you smoke, and not much else. The quote assumes you are in good health. Underwriting is what comes next.
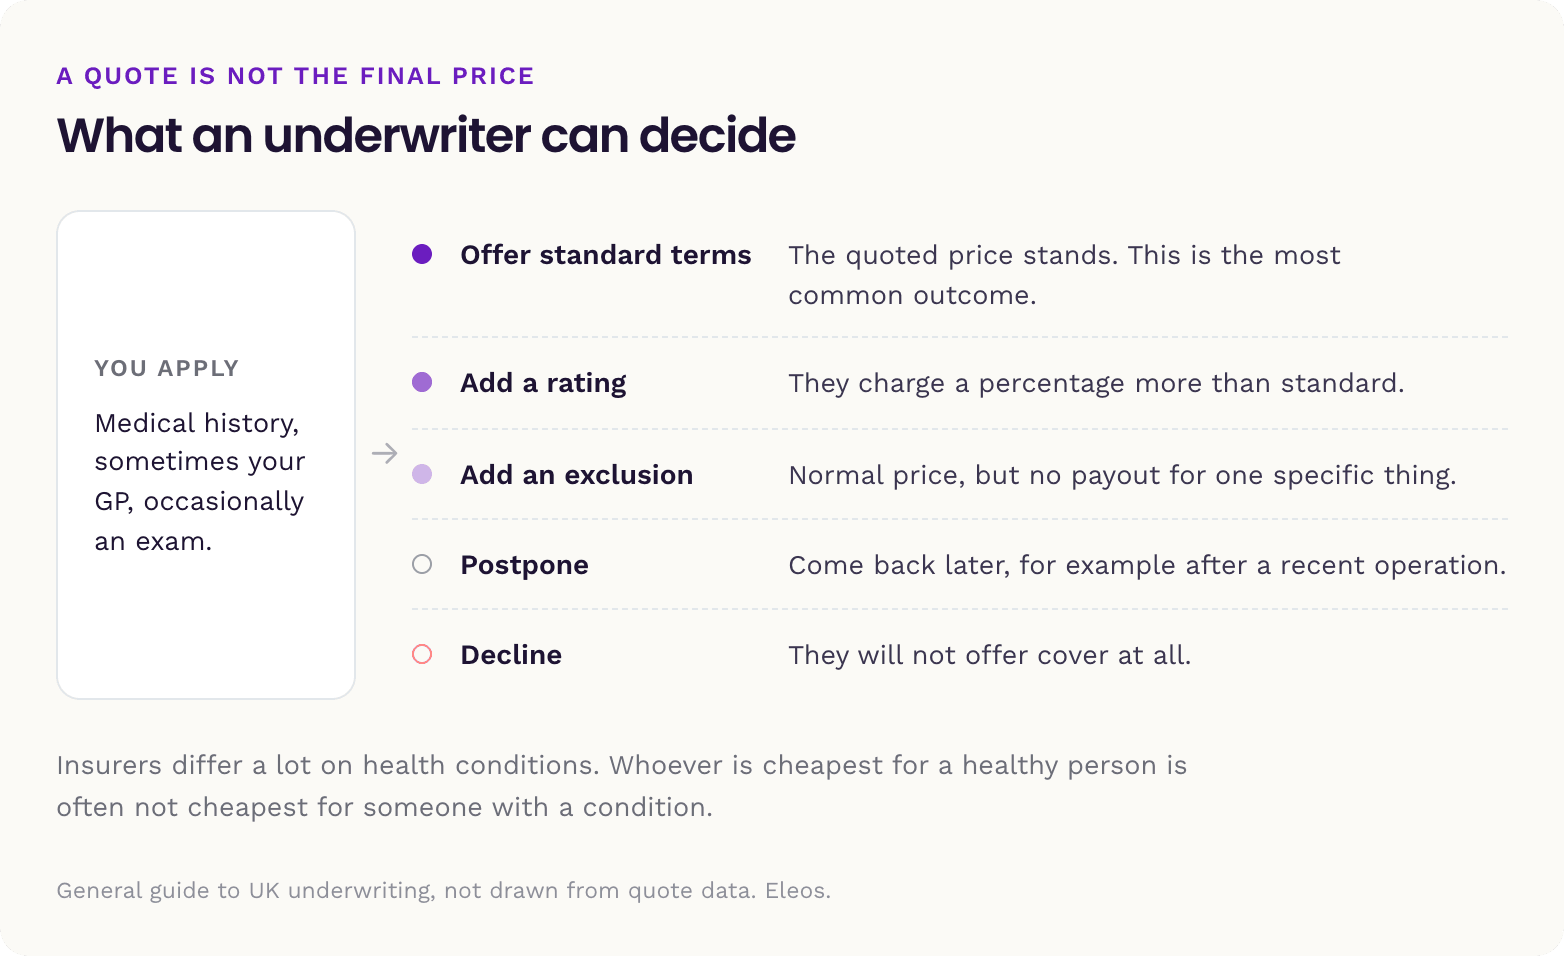
This part is general knowledge about how UK underwriting works. It is not from our quote data, because our data only covers a healthy profile. Treat it as a guide to what to expect, not as a price list.
Weight. Build is the one health factor already baked into every quote, because height and weight are compulsory questions. A higher BMI generally means a higher price, and past a certain point some insurers decline.
High blood pressure. If it is diagnosed, treated and under control, many people get standard terms or a small rating. Uncontrolled or newly diagnosed is treated more carefully.
Type 2 diabetes. Usually leads to a rating. How big depends on how well controlled it is, how long you have had it, and whether there are complications.
Asthma. Mild and well controlled asthma very often gets standard terms. Severe asthma with hospital admissions is looked at differently.
Mental health. Depends heavily on how severe and how recent. A single episode of mild depression years ago is often standard. Recent hospital treatment is assessed much more carefully.
Cancer history. Depends almost entirely on the type, the stage, and how long ago treatment ended. Plenty of people who finished treatment years ago can get cover. Recent diagnoses are usually postponed or declined.
Family history. Some insurers ask whether close relatives had certain conditions before a given age. This can affect your price even when you are perfectly healthy yourself.
The honest summary is that insurers differ a lot from each other on health conditions. Whoever is cheapest for a healthy person is often not cheapest for someone with a condition. That is the strongest argument in this whole article for not simply taking the first quote you see.
Not every product works this way. Some life insurance is priced only on age, cover amount, policy length and smoking status, with the health questions used to decide yes or no rather than to adjust the price. With that kind of policy, the price you are quoted is the price you pay, or you are told you cannot be covered. There is no middle ground where the price creeps up after you apply.
It is worth asking any insurer which of the two you are dealing with, because it changes what a quote actually means.
We would rather say this plainly than bury it.
It is one person, not a national average. Every number here is for the healthy profile described earlier. It is not what the average UK buyer pays.
It is one day. All quotes were collected in September 2026. Insurers change their rates through the year.
It is quotes, not sales. We recorded what was offered, not what people bought. A comparison site publishing what its customers actually paid is measuring something different. Both are useful, and neither replaces the other.
These came through an adviser platform. The quotes include commission. We have not yet confirmed whether buying direct from an insurer gets you the same price, a better one or a worse one.
Five level term combinations are missing. Out of 336 we captured 331. The five gaps are 25 year policies for smokers wanting £750,000 at ages 40 to 60, where the platform timed out.
One product is excluded. The panel includes a benchmark product that members of the public cannot buy. We collected it but left it out of every figure here, because including it would have distorted the results badly at older ages.
The decreasing cover panel is smaller. Around seven insurers per combination, against up to twelve for level term, because several insurers would only quote decreasing cover on their own interest rate assumption. Fewer quotes means wider confidence ranges, so treat the decreasing medians as slightly less settled.
Quotes collected in September 2026 through a whole of market adviser research platform.
Held constant: male, 178cm, 78kg (BMI 24.6), no occupation entered, no previous smoker history, life cover only with no critical illness, guaranteed premiums, level premiums, no children's critical illness benefit, cover starting immediately.
Varied: age (25, 30, 35, 40, 45, 50, 55 and 60), cover amount (£50,000, £100,000, £150,000, £200,000, £250,000, £500,000 and £750,000), policy length (10, 20 and 25 years), and smoking status.
Level term: 331 of 336 combinations captured, producing 4,409 individual insurer quotes. Every run was checked to carry its own unique transaction reference, so no result was counted twice or carried over. Between three and four insurers declined to quote on any given run, which is normal.
Mortgage protection: the same grid of 336 combinations, with cover set to follow a repayment mortgage at 5% interest. That run recorded a row for every insurer on every combination, including those that declined, giving 5,040 rows. After removing quotes with no premium, quotes where the insurer applied its own interest rate instead of 5%, quotes where the insurer changed the cover amount, and quotes where a different product was substituted, 2,148 usable quotes remain across 330 of the 336 combinations, typically seven insurers each.
Where an insurer returned a different amount of cover than requested, because of a minimum premium, that quote was left out of the statistics for that cover amount but kept in the underlying data. This is why the number of quotes behind each figure varies, and why it is lower at younger ages.
Confidence intervals are 95% intervals around the mean, calculated with the t distribution, treating the insurers who quoted as a sample of the market.
A complete UK guide to term life insurance: how it works, what it costs, the main policy types, underwriting, how it compares with whole of life, and the top UK providers.
New Year, new money mindset. It’s time to break free from financial anxiety once and for all. Here are six simple tips to boost your financial resilience in 2026 and bring you peace of mind all year long!
Life insurance for young adults doesn't have to be complicated or costly. This comprehensive guide covers why purchasing life insurance as a young adult locks in lower rates based on current health and how to pick the proper policy length and provider for your situation.
Introducing Theea's Coverage Calculator: the intuitive insurance tool inspired by thousands of customer conversations that turns anxiety into tailored advice and confusion into confident choices.
We’re expanding our perks with two new additions designed to turn good intentions into healthy habits. Discover everything you can get for free with an Eleos policy.