Who should your life insurance beneficiary be?
Contents
A life insurance beneficiary is the person, or people, you'd like to receive the proceeds of your policy when you die. You can choose one person or several, and beneficiaries can include family members, friends, charities, or children.
It's worth understanding one key point up front: in the UK, simply naming someone as a beneficiary doesn't always guarantee they'll receive the money directly. Unless your policy is written in trust (or your insurer offers a formal beneficiary nomination), the payout usually forms part of your estate and is distributed according to your will, or the intestacy rules if you don't have one. Writing your policy in trust is the most reliable way to make sure the money goes to the person you have in mind.
If you don't make any arrangements at all, the payout will become part of your estate when you die, which can make those who inherit potentially liable for inheritance tax.
This is where UK life insurance differs from what you might have read about elsewhere. In the United States, "naming a beneficiary" on a policy gives that person a direct legal right to the payout. In the UK, that isn't automatically the case.
Unless your policy is placed in trust or your insurer specifically allows a beneficiary nomination, the money is paid to your estate and handled by your executor, then shared out according to your will or the intestacy rules. The insurer pays your legal representatives, not the beneficiary directly.
For this reason, most UK policyholders who want a specific person to receive the money reliably, and quickly, write their policy in trust. A trust lets you set out who benefits and appoints trustees to manage the payout. Some insurers also offer a nomination facility, which can be updated by completing a form, often online or by phone. If you want to change who benefits, you can usually do so at any time while you're alive, provided you have mental capacity, but this can't be changed after you've died.
There are very few restrictions on who you can choose. Most people name their spouse, civil partner, or children, but you're free to choose other relatives, friends, or a charity. You can also name a trust as the beneficiary.
How many life insurance beneficiaries can I have?
You can name more than one beneficiary. If you do, it's important to set out clearly how the payout should be divided, usually by giving each person a percentage share. Without clear instructions, there could be disputes between beneficiaries, which in some cases can lead to legal action.
It can help to think through a few questions before you decide:
- Who relies on you financially, and who would be most affected if your income stopped?
- Does anyone have particular financial needs, for example a dependent child or family member?
- Are there debts to cover, such as a mortgage or tuition fees?
- How many people do you want to benefit?
- Would you like a charity to receive a share, or all, of the proceeds?
- Could a large lump sum cause problems for someone, for instance affecting their means-tested benefits?
Family and friends
Immediate family and close friends are the most common choices. A spouse or civil partner is often the first beneficiary people think of, partly because payouts to a spouse or civil partner are generally free of inheritance tax.
Contingent beneficiaries
It's sensible to name backup, or "contingent," beneficiaries in case your first choice dies before you do. This helps make sure the money still goes where you'd want it to, rather than defaulting into your estate.
Children as beneficiaries
Life insurance can be a valuable way to support children into adult life. However, children can't receive a lump sum directly. In England, Wales, and Northern Ireland, the money must be held on their behalf, usually in a trust, until they turn 18. In Scotland, a child can receive and manage money from the age of 16. Setting up a trust and appointing trustees is the usual way to manage the funds until the child is old enough.
Charities as beneficiaries
A charity can be a primary or a contingent beneficiary, in the same way as an individual. Leaving money to charity can also reduce the inheritance tax payable on your estate in some circumstances.
Trustees as beneficiaries
Putting your life insurance in trust is a good way of keeping control over how the payout is distributed, helping it reach the right people quickly, and generally keeping it outside your estate for inheritance tax purposes. A trustee can also be one of the beneficiaries. For example, it's common for a spouse to be both a trustee and a beneficiary.
Being your own beneficiary
If your policy includes terminal illness or critical illness cover, you may be able to receive a payout while you're still alive, provided you meet the policy's conditions.
Payouts don't happen automatically; someone has to make a claim. In practice, it's usually the executor of the estate, the policy's trustees, or a family member who notifies the insurer that the policyholder has died. Insurers don't seek out beneficiaries themselves, so it's important that the people involved know the policy exists and who the insurer is.
Where the policy is written in trust, the trustees can claim directly from the insurer and pass the money on to the beneficiaries, often within a few weeks. Where the policy isn't in trust, the payout goes into the estate, and the executor may need to obtain probate before the money can be distributed, which can take several months.
To make a claim, the insurer will normally need a death certificate and a completed claim form, and may ask for further information.
Beneficiaries who live outside the UK can usually still receive a payout, though policy terms, local tax rules, and access to a suitable bank account may affect how straightforward this is.
Do beneficiaries pay tax?
There's no income tax or capital gains tax to pay on a life insurance payout itself.
Inheritance tax is where it gets more nuanced. If the proceeds form part of your estate, they count towards its total value. Inheritance tax is charged at 40% on the value of your estate above the tax-free threshold (the "nil-rate band"), which is currently £325,000. A few important points to keep in mind:
- Anything you leave to a spouse or civil partner is normally free of inheritance tax, regardless of value.
- There's an additional "residence nil-rate band" (up to £175,000) if you pass your home to your children or grandchildren, which can raise the effective threshold.
- The 40% rate applies only to the portion of the estate above the threshold, not to the whole amount.
Writing your policy in trust generally keeps the payout outside your estate, so it isn't counted for inheritance tax, which is one of the main reasons trusts are so widely used. As tax rules can be complex and depend on your circumstances, it's worth speaking to a financial adviser about your own situation.
Wills and life insurance do different jobs, and it's a good idea to have both. Someone can be a life insurance beneficiary without being named in your will, and vice versa. Your will deals with the distribution of your entire estate, while your life insurance, especially if written in trust, directs a specific payout to specific people. Keeping the two aligned helps avoid confusion and makes sure your wishes are carried out.
Who should your life insurance beneficiary be?
Frequently asked questions
Fact-checked and reviewed by Kiruba Shankar Eswaran or another licensed agent on our team. Read our editorial standards.
This guide is for general educational purposes and is not financial advice. Cover, eligibility and terms vary by insurer and by policy. Always read the policy documents for the full terms, limitations and exclusions before you buy.
Related resources
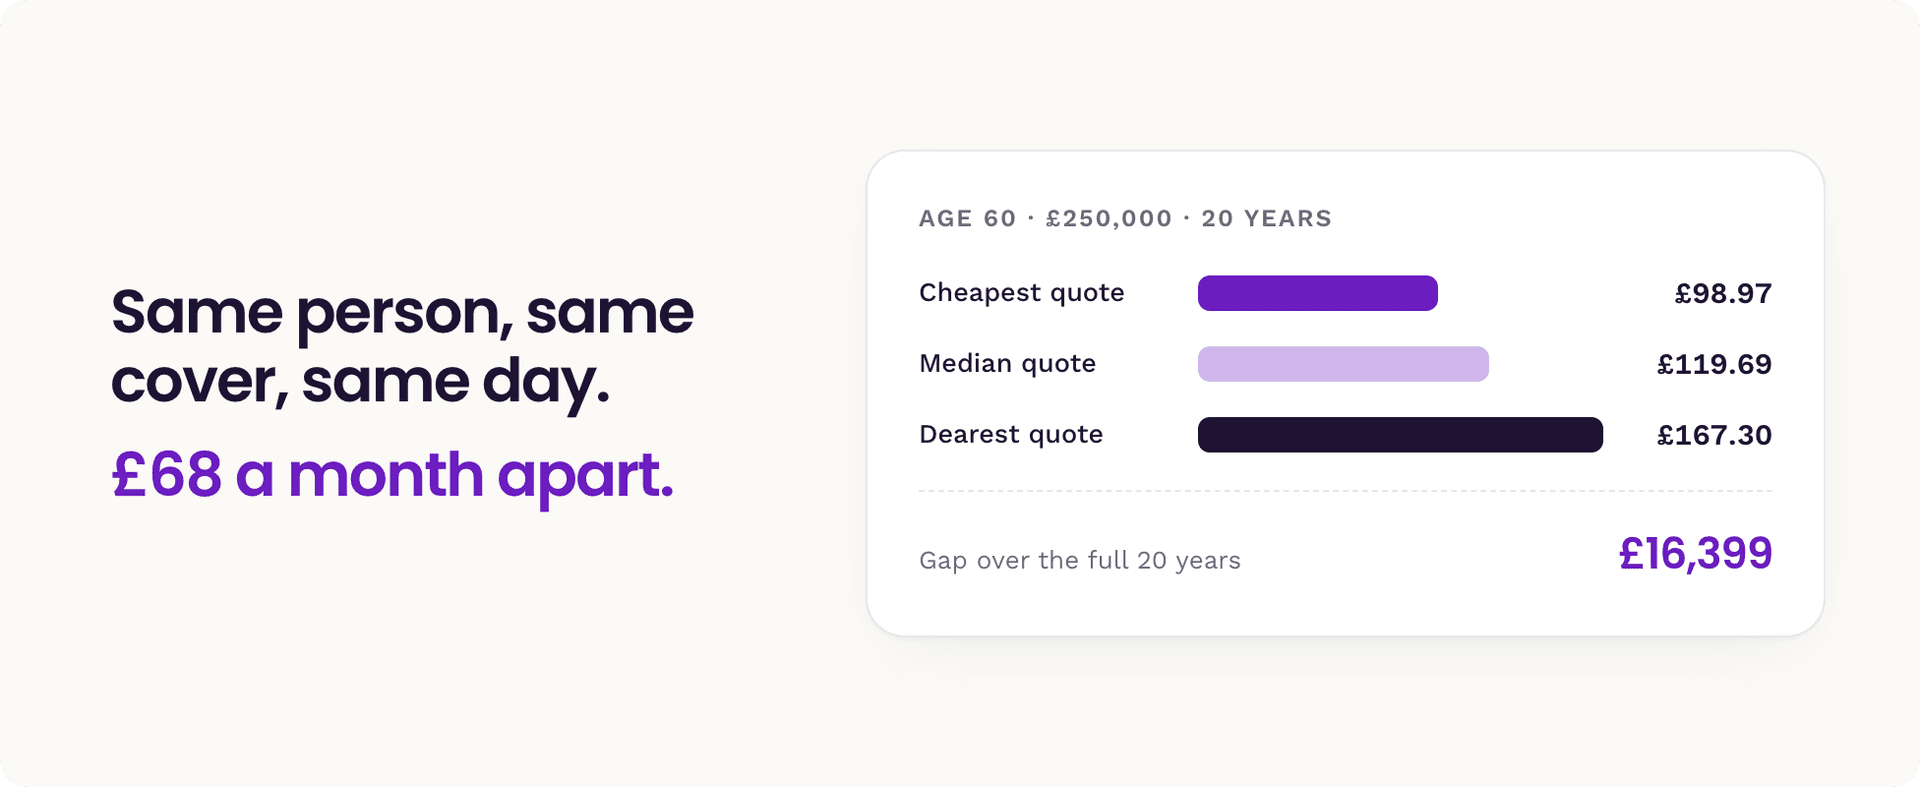
Life insurance cost UK 2026: what 6,557 real insurer quotes show
We collected 6,557 live quotes from UK life insurers in September 2026 and compared every one. Median prices by age, cover amount and policy length, how much smoking multiplies your premium, why bigger policies cost less per pound, and how mortgage protection compares with level cover.
What Is Term Life Insurance? UK Guide & Quotes (2026)
A complete UK guide to term life insurance: how it works, what it costs, the main policy types, underwriting, how it compares with whole of life, and the top UK providers.
6 Financial Resilience Tips for 2026
New Year, new money mindset. It’s time to break free from financial anxiety once and for all. Here are six simple tips to boost your financial resilience in 2026 and bring you peace of mind all year long!
Life Insurance for Young Adults
Life insurance for young adults doesn't have to be complicated or costly. This comprehensive guide covers why purchasing life insurance as a young adult locks in lower rates based on current health and how to pick the proper policy length and provider for your situation.
Turning Customer Curiosity Into Confidence: Theea's Coverage Calculator
Introducing Theea's Coverage Calculator: the intuitive insurance tool inspired by thousands of customer conversations that turns anxiety into tailored advice and confusion into confident choices.
Meet Your Newest Eleos Perks
We’re expanding our perks with two new additions designed to turn good intentions into healthy habits. Discover everything you can get for free with an Eleos policy.