Income Protection by Occupation: Is Your Job Covered? (UK 2027 Guide)

Short answer: most jobs in the UK can get income protection, but your job affects the price, how long cover can last and how soon it can start paying. A few jobs, such as police officers, armed forces personnel and rig workers, are hard to cover with a standard policy. Insurers also disagree, so one decline doesn't mean no insurer will cover you.
Whatever your job, Eleos will almost always have an option for you. We offer short-term accident and sickness cover across all occupations, and long-term income protection through our insurance partners. Unemployment cover is available for selected occupations. Some very high-risk jobs can be declined, but that's rare, so even if your job is hard to place for long-term cover, short-term cover with us is still likely to be open to you.
There's no single official list. Each insurer rates jobs in its own way, and the same job title can get a different answer from each one. We reviewed insurer occupation guidance and turned it into one plain-English table of 277 common UK jobs.
How to find your job: use the contents list to jump to your sector, or use Find on page (Ctrl+F, or "Find in page" on your phone) and type your job title. If it isn't listed, see what to do.
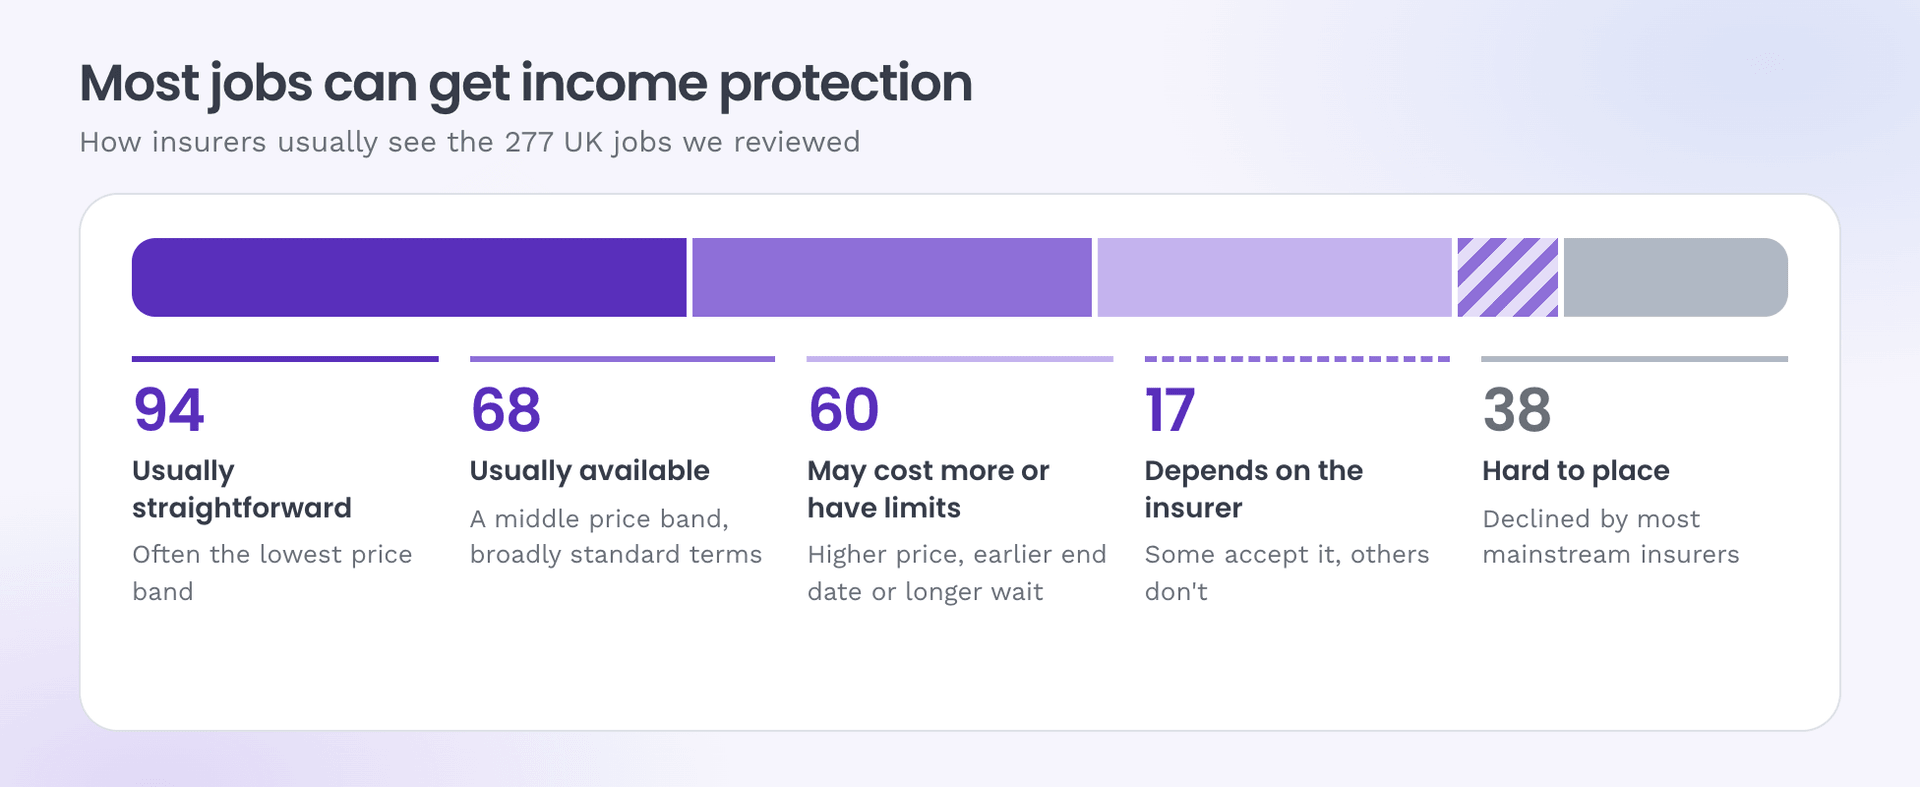
What the bands mean
| Band | What it usually means |
|---|---|
| Usually straightforward | Often the lowest price band, with a full choice of waiting periods |
| Usually available | Normally a middle price band, on broadly standard terms |
| May cost more or have limits | Higher premiums, or limits such as an earlier end date or a longer waiting period |
| Depends on the insurer | Some insurers accept this job and others don't, so the choice of insurer matters |
| Hard to place | Long-term cover is declined by most mainstream insurers we reviewed, but Eleos short-term cover is usually still an option |
These bands show how insurers tend to treat a job for long-term income protection. They don't apply to Eleos short-term accident and sickness cover, which is offered across all occupations, with only rare declines for very high-risk jobs. They're a guide, not an offer. Your own result also depends on your duties, health, age and the policy you choose.
Insurers rarely publish the reason behind each decision. The "Why" column is our own reading of the risks that usually drive it, so your insurer's reason may differ.
Why does your job affect income protection?
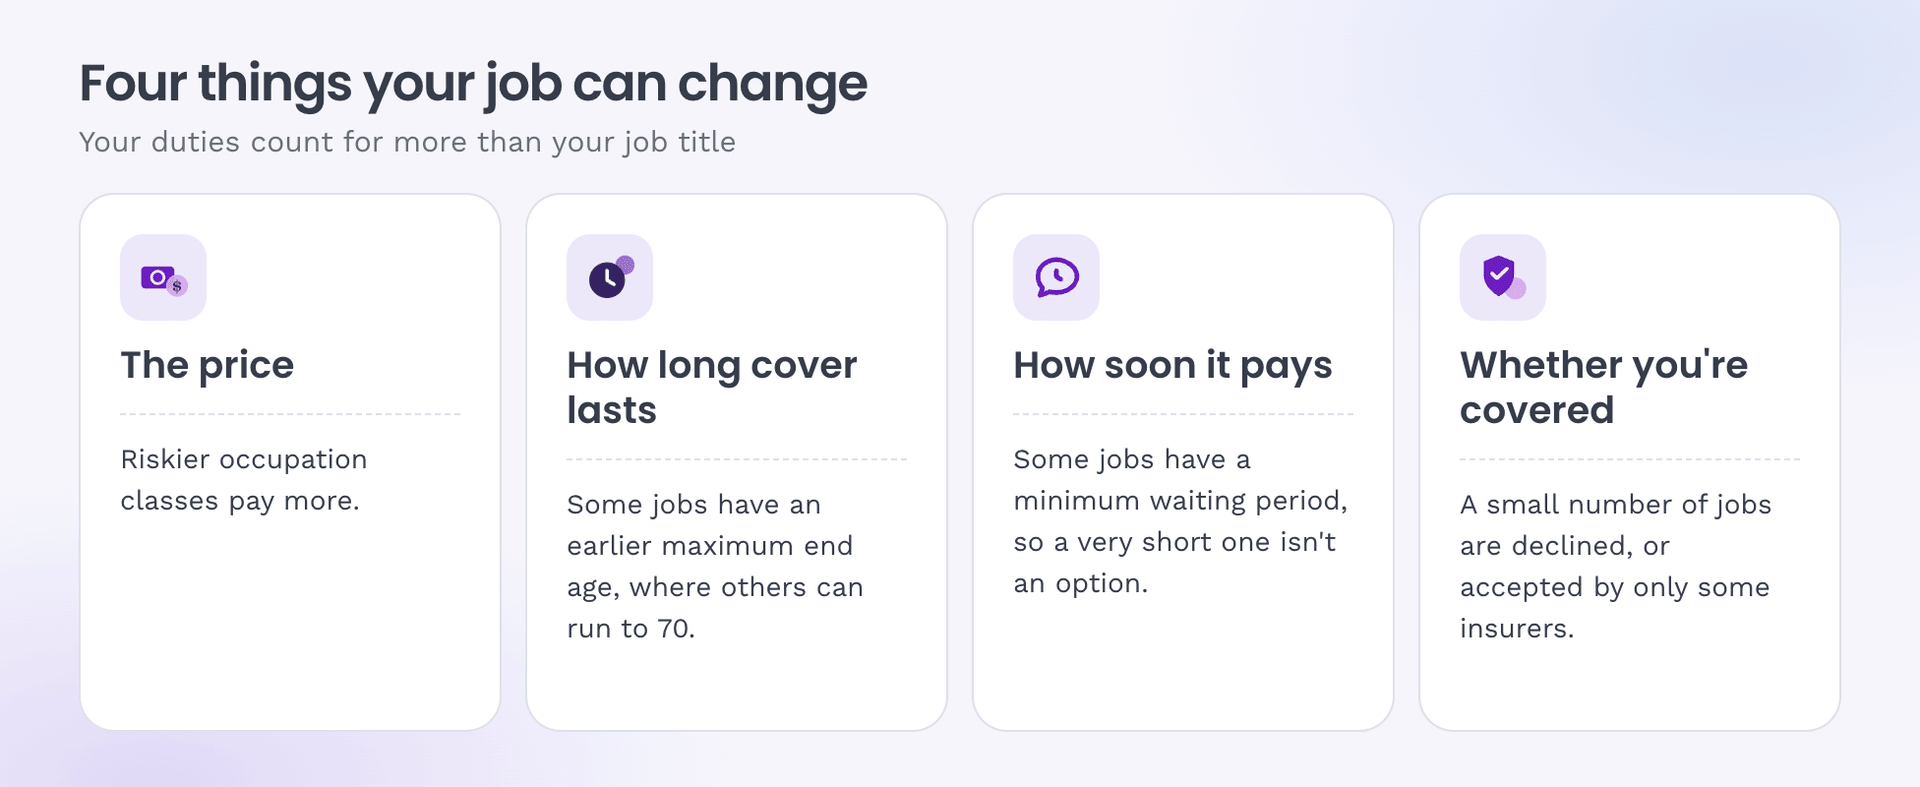
Income protection pays out when you can't work, so the insurer needs to know how likely that is in your line of work. A job that's physically demanding or dangerous is more likely to lead to a claim. Your job can affect four things:
- The price. Insurers group jobs into occupation classes, and riskier classes pay more. What income protection costs depends on this as well as your age and health.
- How long cover can last. Some jobs have an earlier maximum end age, even where others can run to 70.
- How soon it can pay. Some jobs have a minimum waiting period, so you can't choose a very short one.
- Whether you can get cover at all. A small number of jobs are declined, or are only accepted by some insurers.
Your duties count for more than your job title. Two people called "engineer" can be rated very differently if one works at a desk and the other climbs ladders, so describe what you actually do.
What does own occupation mean?
Own occupation means the policy pays if you can't do your own job. It's the strongest type of cover because you don't have to be unable to do every job, only yours. The main policies we reviewed use an own-occupation test for most working people.
Check this before you buy, because the test can be stricter in some situations. Both of the main guides we reviewed treat people working fewer than 16 hours a week differently, for example. Our guide to what income protection covers explains more, and our guide to choosing the right policy can help you compare.
Income protection for office, finance, legal and tech jobs
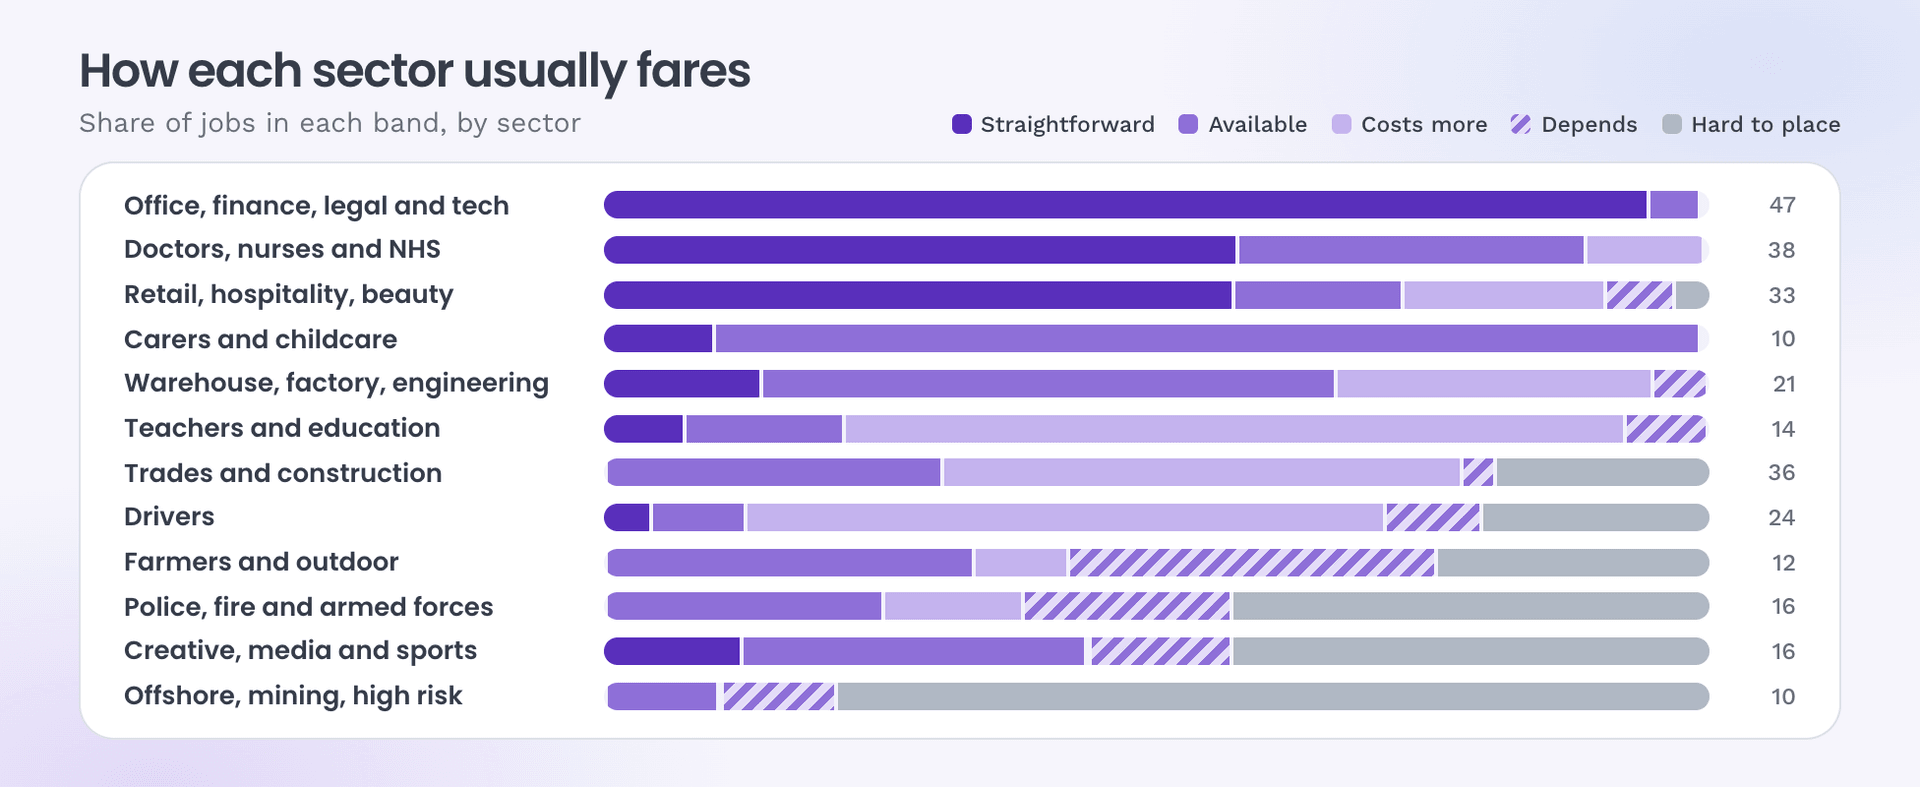
Desk-based jobs are usually the easiest to cover and the cheapest. If most of your day is office work, you can normally expect a full choice of waiting periods and cover that can run to a later age. The answer can shift if your job also involves regular site visits or overseas travel.
| Job | How insurers usually see it | Why |
|---|---|---|
| Accountant | Usually straightforward | |
| Accounts Assistant | Usually straightforward | |
| Actuary | Usually straightforward | |
| Administrator | Usually straightforward | |
| Architect | Usually straightforward | Regular site work can change this |
| Barrister | Usually straightforward | |
| Bookkeeper | Usually straightforward | |
| Business Analyst | Usually straightforward | |
| Call Centre Worker | Usually straightforward | |
| Chartered Surveyor | Usually straightforward | Regular site work can change this |
| Civil Servant | Usually straightforward | |
| Company Director | Usually straightforward | Based on office duties; hands-on work is rated on what you do |
| Compliance Officer | Usually straightforward | |
| Customer Service Adviser | Usually straightforward | |
| Data Analyst | Usually straightforward | |
| Data Scientist | Usually straightforward | |
| Economist | Usually straightforward | |
| Estate Agent | Usually straightforward | |
| Executive Assistant | Usually straightforward | |
| Finance Manager | Usually straightforward | |
| Financial Adviser | Usually straightforward | |
| HR Manager | Usually straightforward | |
| IT Support Technician | Usually straightforward | |
| Insurance Broker | Usually straightforward | |
| Journalist | Usually available | Some jobs involve travel to risky places, so overseas work may be asked about |
| Legal Secretary | Usually straightforward | |
| Lettings Agent | Usually straightforward | |
| Management Consultant | Usually straightforward | |
| Marketing Manager | Usually straightforward | |
| Mortgage Adviser | Usually straightforward | |
| Office Manager | Usually straightforward | |
| Office Worker | Usually straightforward | |
| Payroll Clerk | Usually straightforward | |
| Project Manager | Usually available | Often rated above desk jobs in case of site visits. Office-only work may do better |
| Quantity Surveyor | Usually straightforward | Regular site work can change this |
| Receptionist | Usually straightforward | |
| Recruitment Consultant | Usually straightforward | |
| Sales Manager | Usually straightforward | |
| Sales Representative | Usually straightforward | |
| Secretary | Usually straightforward | |
| Software Developer | Usually straightforward | |
| Software Engineer | Usually straightforward | |
| Solicitor | Usually straightforward | |
| Tax Adviser | Usually straightforward | |
| Town Planner | Usually straightforward | |
| UX Designer | Usually straightforward | |
| Web Developer | Usually straightforward |
Income protection for doctors, nurses and NHS staff
Doctors, nurses and most other healthcare professionals can usually get income protection. Doctors who don't operate tend to sit in a lower price band than surgeons, dentists and nurses. If you work for the NHS, your waiting period matters more than your job title, because it needs to fit around your sick pay. We cover this in more detail in our guides to income protection for doctors and income protection for nurses.
| Job | How insurers usually see it | Why |
|---|---|---|
| Ambulance Technician | May cost more or have limits | Lifting, emergency driving and physical risk. Driving duties usually bring the limits. Cover may end earlier, with a longer minimum waiting period |
| Anaesthetist | Usually available | Hands-on clinical work with long, high-pressure shifts |
| Biomedical Scientist | Usually straightforward | |
| Chiropractor | Usually straightforward | |
| Counsellor | Usually straightforward | |
| Dental Hygienist | Usually available | Relies on fine hand skills, and neck and back strain is common |
| Dental Nurse | Usually available | Hands-on clinical work and time on your feet |
| Dentist | May cost more or have limits | Relies on fine hand skills, and neck and back strain is common. Cover may end earlier |
| Dietitian | Usually straightforward | |
| District Nurse | Usually available | Lifting patients plus time on the road. NHS staff: your waiting period may be tied to your sick pay |
| Doctor | Usually straightforward | Surgical work can move you up a band. NHS staff: your waiting period may be tied to your sick pay |
| GP | Usually straightforward | Check how your waiting period fits your practice sick pay |
| Health Visitor | Usually straightforward | |
| Healthcare Assistant | Usually available | Lifting and moving patients every day |
| Hospital Consultant | Usually straightforward | Surgical work can move you up a band. NHS staff: your waiting period may be tied to your sick pay |
| Hospital Porter | Usually available | Regular lifting and moving |
| Junior Doctor | Usually straightforward | NHS staff: your waiting period may be tied to your sick pay |
| Laboratory Technician | Usually straightforward | |
| Mental Health Nurse | Usually available | Work stress and some risk of violence. NHS staff: your waiting period may be tied to your sick pay |
| Midwife | Usually available | Physical work, long shifts and night work. NHS staff: your waiting period may be tied to your sick pay |
| Nurse | Usually available | Lifting patients, shifts and work stress. NHS staff: your waiting period may be tied to your sick pay |
| Nurse Practitioner | Usually available | Hands-on patient care and shifts. NHS staff: your waiting period may be tied to your sick pay |
| Occupational Therapist | Usually straightforward | |
| Optometrist | Usually straightforward | |
| Orthodontist | May cost more or have limits | Relies on fine hand skills, and neck and back strain is common. Cover may end earlier |
| Osteopath | Usually straightforward | |
| Paramedic | May cost more or have limits | Lifting, emergency driving and physical risk. Driving duties usually bring the limits. Cover may end earlier, with a longer minimum waiting period |
| Pharmacist | Usually straightforward | |
| Pharmacy Technician | Usually straightforward | |
| Physiotherapist | Usually available | Physical, hands-on work with patients |
| Podiatrist | Usually straightforward | |
| Psychiatrist | Usually straightforward | |
| Psychologist | Usually straightforward | |
| Radiographer | Usually straightforward | |
| Speech and Language Therapist | Usually straightforward | |
| Surgeon | Usually available | A small hand injury can stop you operating. NHS staff: your waiting period may be tied to your sick pay |
| Veterinary Nurse | Usually straightforward | |
| Veterinary Surgeon | Usually straightforward |
Income protection for carers, social workers and childcare jobs
Care work and social work are usually accepted, normally in a middle price band. The physical side of care work and time spent on the road are what move these jobs out of the lowest band.
| Job | How insurers usually see it | Why |
|---|---|---|
| Care Home Manager | Usually available | Often includes hands-on care. Admin-only work may do better |
| Care Worker | Usually available | Lifting and moving people, plus shift work |
| Charity Worker | Usually straightforward | |
| Childminder | Usually available | Active, physical work, and hard to keep going if you're unwell |
| Home Carer | Usually available | Lifting and moving people, plus driving between visits |
| Nanny | Usually available | Active, physical work with young children |
| Nursery Worker | Usually available | Active, physical work with young children |
| Social Worker | Usually available | High work stress and some risk from difficult situations |
| Support Worker | Usually available | Physical care work and some risk of injury |
| Youth Worker | Usually available | Active work, with some risk from difficult situations |
Income protection for teachers and education staff
Teachers can usually get income protection, but some insurers end cover earlier than they would for an office job. That makes the end date worth checking before you buy. Our guide to income protection for teachers explains how it fits around teachers' sick pay.
| Job | How insurers usually see it | Why |
|---|---|---|
| Dance Teacher | Depends on the insurer | Physical work with a high risk of injury. Some insurers decline it. Cover may end much earlier than usual |
| Driving Instructor | May cost more or have limits | Time on the road, and you need to stay fit to drive. Cover may end earlier, with a longer minimum waiting period |
| Headteacher | May cost more or have limits | Stress-related absence is a known risk. Cover may end earlier |
| Librarian | Usually straightforward | |
| Music Teacher | May cost more or have limits | Grouped with teaching, and income can vary. Cover may end earlier |
| PE Teacher | May cost more or have limits | Physical job that's harder to keep doing as you get older. Cover may end earlier |
| Primary School Teacher | May cost more or have limits | Stress-related absence is a known risk. Cover may end earlier |
| Private Tutor | Usually available | Grouped with teaching, and income can vary |
| School Caretaker | Usually available | Manual work and some work at height |
| Secondary School Teacher | May cost more or have limits | Stress-related absence is a known risk. Cover may end earlier |
| Supply Teacher | May cost more or have limits | Stress-related absence, and income can vary. Cover may end earlier |
| Teacher | May cost more or have limits | Stress-related absence is a known risk. Cover may end earlier |
| Teaching Assistant | May cost more or have limits | Stress and active classroom work. Cover may end earlier |
| University Lecturer | May cost more or have limits | Grouped with teaching, where stress is a known risk. Cover may end earlier |
Income protection for electricians, plumbers, builders and trades
Most trades can get income protection, though you'll usually pay more than an office worker. Electricians, plumbers and gas engineers tend to sit in a middle band, while building trades sit higher. How much manual work you do and whether you work at height are the two things that matter most. General labouring, demolition and groundwork are much harder to place for long-term cover, but Eleos short-term accident and sickness cover is usually still an option.
| Job | How insurers usually see it | Why |
|---|---|---|
| Air Conditioning Engineer | Usually available | Manual work, often at height |
| Bricklayer | May cost more or have limits | Heavy lifting and work on scaffolding |
| Builder | May cost more or have limits | Heavy manual work and site risks. No manual work can mean a much lower band |
| Carpenter | May cost more or have limits | Manual work with power tools and some height |
| Construction Manager | Usually available | Time on site, even when you're not doing manual work |
| Crane Operator | Hard to place | Heavy machinery, height and strict fitness needs |
| Damp Proofer | May cost more or have limits | Manual work with chemicals |
| Demolition Worker | Hard to place | High risk of serious injury |
| Digger Driver | Hard to place | Heavy machinery on site |
| Electrician | Usually available | Manual work, with some risk from height and electricity. Offshore work is treated very differently |
| Fencer | May cost more or have limits | Heavy outdoor manual work |
| Floor Layer | May cost more or have limits | Hard on your knees and back |
| Gardener | Usually available | Outdoor manual work with tools |
| Gas Engineer | Usually available | Manual work with some risk from gas |
| Glazier | May cost more or have limits | Heavy lifting, glass and some height |
| Groundworker | Hard to place | Heavy manual work around plant and excavations |
| Handyman | Hard to place | Varied duties are hard to rate, and may include height |
| Heating Engineer | Usually available | Manual work in awkward spaces |
| Joiner | May cost more or have limits | Manual work with power tools and machinery |
| Kitchen Fitter | May cost more or have limits | Heavy lifting and power tools |
| Labourer | Hard to place | Heavy manual work with varied, undefined duties |
| Landscaper | Usually available | Outdoor manual work with machinery |
| Lift Engineer | Usually available | Manual work in lift shafts and around machinery |
| Locksmith | Usually available | Manual work and time on the road |
| Painter and Decorator | May cost more or have limits | Ladder work. Exterior work at height can change this |
| Plasterer | May cost more or have limits | Repetitive strain on your shoulders and back |
| Plumber | Usually available | Manual work in awkward spaces |
| Roofer | May cost more or have limits | Risk of falls. Working height can decide this |
| Scaffolder | May cost more or have limits | Heavy lifting and constant work at height |
| Site Manager | Usually available | Time on site. Regular manual work can change this |
| Steel Erector | Hard to place | High risk of falls, even at lower heights |
| Stonemason | May cost more or have limits | Heavy lifting, dust and power tools |
| Tiler | May cost more or have limits | Hard on your knees and back. Work at height can change this |
| Tree Surgeon | Depends on the insurer | Chainsaws and work at height. Some insurers decline it |
| Welder | May cost more or have limits | Burns, fumes and heavy manual work |
| Window Cleaner | May cost more or have limits | Risk of falls. Working height can decide this |
Income protection for HGV, taxi, delivery and other drivers
Professional drivers can usually get cover, but it often comes with limits. Some insurers end the policy earlier and won't let you choose a short waiting period. Bike and motorcycle couriers are much harder to cover, and so are pilots and merchant seafarers.
| Job | How insurers usually see it | Why |
|---|---|---|
| Air Traffic Controller | Usually straightforward | |
| Airline Pilot | Hard to place | Failing a flight medical can end your ability to work |
| Bus Driver | May cost more or have limits | You need a medical standard to keep your licence. Cover may end earlier, with a longer minimum waiting period |
| Chauffeur | May cost more or have limits | Long hours on the road, and you need to stay fit to drive. Cover may end earlier, with a longer minimum waiting period |
| Coach Driver | May cost more or have limits | You need a medical standard to keep your licence. Cover may end earlier, with a longer minimum waiting period |
| Courier | Depends on the insurer | Road risk and uneven income. Some insurers decline it. Bike and motorcycle work is much harder to cover |
| Delivery Driver | May cost more or have limits | Long hours on the road and lifting. Bike or scooter delivery is much harder to cover. Cover may end earlier, with a longer minimum waiting period |
| Dock Worker | Hard to place | Heavy lifting around machinery and cargo |
| Flight Attendant | Depends on the insurer | Time in the air and physical cabin work. Some insurers exclude flight crew. Cover may end much earlier than usual |
| Forklift Driver | May cost more or have limits | Machinery and warehouse risks. Cover may end earlier, with a longer minimum waiting period |
| HGV Driver | May cost more or have limits | A health problem can cost you your licence, and loading adds injury risk. Cover may end earlier, with a longer minimum waiting period |
| Lorry Driver | May cost more or have limits | A health problem can cost you your licence, and loading adds injury risk. Cover may end earlier, with a longer minimum waiting period |
| Motorcycle Courier | Hard to place | High risk of road injury |
| Postal Worker | May cost more or have limits | Lifting and walking, plus time on the road. Cover may end earlier, with a longer minimum waiting period |
| Private Hire Driver | May cost more or have limits | Usually treated as a taxi driver, so licence and road risks apply. Cover may end earlier, with a longer minimum waiting period |
| Railway Engineer | Usually available | Manual work near live track |
| Refuse Collector | Hard to place | Heavy lifting next to moving vehicles |
| Ship's Officer | Hard to place | Long periods at sea, far from medical care |
| Taxi Driver | May cost more or have limits | You need a medical standard to keep your licence, and face road risk. Cover may end earlier, with a longer minimum waiting period |
| Train Driver | May cost more or have limits | You need to meet strict medical standards to keep driving. Cover may end earlier, with a longer minimum waiting period |
| Train Guard | Usually available | Time on your feet, shifts and some risk from the public |
| Tram Driver | May cost more or have limits | You need to meet medical standards to keep driving. Cover may end earlier, with a longer minimum waiting period |
| Uber Driver | May cost more or have limits | Usually treated as a taxi driver, so licence and road risks apply. Cover may end earlier, with a longer minimum waiting period |
| Van Driver | May cost more or have limits | Long hours on the road, often with lifting. Cover may end earlier, with a longer minimum waiting period |
Income protection for police, firefighters and armed forces
This is where mainstream cover is hardest to find. Police officers and armed forces personnel are declined by most mainstream income protection policies, so workplace schemes and specialist routes are the realistic options. Firefighters show why one decline isn't the market's answer: insurers in the guides we reviewed gave different answers for the same job. For most jobs here, Eleos short-term accident and sickness cover is still an option.
| Job | How insurers usually see it | Why |
|---|---|---|
| Army Reservist | Hard to place | You can be called up. Reserve roles are often excluded |
| Bailiff | Depends on the insurer | Risk of confrontation. Some insurers decline it |
| Coastguard | Usually available | Rescue work can bring physical risk. Office-based work can do better |
| Door Supervisor | Hard to place | Risk of violence. Some insurers accept it only as a second job, with an exclusion |
| Firefighter | Depends on the insurer | Physical danger on duty. Some insurers decline it and others accept it |
| Lifeguard | May cost more or have limits | A physical job that's harder to keep doing as you get older. Cover may end much earlier than usual |
| PCSO | Hard to place | Risk of confrontation on patrol. Ask about group or specialist options |
| Police Officer | Hard to place | Physical danger on duty. Ask about group or specialist options |
| Prison Officer | Usually available | Risk of violence, and work stress |
| Private Investigator | Usually available | Time on the road and some risk of confrontation |
| RAF | Hard to place | Risk of injury in service. Ask about group or specialist options |
| Retained Firefighter | Depends on the insurer | Physical danger on call. At least one insurer accepts this as a second job |
| Royal Navy | Hard to place | Risk of injury in service. Ask about group or specialist options |
| Security Guard | May cost more or have limits | Risk of confrontation. Often premises work only. Cover may end earlier |
| Soldier (British Army) | Hard to place | Risk of injury in service. Ask about group or specialist options |
| Traffic Warden | Usually available | Outdoor work with some risk of confrontation |
Income protection for retail, hospitality, beauty and fitness jobs
Shop, catering and salon work is usually straightforward, often in a lower price band than people expect. Pub work and fitness jobs are the main exceptions, and some insurers end cover early for fitness instructors. Cleaners get very different answers depending on the insurer and the exact job title.
| Job | How insurers usually see it | Why |
|---|---|---|
| Baker | Usually straightforward | |
| Bar Staff | May cost more or have limits | Late nights and some risk from customers. Full-time pub work may need individual review |
| Barber | Usually straightforward | |
| Barista | Usually straightforward | |
| Beautician | Usually straightforward | |
| Butcher | May cost more or have limits | Knives and heavy lifting |
| Cashier | Usually straightforward | |
| Chef | Usually straightforward | |
| Cleaner | Depends on the insurer | Physical work and chemicals. Your exact title matters: domestic, commercial or industrial |
| Cook | Usually straightforward | |
| Dog Groomer | Usually available | Physical work with some risk from animals |
| Florist | Usually straightforward | |
| Funeral Director | Usually straightforward | |
| Gym Instructor | May cost more or have limits | A physical job that's harder to keep doing as you get older. Cover may end much earlier than usual |
| Hairdresser | Usually straightforward | |
| Hotel Manager | Usually straightforward | |
| Hotel Receptionist | Usually straightforward | |
| Housekeeper | Usually available | Physical work with repetitive strain |
| Kitchen Porter | Usually straightforward | |
| Launderette Worker | Usually available | Physical work with machinery and heat |
| Market Trader | Hard to place | Income is hard to verify, with outdoor manual work |
| Massage Therapist | Usually available | Repetitive strain on your hands and arms |
| Nail Technician | Usually straightforward | |
| Office Cleaner | Depends on the insurer | Physical work and chemicals. Your exact title matters: domestic, commercial or industrial |
| Personal Trainer | May cost more or have limits | A physical job that's harder to keep doing as you get older. Cover may end much earlier than usual |
| Pub Landlord | May cost more or have limits | Late nights and physical work. Full-time pub work may need individual review |
| Retail Manager | Usually straightforward | |
| Shop Assistant | Usually straightforward | |
| Supermarket Worker | Usually straightforward | |
| Takeaway Worker | Usually straightforward | |
| Tattoo Artist | Usually available | Relies on your hands, and income can vary |
| Waiter | Usually straightforward | |
| Yoga Instructor | May cost more or have limits | A physical job that's harder to keep doing as you get older. Cover may end much earlier than usual |
Income protection for warehouse, factory and engineering jobs
Most of these jobs can be covered, and the price depends on how hands-on the work is. Engineers and technicians tend to sit in a middle band. Warehouse, factory and heavier metalwork roles usually sit higher, while managers with no manual work can sit much lower.
| Job | How insurers usually see it | Why |
|---|---|---|
| Aerospace Engineer | Usually available | Depends on how hands-on you are. Desk-based work may do better |
| Blacksmith | May cost more or have limits | Heavy manual work with heat |
| Car Salesperson | Usually straightforward | |
| Car Valeter | Usually available | Physical work and chemicals |
| Chemical Engineer | Usually available | Time on plant sites. Offshore work is treated differently |
| Civil Engineer | Usually straightforward | |
| Electrical Engineer | Usually available | Depends on how hands-on you are. Desk-based work may do better |
| Factory Worker | May cost more or have limits | Machinery and repetitive manual work |
| Machinist | May cost more or have limits | Work around cutting machinery |
| Maintenance Engineer | Usually available | Hands-on work around machinery |
| Mechanic | Usually available | Manual work with heavy parts and tools |
| Mechanical Engineer | Usually available | Depends on how hands-on you are. Desk-based work may do better |
| Panel Beater | May cost more or have limits | Heavy manual work, noise and fumes |
| Printer | Usually available | Work around machinery |
| Production Manager | Usually available | Time on the factory floor. No manual work can do better |
| Quality Inspector | Usually available | Time on the factory floor |
| Sheet Metal Worker | Depends on the insurer | Heavy manual work with sharp materials. Some insurers decline it |
| Tyre Fitter | May cost more or have limits | Heavy lifting and repetitive strain |
| Vehicle Technician | Usually available | Manual work with heavy parts and tools |
| Warehouse Manager | Usually straightforward | |
| Warehouse Operative | May cost more or have limits | Heavy lifting and machinery |
Income protection for farmers and outdoor jobs
Farmers can usually get income protection, but farm workers may not get the same answer. Owning a farm and working on one can be rated differently. Fishing and professional horse riding are among the hardest jobs to cover.
| Job | How insurers usually see it | Why |
|---|---|---|
| Abattoir Worker | Depends on the insurer | Knives, machinery and heavy work. Some insurers decline it |
| Dog Walker | Usually available | Outdoor work, and income can vary |
| Farm Worker | Depends on the insurer | Machinery and livestock, often with varied duties. Some insurers decline it |
| Farmer | Usually available | Machinery, livestock and lone working. Owning a farm and working on one can be rated differently |
| Fisherman | Hard to place | Dangerous work at sea, and income varies. Inshore work may be considered individually |
| Forester | Depends on the insurer | Chainsaws and heavy outdoor work. Some insurers decline it |
| Gamekeeper | Usually available | Outdoor work with firearms and machinery |
| Groom (horses) | Depends on the insurer | Risk of injury from horses. Some insurers exclude certain equestrian jobs |
| Jockey | Hard to place | High risk of falls and serious injury |
| Riding Instructor | Hard to place | Risk of falls and injury from horses |
| Shepherd | Usually available | Outdoor work with livestock |
| Zookeeper | May cost more or have limits | Physical work with some risk from animals |
Income protection for creative, media and sports jobs
Creative jobs split into two groups. Studio and desk-based work such as graphic design is usually fine. Performers, including actors, musicians, singers and dancers, are often unavailable from mainstream insurers, and so are professional sportspeople. Some insurers also treat writers and freelance artists as unavailable, so check before you assume. If long-term cover isn't available, Eleos short-term accident and sickness cover is usually still an option.
| Job | How insurers usually see it | Why |
|---|---|---|
| Actor | Hard to place | Irregular income that's hard to verify |
| Artist | Depends on the insurer | Irregular income that's hard to verify. Some insurers decline it |
| Clergy | Usually straightforward | |
| Dancer | Hard to place | Short physical career with a high risk of injury |
| Fashion Designer | Usually available | Often hands-on studio work, and income can vary |
| Film Director | Usually available | Irregular work and time on location |
| Graphic Designer | Usually straightforward | |
| Interior Designer | Usually available | Income can vary, and site visits may be involved |
| Musician | Hard to place | Irregular income, and a small injury can stop you performing |
| Photographer | Usually available | Income can vary, and some work involves travel |
| Professional Footballer | Hard to place | Injury is a known risk of the job, and careers are short |
| Professional Sportsperson | Hard to place | Injury is a known risk of the job, and careers are short |
| Singer | Hard to place | Irregular income, and a voice problem can stop you performing |
| Stunt Performer | Hard to place | Very high risk of serious injury |
| Television Presenter | Usually available | Irregular work and time on location |
| Writer | Depends on the insurer | Irregular income that's hard to verify. Some insurers decline it |
Income protection for offshore, mining and high-risk jobs
Most rig-based, underground and diving work can't be covered by a standard income protection policy. Some offshore support and management roles can be, so your exact duties matter. If your job is on this list, you may still have an option. Eleos offers short-term accident and sickness cover across all occupations. The highest-risk jobs can be declined, but that's rare, and an adviser can check whether long-term cover is possible too. Our guide to high-risk jobs and life insurance covers the wider options.
| Job | How insurers usually see it | Why |
|---|---|---|
| Asbestos Remover | Hard to place | Long-term lung disease risk |
| Diver | Hard to place | Dangerous work with long-term health risks |
| Explosives Worker | Hard to place | Very high risk of serious injury |
| Nuclear Power Worker | Usually available | Work in a controlled, safety-critical environment |
| Offshore Electrician | Hard to place | Dangerous work, far from medical care |
| Offshore Worker (rig-based) | Hard to place | Dangerous work, far from medical care |
| Oil Rig Worker | Hard to place | Dangerous work, far from medical care |
| Quarry Worker | Depends on the insurer | Heavy machinery and dust. Some insurers decline it |
| Steeplejack | Hard to place | Very high risk of falls |
| Underground Miner | Hard to place | Underground work with injury and long-term lung risks |
Income protection for self-employed people, contractors and directors
Being self-employed doesn't change your job's band. Insurers rate the work you do, so a self-employed electrician is treated like an employed one. What changes is how your income is worked out and how much you need, because you have no employer sick pay to fall back on.
See our guides to income protection for the self-employed, freelancers and gig workers and executive income protection for company directors. If your hours vary, read about income protection and zero-hours contracts.
What if your job isn't listed?
Find the closest job in the table and treat it as a rough guide, then give your insurer or adviser your real job title and duties. Insurers hold thousands of job titles, and the wording matters. Don't pick a safer-sounding title to get a better price. If your duties aren't described accurately, it could cause problems at claim time.
Not being on this list doesn't count against you. Eleos short-term accident and sickness cover is offered across all occupations, listed or not, with only rare declines for very high-risk jobs.
What if you have two jobs?
Tell the insurer about both. Some insurers look at each job and what you'd be able to do in each. A few roles that are hard to cover as a main job can be accepted as a second job. Retained firefighters and special constables are examples at one insurer we reviewed.
What to do if you're declined because of your job
A decline from one insurer isn't a decline from the market, and it rarely leaves you without an option at Eleos. Try these steps in order:
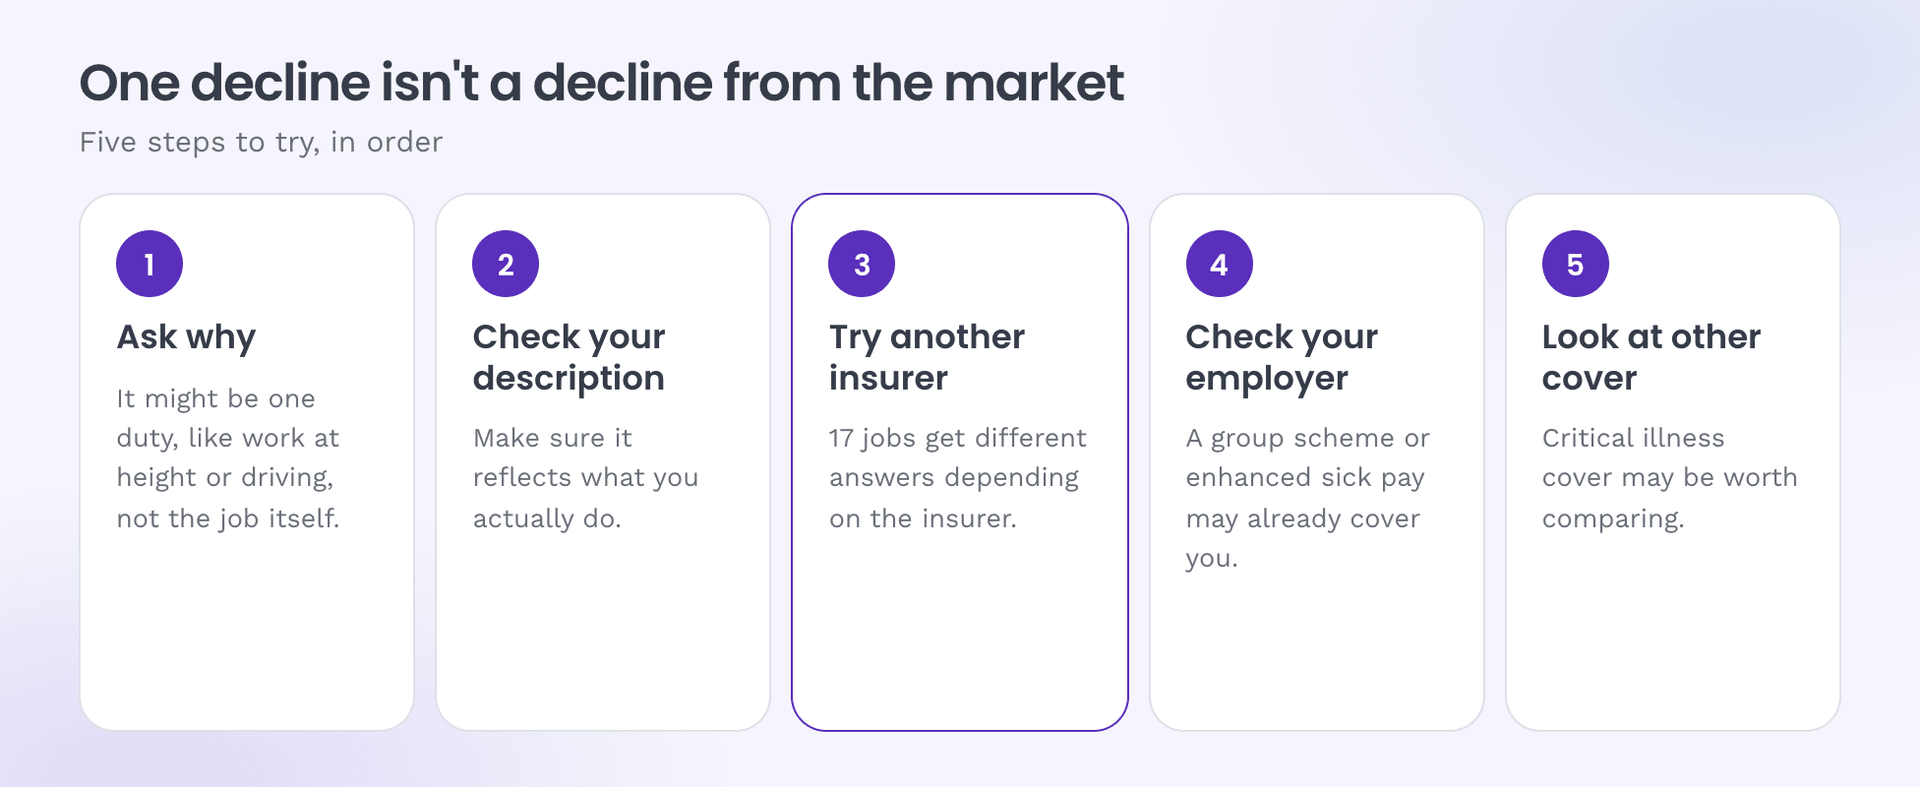
- Ask why. It might be one part of your job, such as work at height or a driving duty, and not the job itself.
- Check your description. Make sure the application reflects what you actually do.
- Try another insurer. As the "Depends on the insurer" rows show, answers really do differ.
- Look at short-term cover. Eleos offers accident and sickness cover across all occupations, so a job that's declined for long-term cover can usually still have protection.
- Check what your employer offers. A group income protection scheme or enhanced sick pay may already give you some cover.
- Look at other protection. If long-term income protection isn't available, critical illness cover may be worth comparing.
Frequently asked questions
What are income protection occupation classes? They're the groups insurers use to rate jobs by risk. Many insurers use classes numbered 1 to 4, where 1 is mainly office work and 4 is heavy manual work, and some use their own system. Classes aren't the same across insurers, which is why we use plain bands here.
Which jobs can't get income protection? Mainstream insurers commonly decline police officers, armed forces personnel, oil rig workers, divers, underground miners and professional sportspeople. Other jobs vary by insurer, so it's worth checking. That's for long-term cover. Eleos short-term accident and sickness cover is offered across all occupations, and declines for very high-risk jobs are rare.
Is there income protection for any job? At Eleos, almost always. We offer short-term accident and sickness cover across all occupations, and long-term income protection through our insurance partners. Unemployment cover is available for selected occupations. Some very high-risk jobs can be declined, but that's rare, and your health, age and other eligibility checks still apply.
Do I have to tell my insurer my exact job? Yes. Answer honestly and describe your real duties. An inaccurate answer could affect a claim later.
Is income protection more expensive for manual workers? Usually, yes. Manual work is more likely to lead to a claim, so these jobs normally sit in a higher price band. How much depends on your age, health, waiting period and the amount of cover. Our guide to how much income protection you need can help you set the right level.
Is income protection worth it if my job is low risk? Illness can stop anyone working, so an office job doesn't remove the need. Our guide on whether income protection is worth it looks at this in more detail.
Do I still need income protection if I get sick pay? It depends on how much you get and for how long. Statutory Sick Pay is low, and many employer schemes run out after a few months. Income protection can start when your sick pay ends, which also keeps the premium down.
Does having a health condition change the answer? It can. Your job is only one part of the assessment, and our guide to income protection with a pre-existing condition covers the health side.
Can Eleos help with income protection for your job?
Yes. Whatever you do for a living, there's almost always an option for you at Eleos:
- Short-term accident and sickness cover, across all occupations. Some very high-risk jobs can be declined, but that's rare. You can get an income protection quote from Eleos online, and the application generally doesn't involve a medical exam. Our guide on how to buy Eleos income protection walks you through it.
- Long-term income protection, through our insurance partners. An Eleos adviser can look at your job and find out which partner may cover you. The quickest way to reach us is by WhatsApp.
- Unemployment cover, for selected occupations. You can add this if your job qualifies.
Your job is rarely what stops you. Your health, age and other eligibility checks still apply, and we'll tell you clearly what you can get.
The bottom line
Most jobs can be covered. Your job shapes the price, the end date and the waiting period, and insurers don't all agree. Find your job above, describe your duties accurately, and don't take one decline as the final answer.
And remember, whatever your occupation, there's almost always an option for you at Eleos: short-term accident and sickness cover across all occupations, and long-term income protection through our insurance partners.
This guide explains how UK insurers generally treat occupations for income protection. It's based on insurer occupation guidance reviewed by Eleos in November 2026. Bands are our own simplified summary, and they're indicative only. Insurers change their rules without notice, and better or worse terms are both possible. Nothing here is an offer of cover, a quotation, a statement of the terms available to you, or financial advice. Always read your policy documents.
Fact-checked and reviewed by Kiruba Shankar Eswaran or another licensed agent on our team. Read our editorial standards.
This guide is for general educational purposes and is not financial advice. Cover, eligibility and terms vary by insurer and by policy. Always read the policy documents for the full terms, limitations and exclusions before you buy.
Related resources
Life Insurance Without a Medical: How Much Cover Can You Get? (2026 Guide)
Most applicants are not automatically asked for medical evidence. Under age 30, all five UK insurers reviewed for this guide will consider up to £1 million of life cover with no automatic medical evidence based on age and cover amount alone. The amount falls as you get older, and by 75 it can be as low as £25,000 at one insurer and £100,000 at another.
Insurance terms defined and explained
A dictionary of terms used in insurance
A step-by-step guide to buying Eleos income protection
If you like the sound of Eleos income protection insurance, here’s how to go about getting your policy
Income protection for private tenants
The government is planning changes to the landlord-tenant relationship, but until then how can tenants give themselves greater security?
How to protect my income: a guide
Most of us protect our valuable or precious assets, so doesn't it make sense to protect one of the most important: our income?