Life insurance for high risk occupations
Contents
It’s important to know the difference between high-risk insurance and high-risk occupation insurance. The first is for people who struggle to find standard life insurance because of health issues, medical history and hazardous pastimes as well as the nature of their work. The second, which we’re looking at here, is more narrowly focused on people with dangerous jobs.
If your job puts you at greater risk than the average person it can be difficult to get life insurance, or, if you do find it, the cost can be prohibitive. However, life insurance is just as important for you and your loved ones as it is for anyone else. In fact, because of the higher risk it can be even more important.
Fortunately, there are insurance companies who recognise this and have created policies for people in precisely this position.
Every insurer has its own definitions but as a general guide, these are some of the most common elements of an occupation that will qualify it as dangerous:
- Working outdoors at heights of over 40 feet (12 metres)
- Working on building sites
- High car mileage
- Underground or underwater work
- Working with chemicals or explosives
- Operating heavy machinery
- Working in dangerous locations such as conflict zones
- Military roles
Examples of high-risk jobs
Some jobs are by their nature clearly dangerous, but others are not so obvious. Here are some examples of both:
- Construction worker
- Firefighter
- Police officer
- HGV driver
- Pilot
- Soldier
- Offshore oil platform worker
- Large animal vet
Applying for life insurance for dangerous jobs isn’t really any different from taking out a standard policy. You’ll generally be asked the same questions to determine whether you’re eligible. An insurer will want to know your age, details about your current and past health, your family’s medical history, your hobbies and leisure pursuits, whether you smoke or drink and how much. So far so similar. When asked about your occupation, of course, it gets a little different.
Most life insurance applications will feature questions like ‘do you work at heights of over 15 metres?’ or ‘do you work with explosives?’ or ‘are you in the military?’ The majority of applicants will answer ‘no’ and those that answer ‘yes’ may be offered a policy that excludes cover for death that’s related to any of these job requirements. Dangerous occupations insurance will have none or very few of these exclusions, because that’s the whole point.
The high-risk cover of these policies will be reflected in the price. Your premiums will be higher – in some cases much higher – than for a standard life insurance policy. Insurers may take other issues into account, such as your age and the state of your general health when you apply. There may be a limit on the amount of cover you can buy and the length of the policy may be more limited, although some insurers will offer both term life and whole life policies. These are commercial decisions the insurer makes in order to strike a balance between the extent of the cover they can provide and their greater risk of loss.
Specialist insurers
Should you decide to go direct, bear in mind that not all insurers will offer cover for high risk-occupations, but there are some companies who specialise in this field. Your choices will be more limited but you should be able to find enough options to compare. Insurers don’t necessarily assess risk in the same way so you needn’t settle on the first one you find.
Specialist brokers
Finding the right policy on your own could seem daunting, so an alternative is to use a specialist broker. They’ll find out from you what your ideal policy would be and possibly raise questions that you haven’t thought of. Once they’ve got an exhaustive picture of your circumstances and expectations they’ll search the market for the right fit. This could give you the best result, although you should be aware that they may take commission or charge for their advice. You can find one through the British Insurance Brokers Association.
Comparison websites
These sites tend not to offer insurance specifically for high-risk occupations. That doesn’t mean you won’t find a policy, but, if you do, it may not meet all your needs and it could still cost you as much as a genuine high-risk option.
Employer group insurance
Some employers in high-risk industries assume responsibility for the dangers faced by their employees and provide group cover. However, this can be fairly basic so if your employer operates such a scheme, it’s worth finding out exactly how it works, what it pays out and whether there are any exclusions or limitations. If you’re a contractor or freelancer you may not be covered by a group policy so you may want to explore your own solution.
If you’re in a high-risk occupation and you’re looking for insurance, there are some additional forms of cover you might find helpful. You may find a policy that does everything you need, but if not, you may want to consider the extra protection provided by these options.
Income protection insurance
High-risk occupation life insurance helps you provide for your family and dependents if you die as a consequence of doing your job. But what if you’re injured or taken ill and have to take extended sick leave? Will your employer continue to pay you and, if so, for how long? If you’re a self-employed contractor or freelancer, how will you support yourself and your family with no money coming in?
Income protection insurance is designed for precisely these eventualities. You take out a policy while you’re fit and working, then, if you get sick and have to stop working, you can make a claim. You could receive as much as 70% of your normal monthly income until you’re able to go back to work or until the end of your claims period, which could be 2 years. There may be restrictions and exclusions for some dangerous jobs, but income protection is well worth exploring.
Critical illness insurance
This pays out if you are diagnosed with any of the serious illnesses specified in the policy. The conditions covered by insurers vary but generally include heart attack, stroke, cancer, MS, Parkinson’s disease and the loss of a limb. This is helpful if you suffer a condition that is debilitating but not fatal. Cover for terminal illness is usually included in life insurance policies.
Accidental death cover
Accidental death and dismemberment insurance, to give it its full name, does exactly what you’d expect. If your main life insurance policy has restrictions on what it will cover, this may be a good way to fill in the gaps. Apart from fatal accidents, it pays out if you suffer specific serious injuries such as paralysis or the loss of a limb, hearing, eyesight or speech.
Why risk your income?
Protect yourself and your family today
The life insurance sector has expanded over time, with innovations that aim to suit every situation. High-risk insurance may be available in many forms so here’s a brief summary of the main ones.
Whole life
This covers you for the whole of your life so it will pay out to your chosen beneficiaries whenever you pass away. Many whole life policies build up a cash value, acting as a form of savings and investment as well as life insurance.
Term life
When you take out the policy you specify how many years you’d like it to last. People often choose this to cover fixed-term financial obligations like mortgages and university tuition fees. For those in high-risk jobs a term life policy could be used to cover them until retirement.
Level
This can be a whole or term life policy, in which the eventual payout is fixed from the beginning. It is often cheaper than other types of policy, but since the final figure stays the same it doesn’t account for the effects of inflation over many years.
Increasing
Available for term or whole life policies, the eventual payout increases during the life of the policy and continues in force and you should expect the premiums to rise each year. Reviewing the amount of cover periodically gives you the chance to keep pace with inflation
Decreasing
Another variant that’s available for both term and whole life policies, the amount of cover decreases over time. The premiums don’t reduce, but their level is calculated to reflect the decreasing final payout. This may be a good option if you want to cover commitments like mortgages, where the amount repayable gradually falls until the loan is fully paid off.
The main advantages are:
- It gives you cover that may not be available anywhere else
- Policies can be customised to your individual circumstances
- It allows you to meet any legal requirements of your job
- It may offer ancillary support services, such as post-accident rehabilitation
The main disadvantages are:
- The premiums are inevitably higher
- A limit on the amount of cover may be imposed
- Even though you’re insured against the dangers of your job there may still be some restrictions and exclusions
- The underwriting process (the questions asked and information gathered by the insurer) may be longer and stricter
Life insurance for high risk occupations
Frequently asked questions
Fact-checked and reviewed by Kiruba Shankar Eswaran or another licensed agent on our team. Read our editorial standards.
This guide is for general educational purposes and is not financial advice. Cover, eligibility and terms vary by insurer and by policy. Always read the policy documents for the full terms, limitations and exclusions before you buy.
Related resources
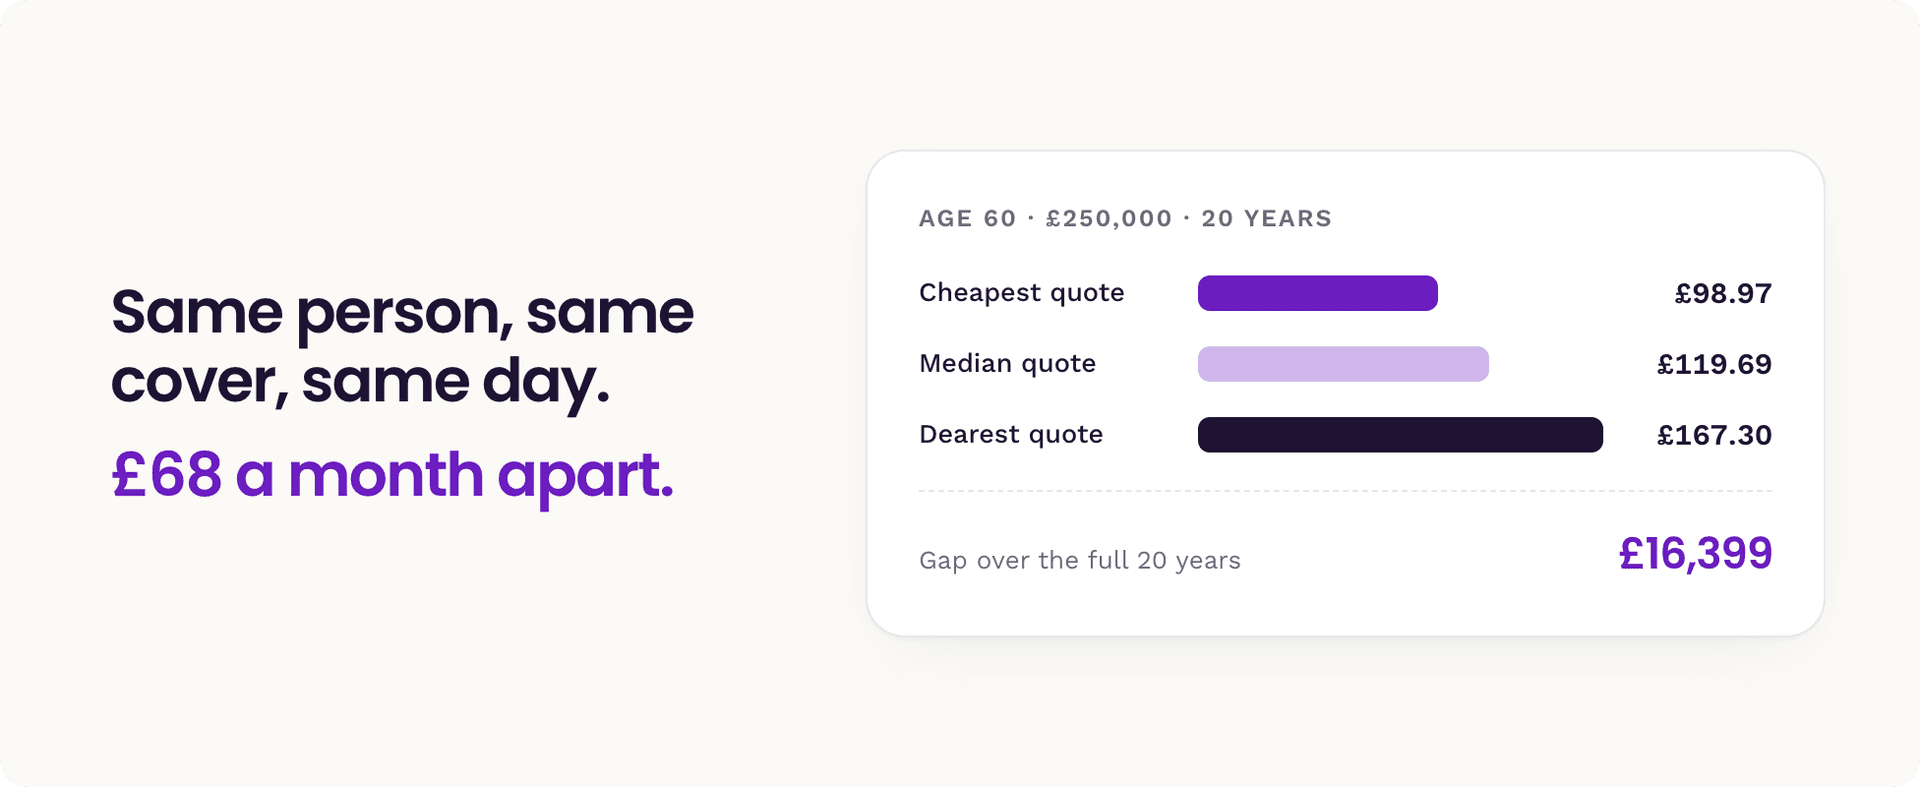
Life insurance cost UK 2026: what 6,557 real insurer quotes show
We collected 6,557 live quotes from UK life insurers in September 2026 and compared every one. Median prices by age, cover amount and policy length, how much smoking multiplies your premium, why bigger policies cost less per pound, and how mortgage protection compares with level cover.
What Is Term Life Insurance? UK Guide & Quotes (2026)
A complete UK guide to term life insurance: how it works, what it costs, the main policy types, underwriting, how it compares with whole of life, and the top UK providers.
6 Financial Resilience Tips for 2026
New Year, new money mindset. It’s time to break free from financial anxiety once and for all. Here are six simple tips to boost your financial resilience in 2026 and bring you peace of mind all year long!
Life Insurance for Young Adults
Life insurance for young adults doesn't have to be complicated or costly. This comprehensive guide covers why purchasing life insurance as a young adult locks in lower rates based on current health and how to pick the proper policy length and provider for your situation.
Turning Customer Curiosity Into Confidence: Theea's Coverage Calculator
Introducing Theea's Coverage Calculator: the intuitive insurance tool inspired by thousands of customer conversations that turns anxiety into tailored advice and confusion into confident choices.
Meet Your Newest Eleos Perks
We’re expanding our perks with two new additions designed to turn good intentions into healthy habits. Discover everything you can get for free with an Eleos policy.