Statutory sick pay vs income protection
Contents
To deal with the challenge of paid sick leave, UK governments have tried various solutions. Statutory Sick Pay (SSP) was introduced in 1983 to replace state sickness benefits. It shifted the financial burden of short-term sick leave away from the state by placing a legal duty on employers to pay their employees a minimum level of sick pay.
SSP provides very modest support. It was reformed significantly in April 2026, and while those changes widened who can claim it, they did not make it generous. For most people it still falls a long way short of their normal earnings.
Long-term sickness remains a serious problem for the UK workforce and economy. Office for National Statistics figures put the number of people aged 16 to 64 who are economically inactive because of long-term sickness at around 2.75 million, close to the highest levels on record. Many of those people are self-employed and have never been eligible for SSP at all.
What SSP pays
The rate
The current rate of Statutory Sick Pay is £123.25 a week, or 80% of your average weekly earnings, whichever is lower. Earnings are averaged over an eight-week period.
That 80% element is new. It exists so that SSP cannot exceed what a low-paid employee would normally have earned. If you earn more than about £154 a week, the flat rate of £123.25 is what applies.
Qualifying days
How much you actually receive depends on the days you normally work, which are known as qualifying days. SSP is paid for the full days you are off sick that you would normally have worked.
If you usually work three days a week and you are unable to work for four weeks, you are paid for three qualifying days in each of those weeks, so twelve days in total rather than a full four weeks' worth.
Who gets SSP, and for how long
What changed on 6 April 2026
If you have read about SSP before, two of the rules you may remember no longer apply. The Employment Rights Act reforms took effect on 6 April 2026 and changed the following.
- Waiting days have been abolished. SSP is now payable from your first full day of sickness absence. Previously the first three qualifying days were unpaid and you needed to be off for at least four days in a row before anything was payable.
- The lower earnings limit has been abolished. SSP is now available to all eligible employees regardless of their weekly earnings. Previously you had to earn at least the lower earnings limit to qualify at all, which excluded roughly 1.3 million low-paid workers.
So the current position is straightforward. To qualify for SSP you need to:
- Be classed as an employee and have done some work for your employer
- Have been ill for at least one full working day
- Tell your employer within the time set out in your contract, or within seven days if your contract does not say
Agency workers may also be entitled. The self-employed are not.
Evidence
The definition of sickness includes mental illness severe enough to prevent you doing your job. For absences of more than seven days in a row your employer can require a fit note from a doctor or other healthcare professional such as a nurse, pharmacist, occupational therapist or physiotherapist. For the first seven days you can normally self-certify.
When SSP runs out
Your employer must pay SSP for up to 28 weeks. After that it stops. Your employer should give you form SSP1, which you use to claim state support instead. The main options are New Style Employment and Support Allowance and Universal Credit, depending on your National Insurance record and household circumstances.
Twenty-eight weeks sounds like a long time until you are the one counting it. If your recovery runs past that point, SSP simply ends.
Contractual sick pay: check your contract
SSP is a legal minimum, not a target. Many employers pay more through a company sick pay scheme, and the terms should be set out in your contract of employment.
The most generous packages may carry you through a long absence comfortably. Others pay full salary for a few weeks and then drop straight to SSP. A significant number pay nothing above the statutory minimum at all.
Find out exactly what yours does, and for how long, because that single fact determines how you should set up any cover you buy alongside it. This is the detail that most people only discover when they need it.
How income protection fills the gap
Income protection insures you against losing your income when illness or injury stops you working. Because it replaces a meaningful proportion of your earnings, it does a fundamentally different job from SSP.
Two points before the detail. You need to take out a policy while you are fit and working: if you wait until you are already on sick leave, you will not be able to get cover. And unlike SSP, income protection is available to the self-employed as well as employees, which matters given how many long-term sick people fall outside the statutory system entirely.
If you have a health history you are worried about disclosing, that does not necessarily rule you out, though it may affect the terms you are offered. Our guide to income protection and pre-existing conditions covers how underwriters approach this.
What it pays
Most UK income protection policies pay between 50% and 65% of gross income, as MoneyHelper sets out. Citizens Advice describes it as "about a half to two-thirds of your earnings before tax".
The cap is deliberate. Insurers do not offer to replace 100% of your earnings, because a benefit worth more than your salary would create an obvious problem.
Why the tax treatment matters more than the headline percentage
This is the part that is almost always left out, and it changes the arithmetic completely.
Where you pay the premiums yourself from taxed income, the benefit is normally paid to you tax free. HMRC's guidance confirms the exemption under section 735 ITTOIA 2005, and notes that "there is no limit on the amount of payments that can be received free of tax".
So a policy paying 60% of gross salary is not replacing 60% of your standard of living. It is replacing 60% of your gross pay with money you keep in full, which typically works out much closer to your normal take-home pay. That is the comparison to make.
The position is different for employer-funded schemes, covered further down.
The deferred period
The deferred period, sometimes called the waiting period, is the gap between becoming unable to work and your first benefit payment. The common options are 4, 13, 26 and 52 weeks. A longer deferred period means a lower premium.
Note that you generally choose from your insurer's standard list rather than naming any number of weeks you like, which matters when you are trying to dovetail with company sick pay.
The benefit period
The benefit period is the maximum time a single claim can be paid. Short-term policies commonly pay for 1, 2 or 5 years; full-term policies pay until you can return to work or the policy ends, whichever comes first.
The benefit period only bites if you are off for longer than it lasts, so choose one you think is realistic. A longer benefit period costs more. As long as you keep paying premiums, most policies let you claim again for a new period of incapacity.
Using SSP and income protection together
It is not an either-or choice. The two are designed to sit at different points on the timeline.
Example: Rachel, statutory minimum sick pay only
Rachel earns £2,500 a month gross, which is £30,000 a year, and takes home £2,000. Her employer pays the statutory minimum and nothing more. She has a policy paying 60% of gross with a four-week deferred period.
She is injured and is off work for 26 weeks.
- Her gross weekly pay is around £577, so 80% of it is well above the flat rate. She receives £123.25 a week in SSP, which is roughly £534 a month.
- SSP runs for up to 28 weeks, so it covers her whole absence.
- For the first four weeks she has SSP alone.
- From week five her income protection begins paying £1,500 a month, tax free.
Against a normal take-home of £2,000, the policy alone replaces three quarters of her spending power, and it does so because the benefit is not taxed. Add SSP and she is close to whole.
One caution worth building into your planning: policies differ on whether state benefits are taken into account. Some insurers set the maximum benefit after allowing for state support, and Citizens Advice notes that the typical half-to-two-thirds figure reflects this. Check how your policy treats SSP rather than assuming the two simply stack.
Example: David, eight weeks of full company sick pay
David has the same earnings, but his employer pays full salary for the first eight weeks of any absence. He is off work for 16 weeks.
There is no eight-week deferred period on most insurers' lists, so David has to choose either side of it. He picks 13 weeks, which keeps his premium lower.
- Weeks 1 to 8: full pay from his employer.
- Weeks 9 to 13: company sick pay has ended, so he is on SSP alone at £123.25 a week. This is the gap he has consciously accepted in exchange for a cheaper premium.
- Weeks 14 to 16: his income protection starts paying £1,500 a month tax free, alongside SSP, until he returns to work.
Had he chosen a four-week deferred period instead, his cover would have started during the period his employer was still paying him in full, which most insurers will take into account. The lesson is to match the deferred period to the point your employer's support actually stops, choosing the nearest available option and understanding the consequence either way.
Three things to get right
Level of cover
Work from the tax-free benefit, not the headline percentage, and compare it against your take-home pay rather than your gross salary.
If your employer runs its own sick pay scheme, be aware that money you receive from it is commonly taken into account by your insurer, unlike SSP in many policies. That does not make cover pointless, because employer schemes usually end long before your benefit period does. It just means the value sits in the later part of a long absence.
Length of cover
Decide the benefit period by reference to how long your employer would keep paying you and what would happen after that. If company sick pay stops at eight weeks and SSP stops at 28, a policy with a one-year benefit period covers a very different risk from one that pays to retirement.
Setting the deferred period
Line the deferred period up with the point your income actually falls away.
- If you are on the statutory minimum from day one, a short deferred period is usually right, because £123.25 a week does not stretch far.
- If your employer pays full salary for a set period, choose the deferred period closest to the end of it.
- If you have savings you would genuinely be willing to run down, a longer deferred period cuts the premium meaningfully.
Group income protection
Personal policies are relatively straightforward. Group schemes work differently.
An employer can simply pay you from its own funds while you are off sick, or it can fund sick leave through group income protection insurance. In that case the policy is owned by the employer, the insurer pays the benefit to the employer, and the employer pays it on to you through payroll.
The tax treatment follows from that structure: because it reaches you as earnings, it is taxed like earnings, with income tax and National Insurance deducted. This is the key difference from a personal policy funded from your own taxed income, where the benefit is normally received tax free.
Group schemes often pay out for long periods and typically involve little or no individual medical underwriting, which can make them valuable if your health history would complicate a personal application. Check how long the cover actually lasts, since some schemes have a limited payment period, and make your own arrangements if there is a gap.
The bottom line
Statutory Sick Pay is a genuine safety net, and the April 2026 reforms made it a wider one by removing the waiting days and the earnings threshold. But £123.25 a week for up to 28 weeks is a floor, not a replacement income.
Used well, income protection covers the two things SSP cannot: the shortfall between the statutory minimum and what you actually earn, and the period after week 28 when SSP stops altogether.
How safe is your income?
If Statutory Sick Pay is not enough, there is another way.
Sources
- GOV.UK, "Statutory Sick Pay: what you'll get"
- GOV.UK, "Statutory Sick Pay: eligibility"
- GOV.UK, "Rates and thresholds for employers 2026 to 2027"
- Employment Rights Act: Statutory Sick Pay factsheet
- Office for National Statistics, economic inactivity due to long-term sickness
- MoneyHelper, "What is income protection insurance?"
- Citizens Advice, "Income protection insurance"
- HMRC Insurance Policyholder Taxation Manual, IPTM6110
This guide is for general information and is not financial, tax or legal advice. SSP rates and rules change, and policy features, definitions and tax treatment vary by insurer and by individual circumstances. Always check the current position on GOV.UK, read the policy documents and consider speaking to a regulated adviser before you buy.
Statutory sick pay vs income protection
Frequently asked questions
Fact-checked and reviewed by Kiruba Shankar Eswaran or another licensed agent on our team. Read our editorial standards.
This guide is for general educational purposes and is not financial advice. Cover, eligibility and terms vary by insurer and by policy. Always read the policy documents for the full terms, limitations and exclusions before you buy.
Related resources
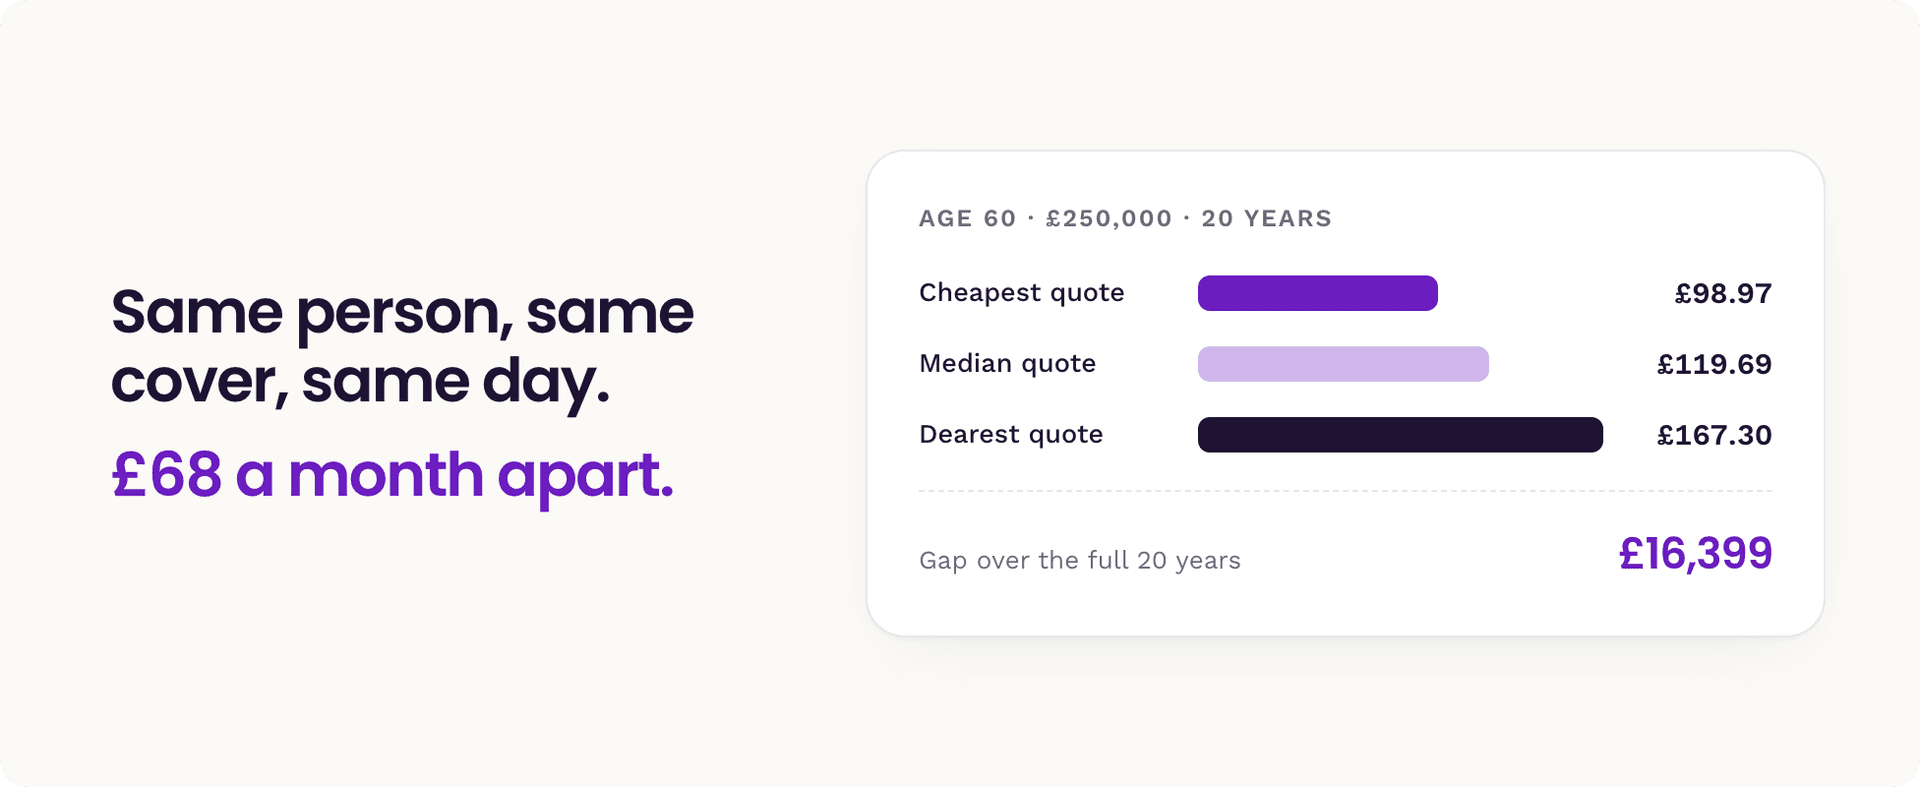
Life insurance cost UK 2026: what 6,557 real insurer quotes show
We collected 6,557 live quotes from UK life insurers in September 2026 and compared every one. Median prices by age, cover amount and policy length, how much smoking multiplies your premium, why bigger policies cost less per pound, and how mortgage protection compares with level cover.
What Is Term Life Insurance? UK Guide & Quotes (2026)
A complete UK guide to term life insurance: how it works, what it costs, the main policy types, underwriting, how it compares with whole of life, and the top UK providers.
6 Financial Resilience Tips for 2026
New Year, new money mindset. It’s time to break free from financial anxiety once and for all. Here are six simple tips to boost your financial resilience in 2026 and bring you peace of mind all year long!
Life Insurance for Young Adults
Life insurance for young adults doesn't have to be complicated or costly. This comprehensive guide covers why purchasing life insurance as a young adult locks in lower rates based on current health and how to pick the proper policy length and provider for your situation.
Turning Customer Curiosity Into Confidence: Theea's Coverage Calculator
Introducing Theea's Coverage Calculator: the intuitive insurance tool inspired by thousands of customer conversations that turns anxiety into tailored advice and confusion into confident choices.
Meet Your Newest Eleos Perks
We’re expanding our perks with two new additions designed to turn good intentions into healthy habits. Discover everything you can get for free with an Eleos policy.