Income protection and zero hours contracts
Contents
A central part of the gig economy, the concept of a zero hours contract existed long before it had a name. It entered the public consciousness as a phenomenon in the late 1990s when many large employers used it as a way to hire relatively cheap, casual labour. It was largely unregulated because it fell outside the bounds of existing employment law.
It’s different today, thanks to a combination of legal challenges and new legislation. Zero hour contract rights now entitle you to:
- National Minimum Wage and National Living Wage
- Itemised payslips
- A written statement of the terms of work
- Paid statutory holiday
- Daily and weekly rest periods and rest breaks
- A 48-hour limit on the average working week
- Protection against discrimination
- A work environment where risks to health and safety are properly controlled.
The government is planning further reforms to strengthen the rights of workers on zero hours contracts.
However, since you’re classed as a worker and not an employee, there are some areas in which you are still at a disadvantage.
Recent research shows that 1.1 million adults in the UK have a zero hours contract as their main source of income. Most of them are under 25 and only 6.1% have job security, regular income and employment rights.
The biggest disadvantage of most zero hours contracts is the lack of a steady income. Earnings can fluctuate enormously from week to week, which makes it extremely hard to budget not just for the day-to-day essentials but also for longer term plans. Add to that the constant threat of being unable to work because of illness or injury and you have a picture of extreme financial precariousness. An income that’s irregular at best can disappear overnight and there’s very little support available if that happens.
Do you get sick pay on a zero hours contract?
Casual contract sick pay has always been a contentious subject and recent legislation has tried to solve the problem of sick pay and zero hours contracts. If you earn at least an average of £123 a week and your employer deducts tax and National Insurance you could qualify for statutory sick pay. However, the current minimum is £118.75 a week and your employer is not obliged to pay any more than this.
Your average weekly pay is typically worked out according to your ‘qualifying days’, which are the regular shifts you work on the same days from week to week. If your employer refuses to pay you SSP they must explain in writing using form SSP1. If they don’t, or you dispute their decision, you can complain to HMRC.
The state offers some income support for part-time workers, but to be eligible you must be working for no more than 16 hours a week.
Can you get income protection on a zero hours contract? The short answer is yes, but the long answer reveals the difficulties that zero hours workers can encounter. Some insurers will offer policies specifically designed for zero hours workers while others have standard policies with enough flexibility to apply to your situation.
The challenges for zero hours workers seeking income protection
Income
Establishing your average income is difficult, as we’ve already seen. Income protection cover and payouts are based on regular wages, so it can be hard to prove your real earnings. The ‘qualifying days’ method could understate your actual income so it’s a good idea to keep your own detailed records of the money you make.
Irregular employment
By their very nature, zero hours work can be unstable and gig economy income unreliable. Insurers might consider you to be a higher risk than someone in a regular job and this might mean your premiums will be higher.
Multiple jobs
You are legally entitled to take as many zero-hours jobs as you wish and your employers cannot object or do anything to prevent this. When applying for income protection insurance you should take into account your earnings from all the work you do, however small.
Policy types
It’s important to consider the possible impact of your fluctuating income in deciding what policy will give you the greatest support.
Guaranteed benefit policies
The payout is based on your average earnings at the time you take out your insurance. It gives you baseline cover but doesn’t take account of any increase in your earnings. The premiums you pay and the benefits you can claim are fixed at the start and won’t change over time.
Indemnity benefit policies
The payout is based on your income at the time you make a claim. If you’re earning less than when you took out the policy, your benefit will be correspondingly lower.
Reviewable policies
These enable the insurer to review your policy periodically. If they do, they may adjust your premiums and cover, which could be particularly suitable for people with irregular income.
Zero hours income can be uncertain
Why not get the certainty of a replacement income when you aren't able to work?
Whether you’re still looking for the best policy or you’re ready to apply, here are a few things to bear in mind.
Make sure your financial records give as accurate a picture as possible of your earning patterns, going back as far as possible during your time as a zero hours contract worker. This is vital as your proof of earnings.
Shop around to find the best deal and even speak to a broker or independent adviser.
If you’re concerned about keeping the monthly premiums you pay for your policy as low as possible, you could settle for a slightly lower payout and you can also reduce the cost by setting a longer waiting period. This is the time you agree to wait between stopping work and receiving your first payment under the policy. You choose the period, which could be anything from one week to several months. The longer the waiting period the lower the premiums.
Be prepared to answer questions about your work, your health, your medical history and your lifestyle. Answer fully and accurately or you risk any claim you make being rejected and your policy cancelled.
If your work is particularly dangerous it may be hard to get cover, or you may find that any injury or illness related to your job is excluded from your policy.
If you’re unable to get income protection you could opt for accident-only insurance. This doesn’t cover you for illness, but if you are injured in an accident it can pay out money to help you through your recovery.
Life insurance is a very effective way of looking after family and dependents who rely on your income. Naturally it doesn’t help you personally if you have to stop working, but should you pass away it means your loved ones can be looked after.
Income protection and zero hours contracts
Frequently asked questions
Fact-checked and reviewed by Kiruba Shankar Eswaran or another licensed agent on our team. Read our editorial standards.
This guide is for general educational purposes and is not financial advice. Cover, eligibility and terms vary by insurer and by policy. Always read the policy documents for the full terms, limitations and exclusions before you buy.
Related resources
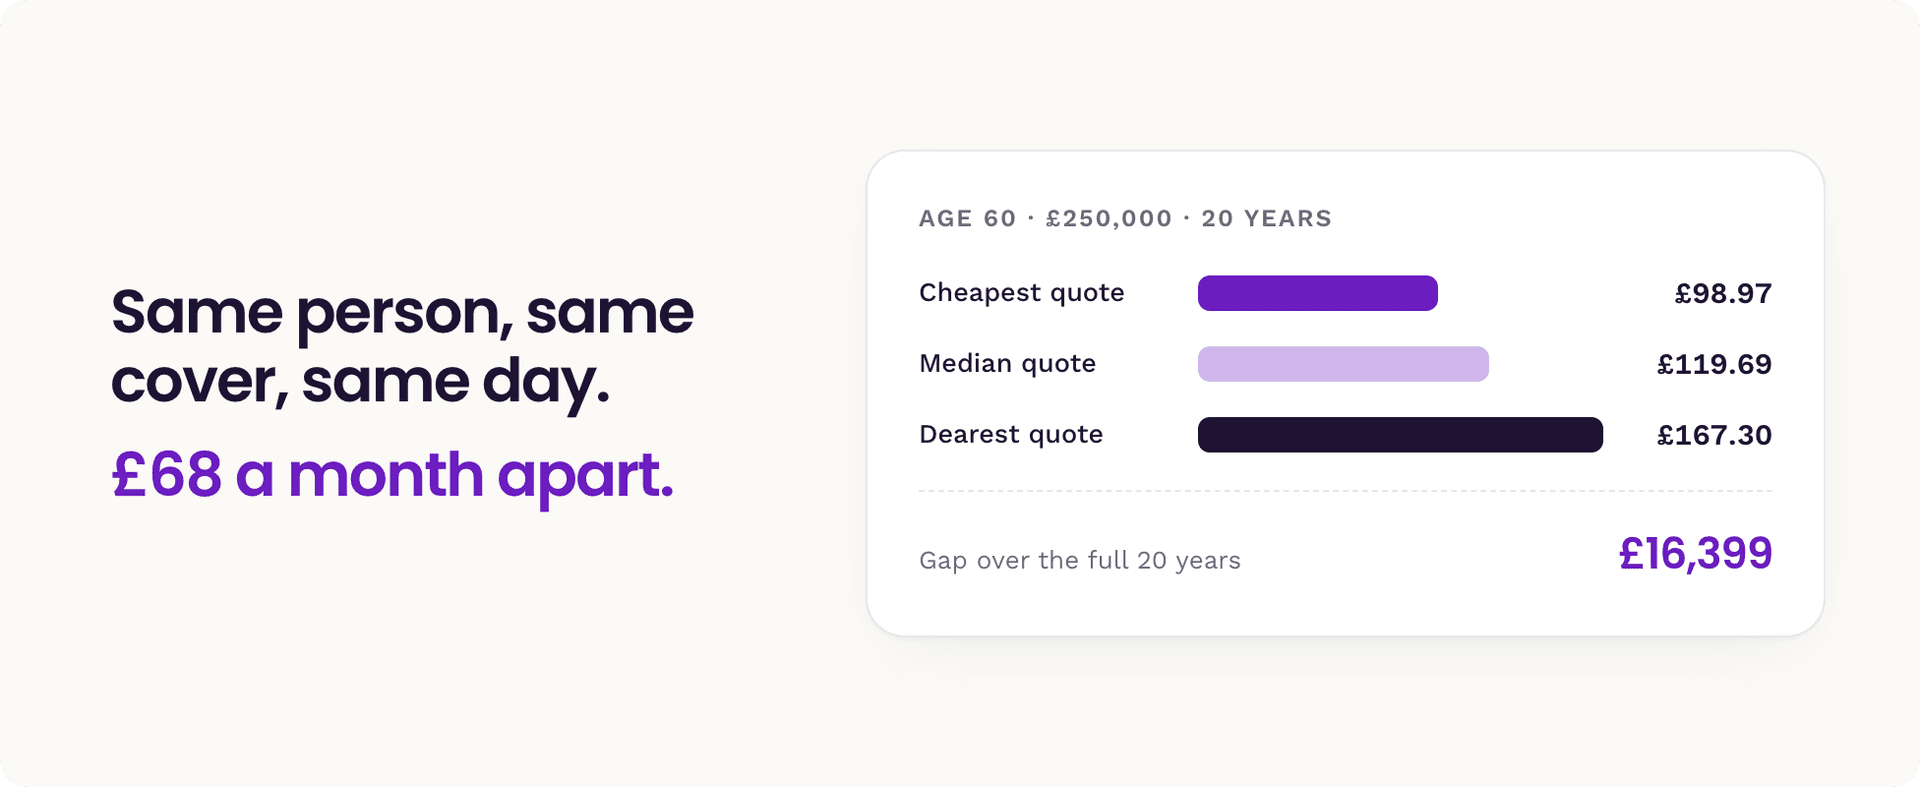
Life insurance cost UK 2026: what 6,557 real insurer quotes show
We collected 6,557 live quotes from UK life insurers in September 2026 and compared every one. Median prices by age, cover amount and policy length, how much smoking multiplies your premium, why bigger policies cost less per pound, and how mortgage protection compares with level cover.
What Is Term Life Insurance? UK Guide & Quotes (2026)
A complete UK guide to term life insurance: how it works, what it costs, the main policy types, underwriting, how it compares with whole of life, and the top UK providers.
6 Financial Resilience Tips for 2026
New Year, new money mindset. It’s time to break free from financial anxiety once and for all. Here are six simple tips to boost your financial resilience in 2026 and bring you peace of mind all year long!
Life Insurance for Young Adults
Life insurance for young adults doesn't have to be complicated or costly. This comprehensive guide covers why purchasing life insurance as a young adult locks in lower rates based on current health and how to pick the proper policy length and provider for your situation.
Turning Customer Curiosity Into Confidence: Theea's Coverage Calculator
Introducing Theea's Coverage Calculator: the intuitive insurance tool inspired by thousands of customer conversations that turns anxiety into tailored advice and confusion into confident choices.
Meet Your Newest Eleos Perks
We’re expanding our perks with two new additions designed to turn good intentions into healthy habits. Discover everything you can get for free with an Eleos policy.