What's in an income protection policy?
Contents
In principle it's fairly self-explanatory. You take out an income protection policy while you’re fit and in work, then if you get injured or fall ill and have to take time off work you can make a claim and receive regular payments to replace your income until you’re able to work again.
You work out how much you’ll need, based on your regular expenses. The amount you’re entitled to when you claim depends on how much you can afford to pay in monthly premiums and there are a few other options to help you adjust the cost.
Income protection is often misunderstood. It doesn’t help that policy documents can spend 30 pages or more in describing income protection features. Here’s an explanation of the main ones..
Benefit amount
This is the level of income protection cover for which you’re insured, or, in other words, the amount of money you can expect to receive each month when you make a successful claim. What you’ll get is partly determined by how much you normally earn and the maximum is either 65% of that income or £2,000, whichever is lower. It’s important to note that the 65% limit applies to your pre-tax income. This won’t be far off what you normally take home after basic rate income tax and national insurance, which together amount to 28%.
Benefit period
This is the maximum time for which your policy will pay you under a single claim. The most common periods are 1, 2 and 5 years. Eleos policies offer you 1 or 2 year periods. If you’re able to return to work before you reach this limit your payments will stop. If you are still unable to work beyond this limit your payments will also stop. Remember: this is the period for a single claim. You can claim as many times as you need to as long as you hold your policy and keep up the premiums.
Benefit term
This is the entire life of your policy. Whatever your age when you take out the policy, it can usually last until your 70th birthday. You can cancel it at any time, but unless you do, or anything happens to invalidate your policy, such as non-payment of premiums, you can stay covered for the whole of your working life.
Premium
This is the amount you pay each month to maintain your policy. It usually increases each year on the anniversary of the policy start date.
Waiting period
Practically all income protection policies ask you to choose a waiting period. This is the time that must pass when you claim, between getting ill or injured and receiving the first of your monthly payments. In many cases, policyholders can get by on their last monthly wage and don’t need immediate payment. Some people receive sick pay from their employer which might last weeks or even months or just the minimum Statutory Sick Pay. Having an income protection waiting period means you can time your benefit payments to start when your sick pay ends.
The longer the waiting period you choose when you take out your policy, the lower your premiums will be.
Definition of incapacity
Generally you have to be physically or mentally unable to perform the duties of your normal job and this inability needs to be confirmed by a doctor or healthcare professional. However, there are usually three levels of incapacity:
Own occupation: you can’t do your specific job
Suited occupation: you can’t do your specific job or any other job suited to your abilities and experience
Any occupation: you can’t work for your employer in any capacity
Own occupation is the most popular choice, because it’s the easiest definition to meet.
Your obligations
What your insurer requires from you boils down to the honesty and accuracy of the information you give (including any changes in circumstances) and the regular payment of your premiums, in full and on time.
Your insurer’s obligations
The duties of your insurer are varied, largely based on good faith. Swift, efficient handling of your claim, consistent, clear communication and compliance with data protection rules are perhaps the key ones.
Looking for income protection?
Eleos makes it clear and simple
Apart from the waiting period and the benefit period there are some other common limitations you should be aware of.
Exclusions
Income protection exclusions fall into two categories: those that apply generally and those that are specific to you.
General exclusions
Certain health conditions may mean you’re not able to get cover at all, but these are usually limited to very serious illnesses, which make your risk uninsurable.
Most conditions won’t stop you from buying a policy but if any of them is the cause of your inability to work you won’t be covered. These include:
Dangerous jobs - such as working in the fire service, at heights, underwater or with certain types of chemical
Hazardous pursuits - these aren’t related to your job and include extreme sports
Normal pregnancy - pregnancy is not considered an issue of poor health unless it involves complications
Self-harm - if your inability to work is caused partly or wholly by your own actions you won’t be covered, an exclusion that includes self-inflicted injury, failure to follow medical advice and even complications from cosmetic surgery.
Travel abroad - this is a limitation rather than an exclusion, which may reduce the period for which you can receive benefit payments if you’re outside the country when you claim.
Personal exclusions
These are placed on your policy based on the information you give about your own circumstances and the most common ones are:
Pre-existing conditions - any condition you already have when you apply
Occupational - anything about your particular job that puts you at unusually high risk
Other sources of income
This is not an exclusion, but if you have other sources of alternative income, such as employee sick pay or other insurance policies, the amount you can receive in total can’t exceed the amount of your cover. For example, if you’re insured for 65% with two income protection policies you won’t get 130% of your salary, just 65% in total.
The benefits of income protection can cover you in ways you might not expect. These are two examples:
Working persons benefit
If your illness or injury stops you from working in your usual job but you’re able to do other work at a lower wage, you may be entitled to working persons benefit, which will make up your reduced earnings to the level for which you’re insured.
House persons benefit
If you make a claim and become unemployed, a student or a house person while your claim is still being paid, you may not be entitled to the full amount of your insurance but you could receive 50% of your cover. (A house person is someone who takes over housekeeping duties at home.)
Your income protection policy will also provide details of how to make a claim, often with a link to an online claim form. Apart from the form itself you’ll need to give the insurer:
- Proof of your income and income loss
- Proof of your incapacity verified by a doctor or healthcare professional
- Any other information and evidence the insurer asks for
Income protection policies frequently offer flexible options, of which the most common are these:
Waiver of premium - you don’t have to pay your premiums while you have an active claim
Reviewable cover - you can apply to increase your cover during the life of your policy and sometimes you can reduce it.
Payment break - there may be periods when you feel you don’t need your cover, such as if you take a career break or a sabbatical, and rather than cancelling your policy you can put it on hold: both your cover and your premiums will be paused.
Guaranteed insurability option - this allows you to increase your level of cover without going through a new assessment process if a major event occurs in your life such as getting married or having children.
Indexation - your cover automatically increases in line with inflation
Look out for other benefits beyond financial ones, such as:
Rehabilitation support - insurers sometimes provide resources to speed up your recovery
Discretionary benefits - although these aren’t part of your insurance contract, you’ll often have access to free extras like private GP services and money-saving offers.
Finally, your policy will tell you about:
- Your right to cancel
- The role of the Financial Conduct Authority and the Financial Services Compensation Scheme is protecting your money and your interests
- How the insurer complies with data protection legislation
- How to contact customer support
- How to make a complaint, first through the insurer’s internal mechanism and, if that doesn’t solve your problem, by contacting the Financial Ombudsman Service
What's in an income protection policy?
Frequently asked questions
Fact-checked and reviewed by Kiruba Shankar Eswaran or another licensed agent on our team. Read our editorial standards.
This guide is for general educational purposes and is not financial advice. Cover, eligibility and terms vary by insurer and by policy. Always read the policy documents for the full terms, limitations and exclusions before you buy.
Related resources
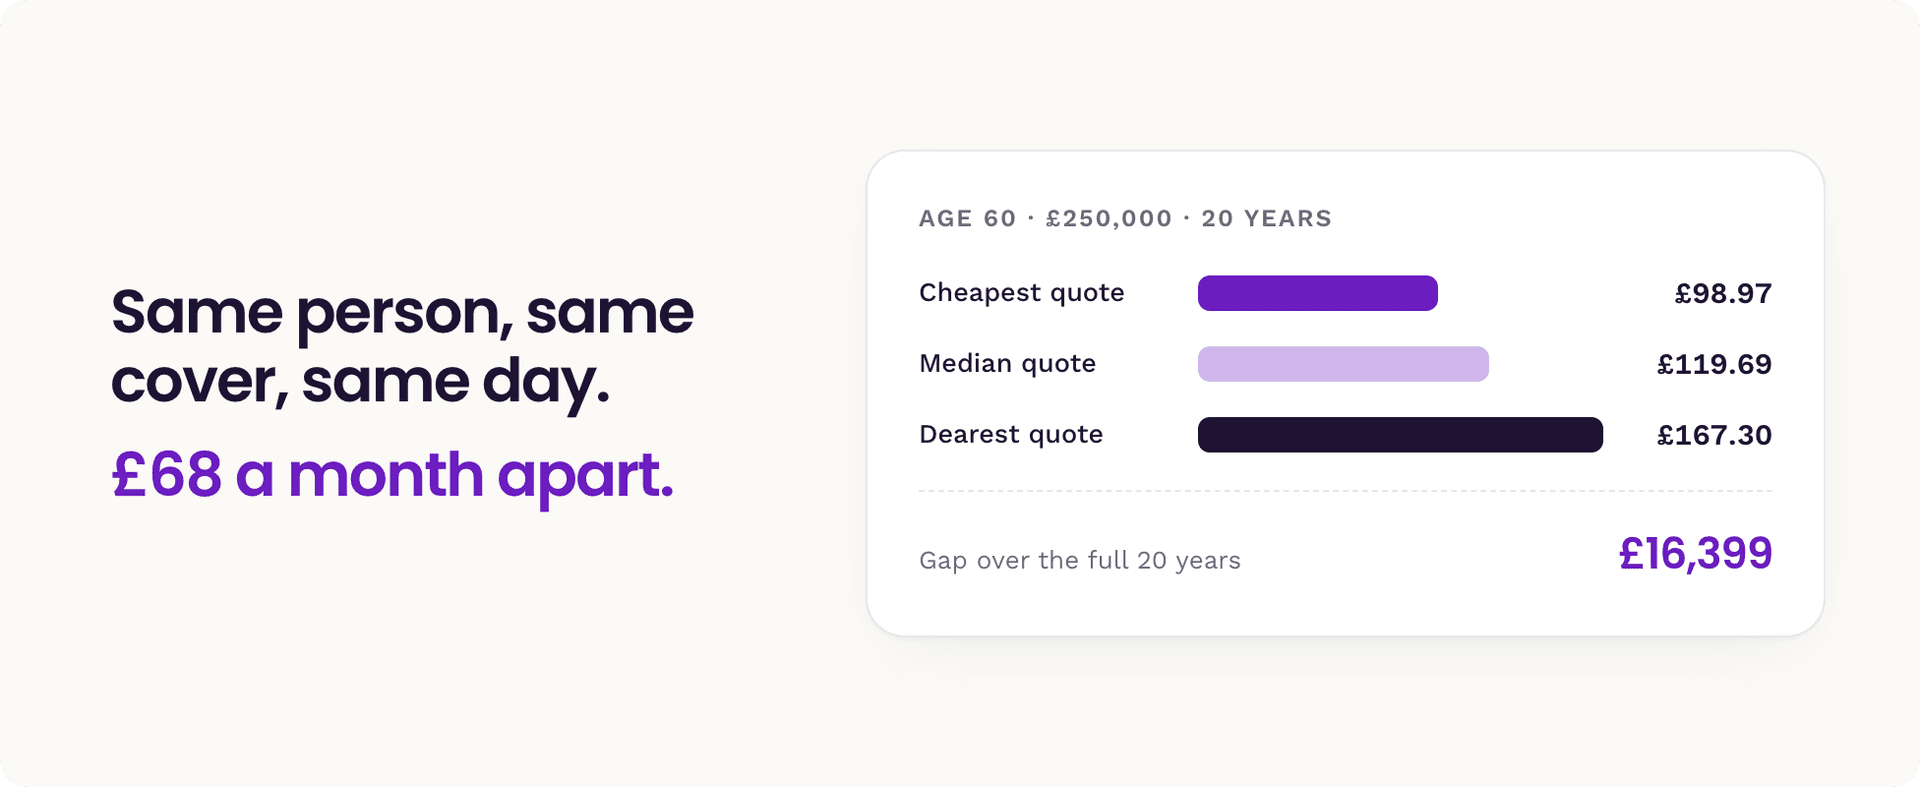
Life insurance cost UK 2026: what 6,557 real insurer quotes show
We collected 6,557 live quotes from UK life insurers in September 2026 and compared every one. Median prices by age, cover amount and policy length, how much smoking multiplies your premium, why bigger policies cost less per pound, and how mortgage protection compares with level cover.
What Is Term Life Insurance? UK Guide & Quotes (2026)
A complete UK guide to term life insurance: how it works, what it costs, the main policy types, underwriting, how it compares with whole of life, and the top UK providers.
6 Financial Resilience Tips for 2026
New Year, new money mindset. It’s time to break free from financial anxiety once and for all. Here are six simple tips to boost your financial resilience in 2026 and bring you peace of mind all year long!
Life Insurance for Young Adults
Life insurance for young adults doesn't have to be complicated or costly. This comprehensive guide covers why purchasing life insurance as a young adult locks in lower rates based on current health and how to pick the proper policy length and provider for your situation.
Turning Customer Curiosity Into Confidence: Theea's Coverage Calculator
Introducing Theea's Coverage Calculator: the intuitive insurance tool inspired by thousands of customer conversations that turns anxiety into tailored advice and confusion into confident choices.
Meet Your Newest Eleos Perks
We’re expanding our perks with two new additions designed to turn good intentions into healthy habits. Discover everything you can get for free with an Eleos policy.