6 Financial Resilience Tips for 2026

It’s time to break free from financial anxiety once and for all.
Here are six simple tips to boost your financial resilience in 2026 and bring you peace of mind all year long!
Your "must-cover" number is the minimum amount of money you need each month to cover all essentials. By nailing it down, you instantly gain a rock-solid foundation for all your financial plans.
- List your essential expenses. Jot down your must-pay monthly costs: rent or housing, utilities, groceries, insurance, transportation, debt payments, and healthcare basics.
- Add them up to find your “Must-Cover” number. The total sum of these essentials is the minimum income you must cover each month to stay afloat.
- Save it somewhere handy. Record the number in a safe place (like a notes app or budget spreadsheet) where you can reference it easily, then use it as your starting point before setting any other goals.
Calculating this baseline is the cornerstone of financial stability. Once you know your bare-minimum budget needs, it’s easier to make decisions without guessing or stressing.
It also helps you gauge how much income protection you might need from insurance in a worst-case scenario, ensuring your essentials would still be funded.
Starting an emergency fund at the beginning of the year helps you build a stress-busting savings habit before life gets busy. Even a modest cushion can turn a full-blown crisis into a minor inconvenience.
- Pick a small savings goal you can realistically fund. For example, a starter emergency fund of £500 (or even just £250) can cover a surprise car repair or unplanned expense.
- Automate a small weekly amount into a separate savings account. Setting up an auto-transfer of £10–£25 each week will grow into a nice buffer over time without spreading your wallet too thin.
- Label the account “Emergency Fund.” Treat this as your personal safety net, not a splurge account, and keep it off-limits except for true emergencies.
Savings help with short-term surprises, while other safeguards like life insurance or income protection can help cover larger or longer-lasting disruptions that would otherwise overwhelm your finances.
Unexpected expenses feel overwhelming when there’s nothing to fall back on. Protection policies add an extra layer of reassurance if and when crisis ever hits.
In 2026, smarter spending is the name of the game. Small monthly subscriptions like streaming services, apps, or meal kits you forgot to cancel can stack up quickly and drain cash just as quietly. Luckily, a quick review of your charges can free up money without requiring any major lifestyle changes.
- Scan your last month’s bank statement for recurring charges or subscriptions. Identify at least one service you haven’t used or completely forgot about that won't be missed in 2026.
- Cancel or downgrade that service right away. If you’re not using it regularly or getting value from it anymore, you should cancel your plan completely or switch to a cheaper option as soon as possible
- Redirect that money to savings right after. If you just cancelled a £15 monthly subscription, make sure to immediately transfer that exact amount into your emergency fund to use for future expenses.
Every unnecessary charge you trim is money back in your pocket. You can even use the extra cash to further strengthen your safety net by funnelling those savings into more financial safeguards.
Upgrading your insurance cover or adding to a rainy-day fund will serve you far better than a rarely used subscription service.
Financial resilience starts with facts. If you’re an employee banking on your job’s benefits, you need to know exactly what your workplace covers — and what they don’t. Understanding the fine print upfront helps you plan ahead and stay prepared.
- Check your employer’s policies. Look up how much statutory sick pay or employer sick pay you have, how long it lasts, and what happens if you need extended leave. If your company offers income protection, make sure you know how it works.
- Identify any gaps or fine-print details. Look for waiting periods, exclusions, or limitations, then note anything you find that might leave you uncovered.
- Verify additional benefits. See if your job offers any income replacement programmes or whether supplementary insurance options are available.
Figuring out these key details ahead of time means fewer surprises during already stressful situations.
If you happen to find any gaps in your workplace policies, insurance can help fill them, especially for income protection during longer absences.
True financial resilience means planning for surprises rather than simply hoping they won’t happen to you. A sustainable budget will keep you moving through your 2026 resolutions long after January’s motivation fades.
- Add an “unexpected expenses” line to your budget. Set aside a small amount each month specifically for random costs so that one surprise expense doesn’t end up wrecking your whole plan.
- Automate one key priority immediately. Pick one important goal, such as saving up or paying debts, and set up a recurring automatic transfer around it.
- Schedule a 10-minute weekly money check-in. Set a specific time to sit down each week, look over your accounts, and check all your charges so you stay aware and prepared for any potential surprises later on.
Strict plans can cause burnout quick. Make each step you take towards success a reason to reward yourself.
New Year’s resolutions don’t fail from a lack of people caring or trying. They fall apart when the goals are too vague or overwhelming for people to actually initiate. Taking consistent small steps for 30 days gives you the control and confidence you need to conquer 2026.
- Tackle the basics. Calculate your Must-Cover Number and start an emergency fund. Secure your financial foundation first and foremost.
- Check in on your safety nets. Midway through the month is the best time to review workplace benefits, identify coverage gaps, and reallocate savings from cancelled subscriptions.
- Start mapping your future. Choose one next step you can commit to by the end of the month. This could mean researching insurance options, adjusting savings automation, or any action that strengthens your financial shield.
Pairing small financial habits with accessible protection helps plans hold up in real life, not just on paper. In just one month’s time, you can transform good intentions into tangible progress all year long.
Financial resilience comes from steady progress, not drastic change.
You don’t have to overhaul your entire financial life overnight.
Whether you decide to cancel one subscription or finally open that savings account, taking just one small step today will set the tone for a more secure 2026.
So take a deep breath, pick one small action from this list, and start now.
Your future self (the one with much more money and way less stress) will be really glad you did. 💜
Fact-checked and reviewed by Kiruba Shankar Eswaran or another licensed agent on our team. Read our editorial standards.
This guide is for general educational purposes and is not financial advice. Cover, eligibility and terms vary by insurer and by policy. Always read the policy documents for the full terms, limitations and exclusions before you buy.
Related resources
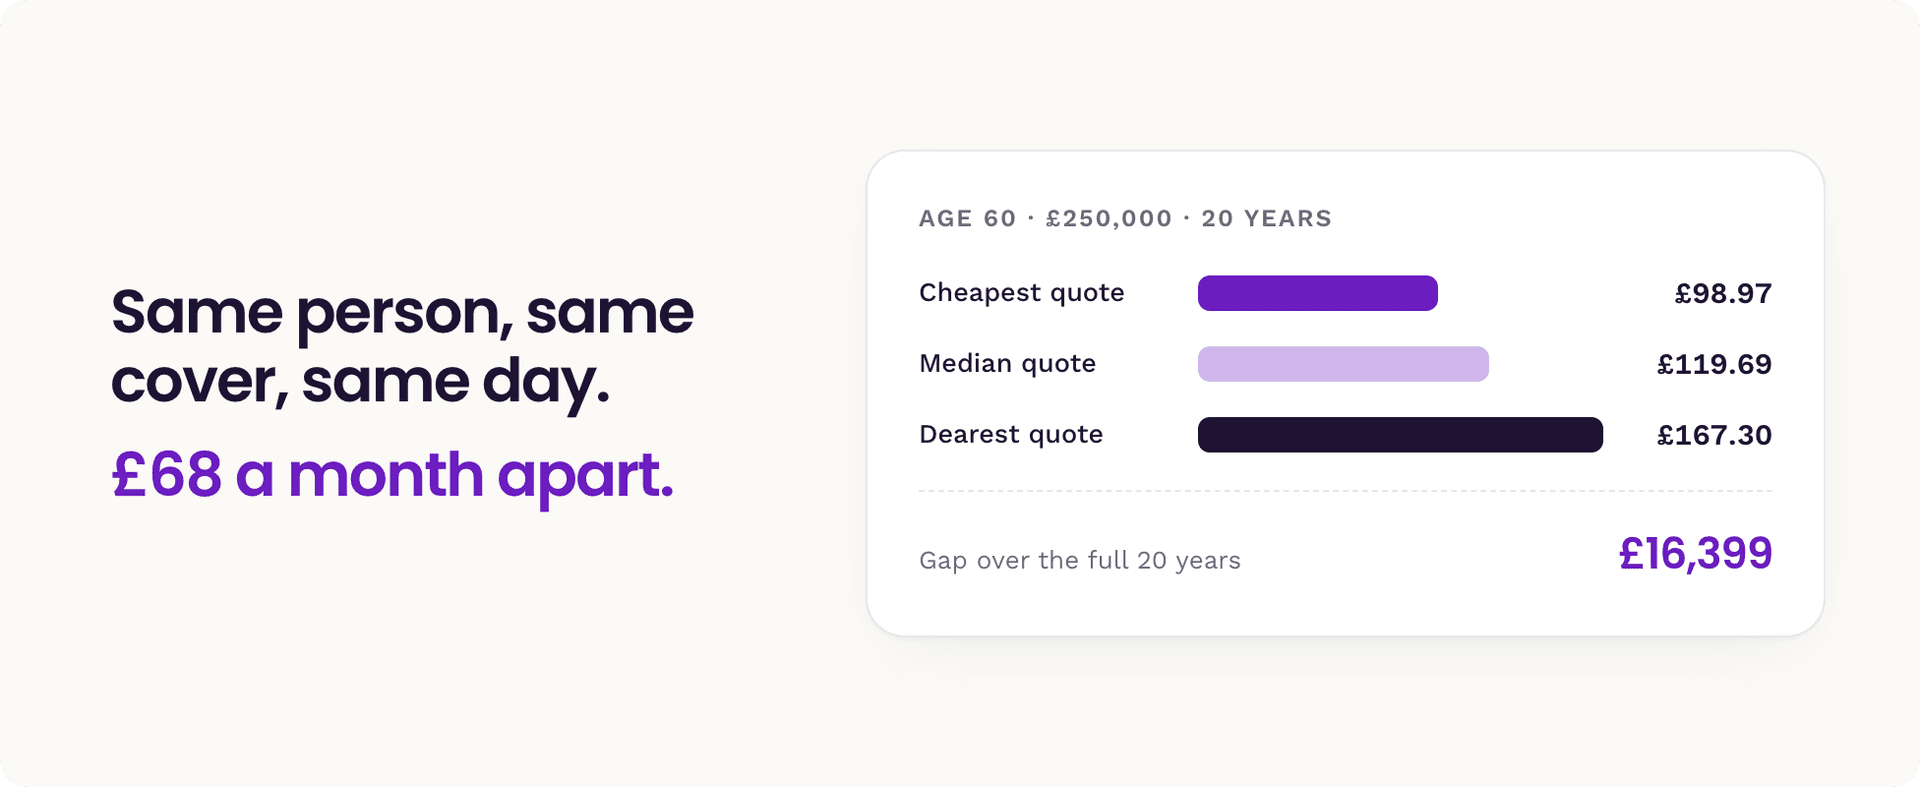
Life insurance cost UK 2026: what 6,557 real insurer quotes show
We collected 6,557 live quotes from UK life insurers in September 2026 and compared every one. Median prices by age, cover amount and policy length, how much smoking multiplies your premium, why bigger policies cost less per pound, and how mortgage protection compares with level cover.
What Is Term Life Insurance? UK Guide & Quotes (2026)
A complete UK guide to term life insurance: how it works, what it costs, the main policy types, underwriting, how it compares with whole of life, and the top UK providers.
Life Insurance for Young Adults
Life insurance for young adults doesn't have to be complicated or costly. This comprehensive guide covers why purchasing life insurance as a young adult locks in lower rates based on current health and how to pick the proper policy length and provider for your situation.
Turning Customer Curiosity Into Confidence: Theea's Coverage Calculator
Introducing Theea's Coverage Calculator: the intuitive insurance tool inspired by thousands of customer conversations that turns anxiety into tailored advice and confusion into confident choices.
Meet Your Newest Eleos Perks
We’re expanding our perks with two new additions designed to turn good intentions into healthy habits. Discover everything you can get for free with an Eleos policy.