What is insurance underwriting?
Contents
Underwriting is a term you’ll come across in many financial sectors, including loans and investments, but it originated in insurance. Lloyd’s of London began in the 17th century by getting wealthy people to insure the risk of sea voyages. These people committed themselves to covering the risk by signing their names at the bottom of - or under - the insurance contract, hence they were known as the underwriters.
The concept of underwriting became more complex as insurance policies grew more sophisticated and today it describes the process by which insurance companies assess the risk associated with every policy, from life insurance to pet and mobile phone insurance. A lot of underwriting is automated, especially for policies that insure possessions, but the manual element remains.
What is underwriting? Essentially, it’s risk assessment. When you apply for insurance, the questions you answer to determine your eligibility are part of the underwriting process. But how do insurance companies assess risk? On the whole, they can only do this by looking at the information you give them. Sometimes they will ask for additional information – for example, medical reports for health, life and income protection insurance, or structural surveys for buildings insurance. But generally, they rely on the honesty and accuracy of the applicant.
This may seem very trusting of them and frankly it is. That’s why insurance policies routinely include conditions to deal with misinformation, whether intentional or accidental. These can range from not paying a claim to cancelling the policy. Deliberate fraud is taken very seriously.
Is your income at risk?
Illness or injury forces millions of people to stop working
When you apply for any policy you trigger the insurance underwriting process, which we’ll now look at it in some detail.
Risk assessment
Insurers need to decide whether to approve or reject your application. The other option is to grant you insurance but with exclusions or limitations. Much of this can be done using algorithms and other digital methods, which is how insurers are able to give instant decisions. However, most applications lead to a telephone interview, in which the insurer’s agent reviews your answers and may ask additional questions. Fully digital underwriting is still relatively rare – as it happens, Eleos is among the first companies to offer this for both income protection and life insurance.
What is an insurance underwriter?
It’s the underwriter’s job to evaluate the risks involved in the various categories of insurance:
- General insurance: possessions, pets, car, travel, etc
- Protection insurance: life, health and income protection
- Commercial insurance: specifically designed for business needs
- Reinsurance: where part of the insurer’s risk is shared with one or more other insurers.
What does an underwriter do? He or she gathers and analyses the information given on the application form, sometimes asking for more if he or she identifies a potentially greater risk than expected. If no special circumstances exist the process is fairly straightforward and can be largely automated. If you’ve ever bought car insurance you may be familiar with this, since insurers apply universally applicable criteria such as your age, the model of your car and the area where you live.
Underwriters often call on the help of specialists where an assessment is particularly difficult, such as doctors, surveyors and other experts.
Pricing
For the consumer at least, this is usually the most important outcome of the underwriting process. If the insurer agrees to cover them, what will they charge? The level of premiums for the policy is directly related to all the risk factors considered by the underwriter.
Decision
When the underwriter has concluded their assessment, they have three options:
- Accept;
- Accept with exclusions; or
- Decline
What factors does an underwriter look at?
It depends on what the insurance is for. For protection insurance such as life or income, they will normally consider:
- Age
- Current health
- Personal or family medical history
- Lifestyle issues such as hobbies and habits like smoking and drinking
- Occupation
If the type of insurance applied for is refused, the insurer may suggest alternatives such as accident-only or critical illness insurance.
If the application is approved but with reservations, the premiums might be higher than they would otherwise be, or certain conditions and events might be excluded from the cover, in addition to any standard exclusions.
It might seem an overly bureaucratic business but insurance underwriting risk assessment has benefits for insurers, policyholders and the insurance industry as a whole.
For insurers
Insurance companies make their money from risk, but if the risk is too severe it can make their business unviable. An insurer that loses money is no use to anyone. Risk management keeps the company financially sound.
It also enables insurers to keep the cost of their policies as low as possible. If they suffer financial consequences as a result of their exposure to risk, the only way they can make up their losses is by raising premiums.
For policyholders
The same reasons why underwriting is valuable for insurers apply to their customers. The limitation of risk keeps prices lower for all and gives insurers the solvency to honour claims when they’re made.
For the insurance market
Insurance may not be on everyone’s list of favourite purchases but, like it or not, it’s an essential protection provided by private companies. The stability of those companies is vital to the efficiency of a market on which virtually all of us rely, in some way or another.
We’ve already looked at how technology is speeding up the application and underwriting experiences. It can offer the same advantages to the claims process, meaning policyholders receive their payments more quickly than if every claim has to be manually approved. What are the consequences of removing this human element?
Positives
Technology can increase the speed and precision of policy and claims management.
It allows insurers to use predictive analytics in making more accurate underwriting assessments.
Health apps, wearable devices, like black boxes in cars, enable insurers to tailor and adapt policies to the individual, giving more appropriate and even reactive cover.
Negatives
Consumers are generally concerned that digital technology allows companies to gather huge amounts of personal information. While it’s true that data breaches do occur, it can be argued that the dangers are very slight with robust data protection legislation doing a good job of protecting the individual.
Another negative that’s more about perception than reality is the feeling that automation deprives applicants and policyholders of a voice if they’re unhappy. For that reason, it’s important to find an insurer with a customer support team that’s genuinely responsive. In fact, insurance companies are obliged by law to operate an internal complaints procedure. If it fails to satisfy a customer, they can take their objections to the Financial Ombudsman, whose decision is binding on the company while leaving the customer with the option to pursue legal action.
Because insurance companies don’t always enjoy the best reputations, many people feel that the underwriting process unfairly denies them cover. We can’t guarantee that this doesn’t happen, but we’re confident that the instances of this are vanishingly small.
The insurance market is one of the most heavily regulated industries in the UK. Several statutory organisations have extensive powers to oversee the conduct of insurance companies, including the Financial Conduct Authority, the Prudential Regulation Authority and the Financial Services Compensation Scheme.
The underwriting decisions of insurers are rarely set in stone and can always be negotiated. Insurers also have discretion, which means they aren’t constrained by their own underwriting rules and are free to make exceptions and concessions in individual cases.
When you apply for insurance, you are entering into the underwriting process, so it’s worth being prepared.
- Make sure you can lay your hands on documents relating to matters like your identity, health and income.
- Do what you can to reduce your risk factors, such as adopting healthier lifestyle habits.
- Be ready to answer all the questions you’re asked as fully, honestly and accurately as you can.
- Refer back to this article so you’ll be able to anticipate the likely questions and outcomes.
What is insurance underwriting?
Frequently asked questions
Fact-checked and reviewed by Kiruba Shankar Eswaran or another licensed agent on our team. Read our editorial standards.
This guide is for general educational purposes and is not financial advice. Cover, eligibility and terms vary by insurer and by policy. Always read the policy documents for the full terms, limitations and exclusions before you buy.
Related resources
Life insurance cost UK 2026: what 6,557 real insurer quotes show
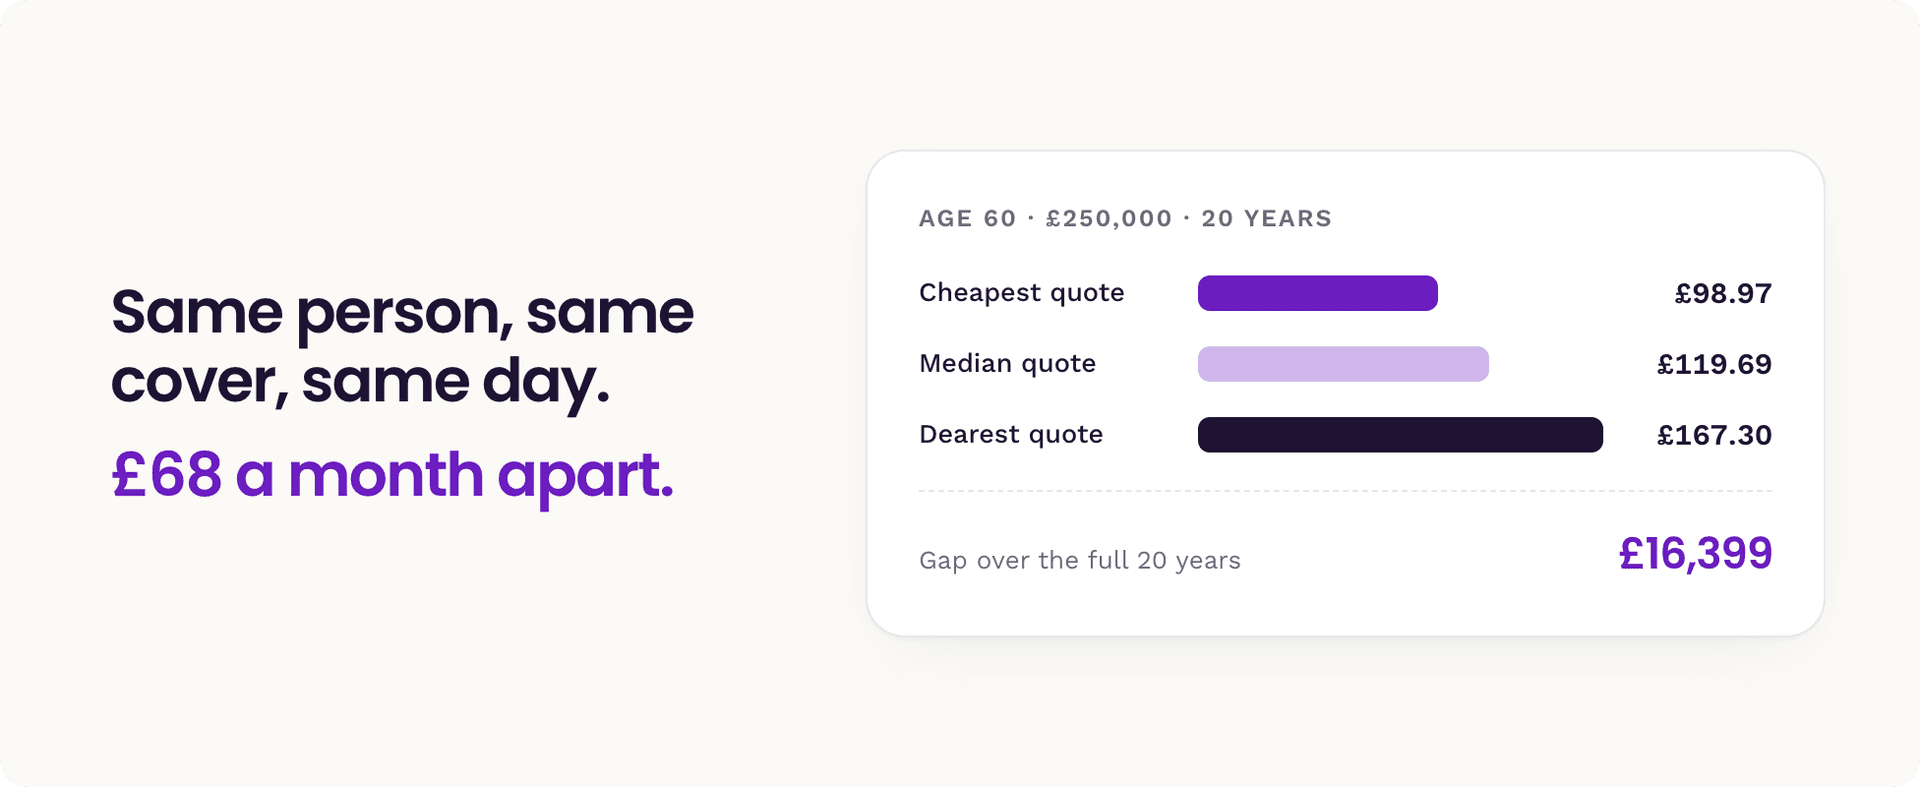
We collected 6,557 live quotes from UK life insurers in September 2026 and compared every one. Median prices by age, cover amount and policy length, how much smoking multiplies your premium, why bigger policies cost less per pound, and how mortgage protection compares with level cover.
What Is Term Life Insurance? UK Guide & Quotes (2026)
A complete UK guide to term life insurance: how it works, what it costs, the main policy types, underwriting, how it compares with whole of life, and the top UK providers.
6 Financial Resilience Tips for 2026
New Year, new money mindset. It’s time to break free from financial anxiety once and for all. Here are six simple tips to boost your financial resilience in 2026 and bring you peace of mind all year long!
Life Insurance for Young Adults
Life insurance for young adults doesn't have to be complicated or costly. This comprehensive guide covers why purchasing life insurance as a young adult locks in lower rates based on current health and how to pick the proper policy length and provider for your situation.
Turning Customer Curiosity Into Confidence: Theea's Coverage Calculator
Introducing Theea's Coverage Calculator: the intuitive insurance tool inspired by thousands of customer conversations that turns anxiety into tailored advice and confusion into confident choices.
Meet Your Newest Eleos Perks
We’re expanding our perks with two new additions designed to turn good intentions into healthy habits. Discover everything you can get for free with an Eleos policy.